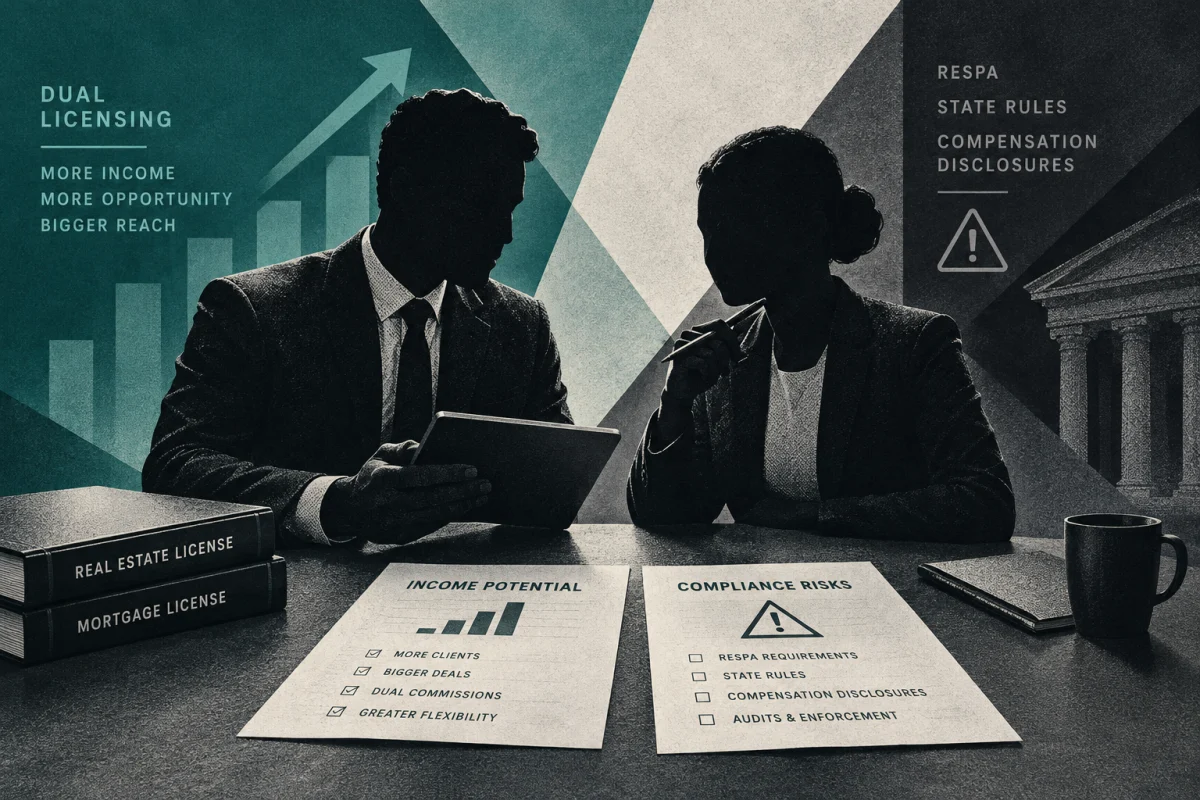
The American housing market has faced a protracted period of compressed transaction volumes, elevated mortgage rates, and lingering affordability challenges. In response to these persistent headwinds, real estate brokerages and mortgage companies are continuously exploring innovative avenues to diversify revenue streams. Among the strategies gaining traction is dual licensing—a professional arrangement that allows individuals to hold credentials both as licensed real estate agents and mortgage loan officers (MLOs). By bridging the gap between property sales and financing, dual-licensed professionals are positioning themselves to capture multiple facets of transaction fees, offering an integrated client experience while shoring up personal and corporate income against market volatility.
Recent industry data underscores the existence of this dual-hatted workforce, while simultaneously highlighting the regulatory and operational complexities that accompany it. As the boundary lines between real estate sales and mortgage origination continue to blur, industry participants are closely monitoring how dual licensing impacts consumer protection, compensation compliance, and overall market efficiency.
Mapping the Footprint of Dual Licensing
A recently published analysis by data firm RETR sheds light on the prevalence of dual-licensed professionals across the United States. Utilizing advanced name-matching methodologies, the study identified 3,729 distinct matches between real estate agents and mortgage loan officers where an agent’s top-producing loan officer shared the exact same name.
Geographically, the phenomenon is heavily concentrated in specific real estate markets. California alone accounted for a striking 40% of these identified matches. When expanding the view to include Florida, Texas, and Arizona, the top four states collectively represented nearly 71% of all dual-licensed professionals captured in the analysis. These states have historically experienced high transaction volumes, dynamic demographic shifts, and competitive housing markets, making them prime testing grounds for revenue-diversifying strategies among agents.
However, industry experts caution that data-driven approximations have inherent limitations. RETR’s analysis relied primarily on name-matching algorithms rather than independent verification of dual licensure through state and federal regulatory databases. Furthermore, the methodology inherently excludes professionals who hold both licenses but actively choose not to originate mortgages for their own real estate clients, as well as those who split their time unequally or prioritize one specific role over the other. Consequently, the actual footprint of dual licensing may be even broader than current figures indicate, encompassing a hidden segment of the workforce operating quietly across various regional markets.
The Catalyst: Protecting Clients and Expanding Expertise
To understand what drives real estate professionals to navigate the rigorous testing, continuing education, and compliance burdens of holding two distinct licenses, one must look at the grassroots level of the housing sector. For Shawn McNeil, broker and owner of HomeFlo and an active loan officer for Mpire Financial Group, the decision to pursue dual licensing stemmed from a desire to exercise greater control over the financing ecosystem for his clients.
McNeil spent nine years working exclusively in real estate before obtaining his MLO license approximately 18 months ago. His transition was catalyzed by mounting frustration over seeing personal friends and high-value clients navigate the complex mortgage landscape, only to be funneled toward large retail lenders and saddled with uncompetitive interest rates and unfavorable loan terms.
“I would watch my big, high-dollar, personal friends go to these big-box retailers and just get absolutely crushed with an interest rate,” McNeil explained in an interview. “I was like, at first, I’m going to go get licensed so that I can talk through these things and be knowledgeable in this.”
Today, McNeil divides his professional schedule roughly 50/50 between real estate sales and mortgage origination. His client base primarily consists of personal acquaintances and real estate investors. While he occasionally functions as both the selling agent and the lender on the exact same transaction, he notes that this dual-representation scenario remains the exception rather than the rule.
McNeil anticipates that an increasing number of real estate agents will pursue MLO credentials as broader market conditions remain challenging. He points to technological advancements—specifically the proliferation of artificial intelligence tools that simplify the process of researching complex mortgage guidelines, underwriting criteria, and loan program requirements—as a major catalyst lowering the barrier to entry.
“I think more agents are going to realize that the job on the loan officer side is getting easier from a guideline standpoint, and I think that they’re going to more and more convert to doing both over time,” McNeil stated. He added that while agents are frequently told that partnering with loan officers is mutually beneficial, many do not fully grasp the intricacies of the mortgage process or how to select the right lender until they acquire firsthand experience.
Nevertheless, dual-licensed practitioners maintain professional boundaries. McNeil clarifies that he does not attempt to originate every loan for clients who utilize his brokerage services. When his own mortgage platform cannot accommodate a specific loan product, or when a borrower’s financial profile requires specialized programs outside his direct expertise, he actively refers them to external lenders.
Navigating the Regulatory and Compliance Labyrinth
While the financial upside of dual licensing is evident, the regulatory framework governing the practice is notoriously strict. Professionals attempting to operate in both capacities must navigate a complex web of federal statutes, state-level licensing mandates, and organizational oversight.
At the federal level, the Real Estate Settlement Procedures Act (RESPA) casts a wide net over any financial arrangements between real estate brokerages and mortgage entities. RESPA strictly prohibits the payment or acceptance of kickbacks, unearned fees, or referral fees for real estate settlement services. When a single individual acts as both agent and loan officer, compliance teams must ensure that compensation structures do not violate anti-referral provisions or create conflicts of interest that could harm the consumer.
Furthermore, state licensing authorities—such as the Nationwide Multistate Licensing System & Registry (NMLS) for loan officers and state real estate commissions for agents—enforce rigorous oversight regarding advertising, fiduciary duties, and consumer disclosures. Dual-licensed professionals must meticulously separate their fiduciary responsibilities, ensuring that clients understand precisely in what capacity the professional is acting at any given stage of the transaction.
To mitigate compliance risks and maintain absolute transparency, industry leaders emphasize the necessity of proactive legal counsel and comprehensive disclosure protocols. McNeil noted that he worked directly with legal professionals to draft stringent disclosure frameworks implemented across his brokerage. Under this policy, every real estate client receives explicit notice informing them that McNeil is a licensed loan officer and the owner of the brokerage firm, regardless of whether they ultimately choose to utilize his mortgage financing services.
“We require 100% disclosure… Even if you’re not using my services, we still disclose to you that I am a licensed loan officer and I own the real estate brokerage,” McNeil emphasized. These disclosures are delivered electronically and acknowledged by clients long before any transaction moves into the active contract phase, ensuring alignment with consumer protection standards.
Broader Industry Implications and Future Outlook
The rise of dual licensing reflects a structural evolution within the housing ecosystem. As commission compression, rising operational costs, and fluctuating inventory levels squeeze profit margins for traditional brokerages and independent mortgage banks alike, professionals are increasingly seeking ways to capture a larger share of the transaction value chain.
From an economic perspective, the dual-licensed model offers distinct advantages. By streamlining communication between the sales agent and the loan officer—who, in this case, are the same person—potential friction points that typically cause transaction delays are significantly reduced. Document collection, underwriting inquiries, and milestone tracking can be tightly coordinated, theoretically lowering fallout rates and accelerating closing timelines.
However, industry analysts maintain a measured outlook regarding whether dual licensing will transform from a tactical niche into a mainstream industry standard. While data from firms like RETR highlights concentrated adoption in high-cost, high-volume states like California, Florida, Texas, and Arizona, widespread national adoption faces formidable hurdles. The time commitment required to maintain active real estate licenses and MLO credentials, complete mandatory continuing education, and manage the administrative burdens of two distinct regulatory bodies can be overwhelming for many practitioners.
Moreover, consumer perception remains a variable factor. Some buyers and sellers may prefer working with independent, specialized professionals who maintain distinct advisory roles, viewing dual representation as a potential conflict of interest despite rigorous legal disclosures.
As housing market conditions continue to evolve, the viability of dual licensing will likely depend on regulatory stability, technological tools that ease administrative friction, and the individual practitioner’s ability to balance dual responsibilities ethically and effectively. For entrepreneurial agents navigating a challenging market cycle, holding both keys—to the home and to the financing—represents a powerful mechanism to control their professional destiny and maximize earning potential.