The retail landscape across the United States is quietly preparing for a fundamental transformation driven by legislative action on the West Coast. By 2028, everyday grocery runs will look distinctly different for American consumers. Traditional petroleum-based plastics are steadily vanishing from shelves, replaced by molded fiber bowls, cardboard fruit cartons, and transparent polyethylene terephthalate trays. These subtle shifts on supermarket shelves are the direct result of California’s Senate Bill 54 (SB 54), a landmark packaging law whose fully realized regulatory framework took effect in May 2026.
Although enacted at the state level, the influence of SB 54 extends far beyond California’s borders. Major consumer goods manufacturers and multinational packaging suppliers are heavily reformulating their production lines for a nationwide market rather than maintaining separate, state-specific supply chains. This corporate strategy ensures that consumers across the country will encounter the physical manifestations of California’s policy. Simultaneously, the implementation of the law has ignited intense legal scrutiny, revealing deep tensions between environmental advocates, state regulators, and industry stakeholders over the pace and strictness of corporate accountability.
The Scale of the Plastic Crisis and the Legislative Mechanism
To comprehend the monumental shift initiated by SB 54, policymakers and industry analysts point to decades of unchecked plastic production. Plastic emerged as the global default for packaging due to its unique combination of low cost, durability, and lightweight structural integrity. However, this explosive growth catalyzed a profound environmental waste crisis. According to data compiled by the U.S. Environmental Protection Agency (EPA), plastic waste accounted for just 0.4% of all municipal solid waste generated in the United States in 1960. By 2018, that figure had surged to 12.2%, reflecting an escalating reliance on single-use materials.
Packaging constitutes a critical portion of this ecological burden. Industry analyses indicate that approximately 36% of all manufactured plastic is utilized exclusively for packaging purposes, with an estimated 85% of that material ultimately terminating in landfills. In response to these escalating volumes, the California legislature enacted SB 54, establishing stringent statutory mandates. The core objectives of the legislation require producers to achieve a 25% reduction in single-use plastic packaging by 2032 while guaranteeing that all single-use packaging sold or distributed within the state is genuinely recyclable or compostable.
The primary enforcement mechanism driving these adjustments is Extended Producer Responsibility (EPR). Under an EPR framework, the traditional financial and operational burdens of municipal waste management, sorting, and recycling are shifted away from local taxpayers and municipal governments and placed directly onto the producers and brand owners. By internalizing the end-of-life costs associated with their goods, manufacturers face a potent financial incentive to minimize material usage, redesign packaging for seamless recyclability, and eliminate problematic chemical compounds entirely.
Legal Challenges and Environmental Advocacy
Despite the implementation of CalRecycle’s final regulations in May 2026, the governance of SB 54 remains fiercely contested in the courtroom. On June 2, a coalition of prominent environmental organizations—including Oceana, the Natural Resources Defense Council (NRDC), and the Californians Against Waste Foundation—filed a formal lawsuit in the San Francisco Superior Court.
The plaintiffs argue that the finalized regulations weaken the statutory intent of the original legislation. Specifically, the legal challenge contends that the rules incorporate excessive exclusions for major categories of plastic packaging, empower producers to secure indefinite exemptions, and fail to establish robust safeguards against problematic technologies that the law was originally designed to restrict. Environmental attorneys argue that these perceived loopholes undermine the integrity of the state’s recycling targets, potentially allowing large corporations to bypass foundational source-reduction mandates. As litigation proceeds, state regulators and industry compliance groups face mounting pressure to defend the rigor of the oversight framework.
Phasing Out Problematic Materials
SB 54 establishes broad compliance benchmarks that exert immense pressure on hard-to-recycle and hazardous packaging formats. Producers are aggressively working toward the 2032 statutory deadlines by systematically redesigning, replacing, or outright discontinuing several high-risk material categories.
Polystyrene Foam (EPS)
Expanded polystyrene, widely recognized by the brand name Styrofoam, has faced severe regulatory contractions. Used ubiquitously in takeout food containers, single-use coffee cups, protective coolers, and appliance cushioning blocks, EPS is notoriously difficult to manage within municipal recovery streams. Because the material is composed primarily of air, it is financially inefficient to transport and prone to fragmentation. These fragments frequently contaminate higher-value recyclable commodities at material recovery facilities (MRFs). Furthermore, toxicological research indicates that human exposure to styrene—a foundational building block of polystyrene—is correlated with elevated risks for leukemia, lymphoma, and other chronic health conditions. Consequently, California prohibited the sale, distribution, and import of EPS food service ware, prompting a rapid industry-wide pivot toward molded fiber containers, corrugated cardboard, and paper-based alternatives.
Black and Dark-Colored Plastic Packaging
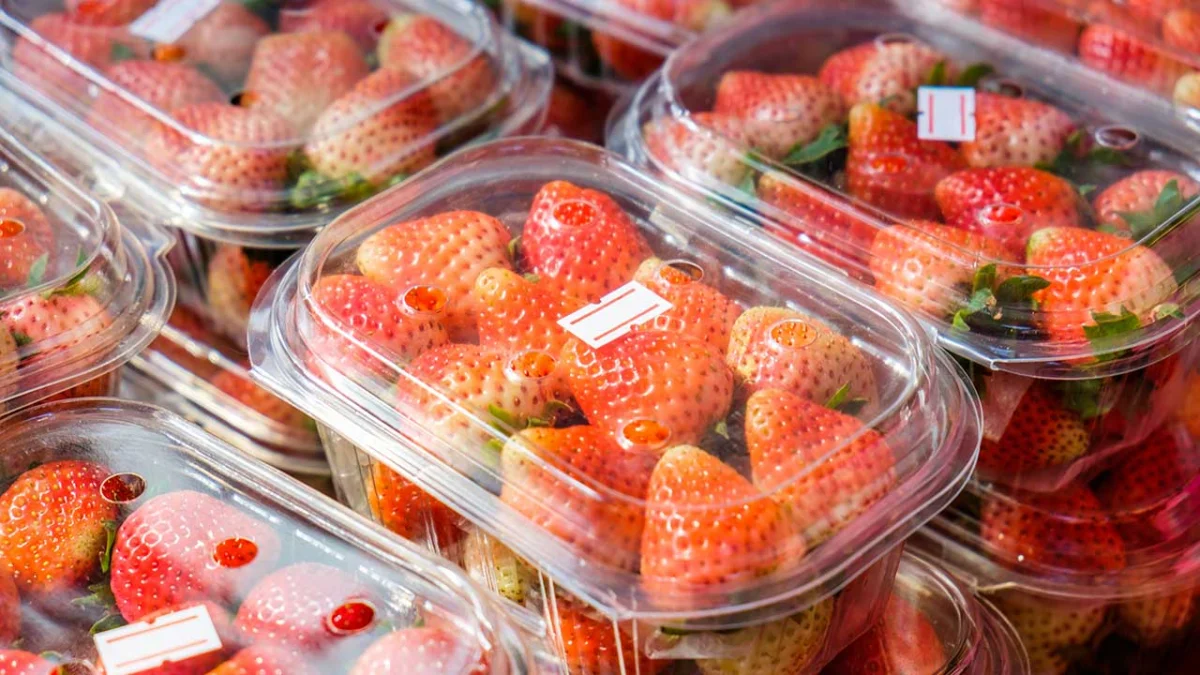
Dark-colored and black plastic trays, frequently utilized for microwaveable ready meals, sushi packaging, and fresh produce, present a unique technological barrier for modern recycling infrastructure. Most contemporary recycling facilities utilize near-infrared (NIR) optical sorters to rapidly identify and segregate different polymer types. However, the carbon black pigments traditionally used to dye these containers absorb near-infrared light rather than reflecting it back to the optical sensors. As a result, sorting machinery fails to categorize the material, automatically routing the containers away from recycling streams and into landfills. To comply with evolving mandates, manufacturers are transitioning toward clear or light-colored polyethylene terephthalate (PET) containers, which are easily detected by optical sorters and represent some of the most economically valuable materials in the recycling chain.
Polyvinyl Chloride (PVC) Clamshells and Blister Packs
Polyvinyl chloride, or vinyl, is a rigid plastic frequently molded into clear clamshell containers for bakery goods, berries, and salads, as well as protective blister packaging for retail electronics and toys. PVC acts as a severe chemical contaminant within the PET recycling stream; even microscopic quantities of PVC mixed into a bale of recyclable PET can ruin the entire batch, rendering it completely unprocessable. Additionally, chemical additives utilized to increase flexibility in PVC products include phthalates, which have been linked in clinical research to endocrine disruption and chronic metabolic conditions. In response, brand owners are rapidly adopting recycled PET (rPET) and molded pulp packaging alternatives.
Oxo-Degradable Plastics
So-called "oxo-degradable" plastics consist of conventional polyethylene embedded with chemical additives designed to accelerate physical fragmentation when exposed to sunlight or heat. Often marketed vaguely as eco-friendly or degradable, these materials do not genuinely biodegrade at a molecular level. Instead, they disintegrate into persistent microplastics that infiltrate terrestrial and aquatic ecosystems. SB 54 directly targets these misleading marketing practices, ensuring that any material claiming degradability must meet verifiable scientific standards rather than simply breaking down into invisible pollutants.
Chronology of Regulatory Implementation
The transition mandated by SB 54 is structured across a multi-year enforcement timeline, providing manufacturers a phased roadmap to overhaul complex global supply chains.
| Date | Statutory and Regulatory Requirement | Consumer-Facing Impact |
| :宁 | :— | :— |
| May 1, 2026 | Permanent regulations take effect upon filing. Producers register with the Circular Action Alliance, register as independent producers with CalRecycle, or claim small-producer exemptions. | Minimal immediate visual changes on retail shelves; corporate announcements regarding packaging redesigns begin. |
| January 1, 2027 | Full program implementation commences. Single-use plastic packaging must be reduced by 10% relative to the 2023 baseline. Non-compliant producers are barred from selling covered materials in California. | Introduction of thinner, lightweight packaging; reduction in secondary packaging materials such as promotional sleeves and window films. |
| January 1, 2028 | A statutory mandate requires that 30% of covered single-use plastic packaging and food service ware be effectively recycled rather than merely recyclable. | Accelerated proliferation of optical-sorter-friendly materials, including clear PET, molded fiber, aluminum, and corrugated cardboard. |
| January 1, 2030 | The mandatory recycling rate threshold increases to 40%, alongside a cumulative 20% source-reduction requirement. | Refill stations, concentrated product pods, and standardized returnable container systems scale from pilot projects to mainstream retail offerings. |
| January 1, 2032 | Full statutory targets take effect: 25% source reduction, a 65% recycling and composting rate, and 100% of covered packaging classified as recyclable or compostable. | Comprehensive transformation of supermarket aisles nationwide, accompanied by regulatory evaluations for potential future standards. |
Interstate Implications and National Market Harmonization
While California is the primary jurisdiction enforcing SB 54, the law functions as a de facto national standard. For major consumer packaged goods corporations that distribute merchandise across all fifty states, maintaining disparate packaging designs and navigating unique administrative fee structures for individual states represents an untenable logistical and financial burden.
To achieve economies of scale, manufacturers increasingly design a single, uniform packaging format that complies with the most stringent state-level regulations in the country—primarily those established by California and supported by parallel legislation in states such as Oregon, Colorado, Maine, and New York. This emerging regulatory alignment across the Pacific Northwest and the East Coast is effectively forging a national baseline, compelling companies to abandon non-compliant packaging across their entire American distribution networks regardless of local state laws.
Conclusion and Economic Outlook
As the implementation of SB 54 reshapes the American consumer goods sector, the long-term success of the initiative will depend on coordinated investments in physical infrastructure. The millions of dollars generated annually through Extended Producer Responsibility fees are earmarked specifically for upgrading municipal material recovery facilities with advanced robotics and optical sorting technologies, as well as expanding commercial composting networks.
By shifting the financial responsibility of waste management onto the corporations that profit from single-use materials, California’s landmark legislation represents a fundamental realignment of industrial design. For consumers, the ongoing transition signals the end of the linear "take-make-waste" economic model, steering the retail marketplace steadily toward a functional circular economy where waste is anticipated, minimized, and engineered out of existence from the design room floor.