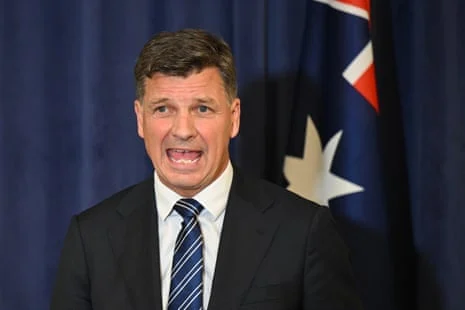
Assistant Treasurer Daniel Mulino has candidly acknowledged that the Australian Taxation Office (ATO) could have handled the abrupt credit card surcharge ban more effectively, admitting that while the agency faced an exceptionally intricate administrative challenge, hindsight reveals significant room for operational improvement.
The controversy stems from sweeping regulatory changes introduced by the Reserve Bank of Australia (RBA), which effectively banned payment surcharges and forced government agencies and commercial enterprises alike to re-evaluate how credit card transactions are processed and funded. With the ATO briefly suspending credit card payments at the start of October, taxpayers, commercial entities, and lawmakers were left scrambling to understand the sudden policy shift. Following intense political scrutiny and urgent negotiations, the federal government and tax commissioners have agreed to an extended transition period, allowing the ATO to continue accepting credit card payments until the end of June next year.
The Origins of the Tax Office Credit Card Crunch
The administrative friction first materialized earlier in the year, culminating in a sharp policy confrontation when Tax Commissioner Rob Heferen received formal notification regarding the RBA’s sweeping regulatory reforms. Speaking during a late-night Senate estimates hearing, Heferen revealed that the complications surrounding merchant fees and banking surcharges crystallised as a significant operational hurdle as early as April.

Under the previous financial framework, the ATO absorbed or passed on banking and credit card transaction fees associated with tax settlements. However, the RBA’s crackdown on surcharges fundamentally altered the cost-benefit landscape for public sector agencies. Heferen previously warned parliamentary committees that absorbing these banking fees entirely could cost the federal revenue collector roughly $200 million annually—an unsustainable financial burden that forced the agency to consider halting credit card payments altogether.
By June and July, internal working groups within the tax office were actively formulating contingency proposals, recognizing that any sudden cessation of credit card processing would directly penalize everyday taxpayers who rely on plastic for liquidity and cash-flow management. Despite these early internal deliberations, the transition strategy faltered, leading to a abrupt October cutoff that caught businesses and individuals off guard.
Political Fallout and Government Accountability
Appearing on ABC’s Radio National, Assistant Treasurer Daniel Mulino defended the tax commissioner’s overarching commitment to navigating the complex reforms, noting that the ATO was forced to simultaneously negotiate complex commercial contracts with major credit card companies while establishing a workable compliance timeline.
"The tax office was dealing with a genuinely complex problem," Mulino told listeners, before conceding that "with the benefit of hindsight, it could have done better."

The admission comes as the federal government faces broader economic pressures, with opposition figures seizing upon administrative missteps to criticize overall government management. Shadow figures and economic commentators have highlighted the incident as symptomatic of wider coordination failures between regulatory bodies and executive government agencies during a period of sustained cost-of-living anxiety.
By extending the grace period through to June of the following year, the government has bought itself a crucial window to finalize permanent commercial arrangements with financial institutions. This ensures that taxpayers will not face unexpected payment blockages while attempting to meet their statutory obligations ahead of the end-of-financial-year deadlines.
Broader Economic Pressures and Political Crosswinds
The controversy surrounding the ATO’s payment processing policies unfolds against a turbulent backdrop of broader Australian political and economic debates. During the same parliamentary and media cycle, Prime Minister Anthony Albanese and key economic ministers defended the government’s fiscal trajectory in the face of persistent inflation and global economic headwinds.
Speaking on wider fiscal policy, opposition voices, including Liberal MP Andrew Hastie, warned the public against the compounding pressures of inflation, describing rising prices as a "silent tax" that steadily erodes household wealth. The Coalition has continuously argued that aggressive government spending is exacerbating domestic inflationary trends, calling instead for stringent fiscal restraint and reduced public expenditure.

Concurrently, the federal government has found itself defending its international trade agenda, particularly the stalled Australia-European Union free trade agreement. Prime Minister Albanese launched a scathing critique of the Coalition’s hesitation regarding the trade pact, warning that opposing the deal would completely undermine the opposition’s professed credentials as champions of free and fair markets. Albanese characterized resistance to the agreement as an entry into "nativist politics" that runs counter to Australia’s identity as an outward-looking trading island nation.
Implications for Taxpayers and Public Administration
The episode involving the ATO’s credit card surcharge response offers a stark case study in the unintended consequences of regulatory convergence between independent monetary authorities and government collection agencies. When the RBA implements broad financial system reforms aimed at protecting everyday consumers from excessive merchant surcharges, public sector agencies operating under strict budgetary constraints inevitably feel the shockwaves.
For individual taxpayers and small-to-medium enterprises, the temporary suspension and subsequent extension of credit card facilities highlight the fragile dependency on digital payment infrastructure for tax compliance. Many businesses utilize credit facilities to manage seasonal cash flow variations when paying quarterly Business Activity Statements (BAS) or annual income tax liabilities. A permanent cessation of credit card payments without adequate alternative liquidity options could have triggered widespread liquidity crunches across the small business sector.
As the June 2026 deadline approaches, the onus remains on the ATO and financial institutions to forge a sustainable, cost-effective framework that bridges the gap between RBA mandates and public sector revenue collection. While the government has successfully defused the immediate crisis through a pragmatic extension, the episode serves as a cautionary tale regarding the necessity of seamless inter-agency communication and phased regulatory rollouts in modern public administration.