The national housing market experienced a brief yet significant respite last week as a marginal decline in mortgage rates successfully halted a prolonged bleeding of housing demand. After climbing to a formidable peak of approximately 7.60%, benchmark mortgage rates retreated toward the 7.30% threshold. This downward adjustment provided a temporary cushion during one of the most volatile weeks observed within the bond market for the 2026 fiscal year. As industry analysts and prospective homebuyers navigate the final week of October, a comprehensive review of macroeconomic indicators—including the 10-year Treasury yield, fluctuating mortgage spreads, and weekly pending sales—offers crucial insight into the trajectory of the housing sector for the remainder of the year.
The broader macroeconomic environment heading into the fourth quarter has been heavily dictated by shifting capital flows, geopolitical tensions affecting commodity prices, and persistent inflation signals. Industry observers and housing economists emphasize that the stability of the housing market remains inextricably linked to broader fixed-income dynamics. Understanding how these financial mechanisms interact is essential for interpreting the health of both the primary and secondary real estate markets as the year draws to a close.
Bond Market Turbulence and the 10-Year Yield Dynamics
The fixed-income market has endured a tumultuous month, characterized by rapid shifts in investor sentiment and macroeconomic crosscurrents. According to leading housing market forecasts for 2026, analysts closely monitor the 10-year Treasury yield as the primary barometer for long-term borrowing costs. Throughout October, market stability has hinged heavily on the 10-year yield maintaining a critical technical support level at 5.35%.
Despite persistent pressures from elevated global oil prices and stronger-than-anticipated domestic economic data, the 10-year yield managed to break back below the critical 5% threshold last week. This retreat was further aided by a slight cooling in investor enthusiasm surrounding artificial intelligence (AI) sector valuations, which redirected capital into safer fixed-income assets. Consequently, mortgage rates pulled back slightly from their recent multi-year highs.
Financial analysts note that the worst-case scenario—projections warning of mortgage rates surging toward 8% or even 9%—remains effectively neutralized for the time being. As long as the 10-year yield successfully holds the 5.35% floor and broader geopolitical conflicts stabilize to allow global energy prices to recede, the housing sector is positioned to avoid a catastrophic liquidity freeze.
Evolution of Mortgage Spreads and Historical Context
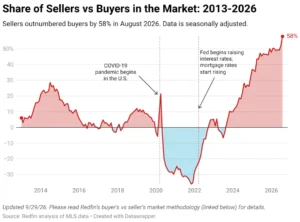
While baseline borrowing costs have retreated slightly, the behavior of mortgage spreads continues to draw scrutiny from financial institutions and consumer advocates alike. Mortgage spreads—the gap between the 10-year Treasury yield and the average 30-year fixed mortgage rate—have widened compared to the cycle lows observed earlier in the year. However, they remain relatively contained compared to the wider spreads seen immediately following the Federal Reserve’s aggressive monetary tightening cycle initiated in 2022.
Market experts emphasize that maintaining a mortgage spread closer to 2% rather than 3% is vital for keeping homeownership within reach for median-income families. Historically, healthy mortgage spreads have ranged between 1.60% and 1.80%. Last week, however, these spreads widened modestly to 2.23%, up slightly from 2.21% the preceding week.
Financial engineers explain that when the 10-year Treasury yield experiences sharp downward movements, mortgage spreads naturally tend to widen. Because mortgage-backed securities are structured to absorb prepayment risk and limit market volatility, lenders adjust spreads upward to hedge against rapid portfolio shifts. Comparing last week’s mortgage rates to historical averages over the past three years highlights the extent to which current monetary policy continues to exert upward pressure on consumer financing costs, even during periods of declining benchmark yields.
Weekly Pending Sales and Buyer Behavior
Real-time housing market metrics, such as weekly pending home sales data, provide an immediate window into consumer behavior and contract activity. Although these weekly metrics can occasionally be skewed by seasonal holidays, adverse weather events, or short-term market noise, they typically manifest in official closed-sales data within 30 to 60 days.
Last week’s data indicated a welcome cessation of the downward trend that had characterized the late-summer and early-autumn periods. As mortgage rates drifted downward, the persistent contraction in weekly pending sales finally leveled off, registering a modest positive print. Nevertheless, market analysts urge caution against overinterpreting a single week of positive momentum. Because the preceding weekly data had been softening at an accelerated pace, it required only a minor easing of borrowing costs to halt the immediate decline.
Historical data compiled over the past three years and ten months confirms a distinct consumer threshold: housing demand reliably expands when mortgage rates dip below 6.64%, mirroring the robust activity observed during the first half of 2026. Conversely, whenever average rates eclipse the 7% threshold, housing data consistently points toward a cooling market.
Purchase Applications and Long-Term Demand Indicators
Purchase application data serves as a reliable leading indicator for completed home sales over the subsequent 30 to 90 days. Recent metrics demonstrate clear evidence of demand destruction resulting from mortgage rates sustaining levels above the 6.64% threshold and pushing past 7%.
Because weekly application indices operate with a slight reporting lag, the latest figures do not yet fully capture the temporary rate relief observed in the final days of the reporting period. Consequently, economists will closely scrutinize upcoming purchase application releases to determine whether the recent dip in yields is sufficient to generate sustained week-over-week growth. To date, annual comparisons underscore the friction introduced by elevated borrowing costs, with purchase applications remaining depressed on both a week-over-week and year-over-year basis throughout much of 2026.
Housing Inventory and New Listings Trends
The dynamics of housing inventory growth throughout 2026 have diverged significantly from the rapid accumulation patterns witnessed in prior years. Inventory expansion has remained relatively subdued, with select weeks recording year-over-year declines. However, economic fundamentals dictate that when mortgage rates rise—particularly above the psychological 7% barrier—inventory tends to accumulate as homes linger on the market longer due to softened buyer demand.
Total inventory growth is currently running at a modest 5.68%. While this appears to indicate rising supply, analysts note that current year-over-year comparisons are artificially flattered by easier baselines, given that mortgage rates were roughly one percentage point lower during the corresponding period in 2025, when buyer demand was surging toward a nine-month high.
Concurrently, new listings have followed their typical seasonal contraction curve. On an annual basis, 2026 has nonetheless established itself as the healthiest year for new listings since 2022, with weekly volumes occasionally surpassing the 80,000 mark during peak periods. Real estate economists maintain a watchful eye on potential seller hesitation; because the vast majority of home sellers are simultaneously prospective homebuyers, persistently high mortgage rates can induce a "lock-in effect," discouraging current homeowners from listing their properties. For historical context, normalized housing markets during peak seasons typically yield between 80,000 and 100,000 new listings weekly, a stark contrast to the housing bubble era when weekly listings consistently ranged between 250,000 and 400,000 over several years.
Price-Cut Dynamics and Valuation Forecasts
Under normal market conditions, approximately one-third of residential properties experience at least one price reduction before securing a finalized purchase contract. Throughout most of 2026, the aggregate percentage of homes undergoing price cuts remained lower than the levels recorded during the previous year.
This trend shifted noticeably once average mortgage rates climbed above 6.64% and subsequently surpassed 7%. As buyer purchasing power diminished and market velocity slowed, the national price-cut percentage rose by approximately 1% year-over-year. Despite these short-term headwinds, overarching home-price appreciation has remained remarkably resilient. Initial annual forecasts projected a modest national home price decline of -0.62%. However, prevailing data indicates that achieving this forecasted contraction may prove difficult, as most recognized home-price indices continue to reflect annual price growth ranging between 1% and 2%, supported by steady wage growth outpacing property price increases.
Broader Economic Outlook: Oil, Geopolitics, AI, and Federal Reserve Policy
As the housing sector navigates the closing weeks of October, broader macroeconomic and geopolitical variables remain at the forefront of market risk assessments. Energy markets continue to pose a latent threat to interest rate stability, with crude oil prices hovering near yearly highs. Market strategists are monitoring potential geopolitical maneuvers in the Middle East and international trade adjustments that could intentionally exert upward pressure on energy commodities, thereby complicating inflationary outlooks.
Simultaneously, financial analysts are closely tracking developments within the technology sector, specifically observing high-yield credit spreads to gauge the ongoing funding environment for capital-intensive artificial intelligence infrastructure projects. Any sudden widening of credit spreads could ripple through the broader financial markets, influencing long-term Treasury yields.
Against this complex macroeconomic backdrop, attention turns squarely to the upcoming Federal Reserve policy meeting. While monetary authorities weigh employment data and core inflation metrics, the primary objective for the fixed-income market remains clear: preventing the benchmark 10-year Treasury yield from establishing a sustained close above the critical 5.35% resistance level. Successfully containing long-term yields within manageable parameters will ensure that the recent stabilization in housing demand translates into a durable footing as the market prepares to transition into the new year.