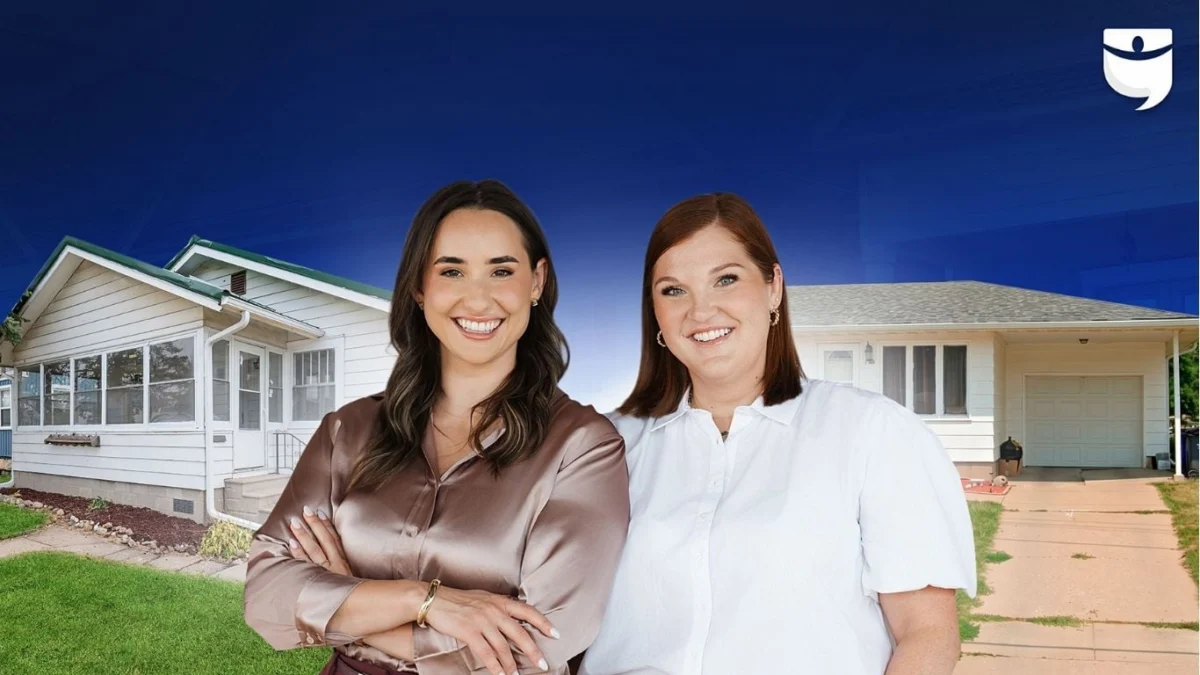
The real estate investment landscape in 2026 continues to shift as investors navigate higher interest rates, fluctuating property values, and the necessity of strategic portfolio management. While social media often highlights rapid wealth accumulation and idealized profit margins, a more granular examination of rental performance reveals a complex reality defined by maintenance costs, tenant retention, and the nuances of financing. Recent insights provided by experienced investors Amelia McGee and Grace Gudenkoff shed light on the mechanics of four distinct rental properties, moving past "phantom" projections to reveal the taxable, actualized income inherent in today’s market.
The Shift Toward Real-World Financial Transparency
The discrepancy between theoretical cash flow and actual net income is a frequent point of friction for novice investors. Theoretical or "phantom" cash flow—calculated as gross rent minus debt service—frequently fails to account for the realities of property ownership, including unexpected repairs, vacancy periods, and administrative expenses. For many, the transition from entry-level investing to a full-time professional portfolio requires a fundamental shift in how one evaluates an asset.
Amelia McGee, an investor based in Des Moines, Iowa, with a portfolio of 41 doors, and Grace Gudenkoff, who manages 25 units in Eastern Iowa, recently detailed the financial breakdown of their respective investments. Their data highlights that successful investing in the current economic climate is rarely about high-margin individual wins, but rather about the long-term compounding effects of debt pay-down, appreciation, and disciplined portfolio management.
Case Study: Duplex Performance and Equity Building
Grace Gudenkoff’s first featured deal, a side-by-side duplex purchased in 2021 for $135,000, serves as a primary example of how local banking relationships can influence initial acquisition costs. By negotiating a 10% down payment with a local community bank—a strategy rarely available through rigid conventional lending—Gudenkoff was able to enter the market while preserving capital.
The property’s performance underscores the volatility of net income. While the property generates approximately $2,150 in monthly rent, the actual annual net income, after accounting for $4,100 in turnover repairs and other operating expenses, resulted in a modest $5,304 of annual cash flow, or roughly $442 per month. This figure is significantly lower than the projected "phantom" cash flow of $770 per month. However, Gudenkoff notes that the true value of the asset lies in its five-year appreciation; the property, part of a $255,000 package deal for four units, has seen its value increase to an appraised $400,000, demonstrating that short-term cash flow is only one metric in a broader wealth-building strategy.
The Role of Niche Acquisition Strategies
Amelia McGee’s approach to acquisition—specifically "driving for dollars" and utilizing traditional methods like the local phone book to identify off-market leads—remains a cornerstone of the professional investor’s toolkit. Her experience with a triplex in a town of 5,000 residents illustrates the viability of small-market multifamily units. By securing the property through seller financing at 0% interest, McGee bypassed the high cost of debt service, allowing for a more aggressive reinvestment strategy.
The triplex features a unique mix of two long-term rentals and one short-term rental unit. Despite the logistical challenges of managing an Airbnb-style unit in a small town, the property nets roughly $580 in monthly cash flow. This, combined with the ability to refinance and extract equity, demonstrates how investors move beyond simple monthly profit-and-loss statements to view properties as capital-generating tools.
Portfolio Management and the "Negative" Cash Flow Paradox
Perhaps the most counterintuitive finding from the discussion involves a single-family home that currently operates at a negative cash flow of $105 per month. While many investors would classify this as a failing asset, McGee presents it as a calculated element of a larger portfolio strategy.
By refinancing the property, which had appreciated from a $55,000 purchase price to a $110,000 appraisal, McGee extracted $40,000 in tax-free capital. This liquidity was subsequently used to acquire an 11-unit apartment building. In this context, the $105 monthly loss on the single-family home is effectively subsidized by the higher-performing 11-unit building. This approach to "portfolio management"—where individual assets are judged not in isolation, but by their contribution to the total enterprise—is a hallmark of institutional-level real estate investing.
The Importance of Tenant Stability
Across all case studies, a recurring theme is the outsized impact of tenant relations on profitability. Turnover costs—often involving cleaning, repairs, and marketing—can quickly erode a year’s worth of cash flow. Both investors emphasize that maintaining a good tenant is often more profitable than raising rents to market levels if the increase risks a vacancy.
In the case of McGee’s single-family home, the inherited tenants have remained in the property for five years with minimal maintenance requests. The decision to keep rent at $825, despite the slight monthly loss after a refinance, is a deliberate trade-off for the stability and lack of turnover costs. This "brutally honest" approach to landlord-tenant relations, where transparency regarding expenses and market conditions is prioritized, has proven to be an effective strategy for minimizing friction and maximizing long-term retention.
Implications for Future Investors
The data provided by McGee and Gudenkoff suggest that the path to a full-time income from real estate is longer and more capital-intensive than is often portrayed. Key takeaways for the broader market include:
- Banking Relationships Matter: Local community banks remain a critical resource for investors seeking flexible terms, such as lower down payments and negotiable interest rates, which are not available through national lenders.
- Cash Flow vs. Total Return: While monthly cash flow provides liquidity, it is often the least reliable metric in the short term. Investors must focus on the total return, which includes debt pay-down, tax benefits, and capital appreciation.
- Portfolio-Level Thinking: Once an investor moves past the first few properties, the focus must shift to the aggregate performance of the portfolio. Moving equity from low-performing or stagnant assets into higher-yield projects is a necessary evolution for scaling.
- The "Boring" Reality: The most stable assets are often the least "interesting." Standard single-family homes or small multifamily units that require little intervention provide the most predictable outcomes, even if they lack the excitement of high-leverage commercial deals.
Conclusion
As the real estate market continues to evolve, the distinction between hobbyist investors and those managing a professional portfolio becomes increasingly apparent. The experiences of McGee and Gudenkoff reinforce the notion that real estate success is not a result of passive, hands-off income, but rather the result of active, informed management. By prioritizing transparent financials, leveraging local relationships, and viewing properties as part of a larger, interconnected portfolio, investors can better weather market fluctuations and build sustainable, long-term wealth. The reality of 2026 is that real estate remains a viable, albeit demanding, path to financial independence for those willing to embrace the complexity of the numbers behind the doors.