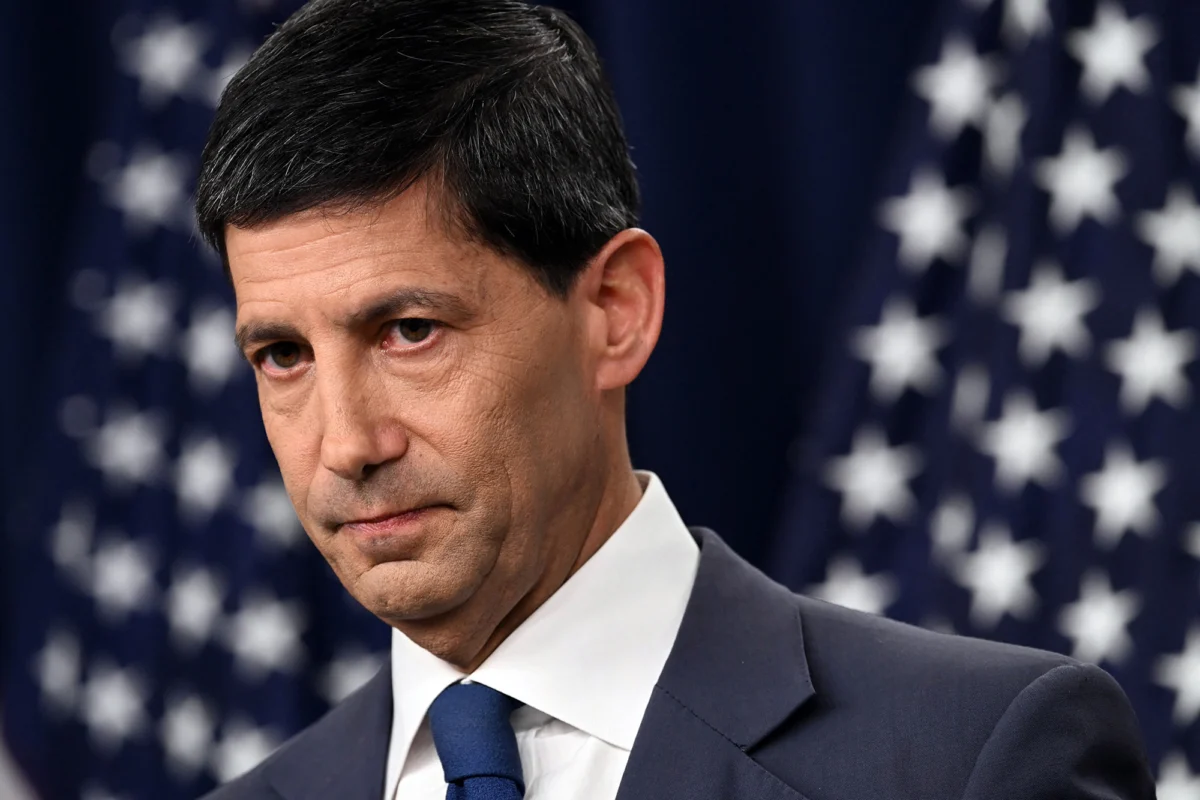
William McChesney Martin, the ninth chairman of the Federal Reserve, famously defined the central bank’s primary objective as the necessity to "take away the punch bowl just as the party is getting started." This philosophy—a metaphor for preemptive monetary tightening to curb inflationary pressures before they become entrenched—remains the guiding principle for modern Fed leadership. For Kevin Warsh, who assumed the chairmanship just four months ago, the mandate has proven to be a sobering baptism by fire.
Last week, the Federal Reserve’s board voted unanimously in a 12-0 decision to increase benchmark interest rates by 25 basis points, moving the target range to between 3.75 and 4 percent. This move signals a resolute, if painful, commitment to cooling an economy that has struggled with persistent price volatility throughout the summer. Warsh’s commentary following the vote was stark: "The plain fact is that inflation is too high, and has been for too long. This summer’s inflation readings do not tell me that underlying trends have meaningfully improved."
A Chronology of Monetary Tightening
The current climate of rising rates did not emerge in a vacuum. Since the post-pandemic recovery began, the Federal Reserve has been oscillating between stimulating growth and managing the resulting inflationary surge. The current 25-basis-point hike is part of a broader trajectory of tightening that began in earnest over the last 18 months.
Market participants have been closely watching the Fed’s communication strategy, particularly given the political friction that characterized the previous chairmanship. Observers are now looking to see if Warsh will face similar executive pressure from the White House, echoing the public discord that marked the relationship between President Trump and former Chair Jerome Powell. The consensus among analysts is that the Fed remains steadfast in its dual mandate of price stability and maximum employment, regardless of external political rhetoric.
The Impact on Commercial Real Estate
The commercial real estate (CRE) sector is uniquely sensitive to the cost of capital. For lenders and developers, the shift to a 4 percent benchmark rate is not merely a number; it is a fundamental restructuring of deal economics. Joseph Fingerman, president of CRE at Peapack Private Bank & Trust, notes that the industry is experiencing a widening chasm between participants. "This would likely widen the divide between well-capitalized sponsors capable of contributing fresh equity and overleveraged owners facing maturity challenges," Fingerman observed.
For institutions like Peapack Private, the strategy has shifted toward conservatism. Underwriting now requires higher stressed rates and more robust debt-service coverage cushions, effectively raising the barrier to entry for new projects. This tightening of credit standards is designed to prevent the systemic defaults seen in previous market cycles.
However, not all industry leaders view the hike as a signal of impending stagnation. Jay Neveloff of HSF Kramer remains optimistic about the resilience of the market. "I see more and more land plays and potential assemblages that are being discussed and are being worked on," Neveloff said. "I think for the smart investor who is not looking to stay on the sidelines, the opportunity is still there, and I don’t think 25 basis points moves the needle."
Institutional Perspectives on Capital Availability
During Commercial Observer’s annual Institutional Investor & Private Equity Forum, held at 237 Park Avenue, Blackstone’s Katie Keenan provided a counter-narrative to the prevailing gloom. She argued that the fundamental demand-supply imbalance continues to buoy the market. "When you have growing demand and flat, or down, supply, it’s a meaningful impact on what you see from a cash flow and growth perspective," Keenan explained. She characterized the current debt capital markets as "as healthy as I’ve seen them in a long time," noting that capital remains readily available and appropriately priced for the current risk environment.
Despite this optimism, the reality of the "lender-controlled" environment is becoming harder to ignore. Ryan Koehler, managing director for originations at NewPoint Real Estate Capital, points out that the era of "kicking the can" down the road is nearing its end. "We’re seeing a lot more lender-controlled transactions where equity has been substantially impaired or in many cases is completely wiped out," Koehler stated. Lenders are increasingly willing to acknowledge losses on bad deals, choosing to redeploy capital into more viable opportunities rather than maintaining non-performing assets.
Industrial and Residential Resilience
While the macroeconomic picture is complex, certain asset classes continue to demonstrate significant momentum. The industrial sector, in particular, remains a primary beneficiary of structural shifts in logistics and e-commerce. Notable recent transactions include SkyREM’s $101.8 million refinancing of a 1.9-million-square-foot East Coast industrial portfolio and the $2.4 billion joint venture between Ares Management and the Canadian Public Sector Pension Investment Board, aimed at expanding logistics capabilities.
The residential sector also continues to draw significant investment. Airbnb’s recent $250 million commitment to an affordable and mixed-use housing construction fund underscores the belief that the long-term housing shortage in major metropolitan areas will continue to drive demand, regardless of temporary interest rate fluctuations. Meanwhile, the office sector is showing signs of bifurcation; while some legacy assets struggle, premier corridors are seeing robust leasing activity. Cohen Brothers Realty, for instance, recently secured seven leases at the Pacific Design Center’s Red Building, totaling 96,000 square feet, proving that quality assets in prime locations continue to attract tenants.
Legal and Hospitality Market Movements
Legal firms remain the primary engine for high-end office leasing in New York City. Greenberg Traurig recently expanded its footprint at SL Green Realty’s One Vanderbilt by an additional 33,477 square feet, while Proskauer Rose renewed and expanded its lease at 11 Times Square by 60,000 square feet, bringing its total occupancy to 478,000 square feet.
In the hospitality sector, the historic Hotel Bossert in Brooklyn Heights is undergoing a transition into a Ritz-Carlton-branded luxury condo and hotel development, reflecting the enduring appeal of high-end, branded residences. Furthermore, the gaming industry is showing significant confidence in the regional market, with Bally’s securing a $560 million debt package from WhiteHawk Capital Partners to advance its Bronx casino project.
Talent Migration and Regional Trends
The current market shift has also triggered a wave of executive movement. Notable industry shifts include Steven McKessey’s departure from the Cumming Group to lead design and construction at Rudin, and Michael Eglit’s move from Blackstone Real Estate Debt Strategies to head U.S. originations at Starwood Capital Group. These moves suggest that major firms are positioning themselves to capitalize on the market reset.
In Southern California, a region that has faced years of stagnation, new opportunities are emerging. Decron Properties, following a two-year hiatus from the Los Angeles market, has acquired a 163-unit property in the Miracle Mile district for $114 million. Similarly, Stockdale Capital Partners and Hamilton Lane have invested $157 million into the Shoppes at Chino Hill. These moves indicate that even in a high-rate environment, institutional investors are finding value in markets where pricing has corrected to more sustainable levels.
Broader Implications and Outlook
The Federal Reserve’s decision to continue raising rates is a clear signal that the central bank intends to prioritize the containment of inflation over the immediate comfort of the real estate markets. While the 25-basis-point increase may seem incremental, the cumulative effect of these hikes is forcing a transition in the CRE landscape. The era of cheap, easy debt is firmly in the rearview mirror, replaced by an environment that rewards capitalization, fiscal discipline, and strategic asset selection.
As the industry adjusts, the primary risk remains the potential for further distress among overleveraged borrowers. However, the presence of significant dry powder and the continued demand for high-quality industrial and residential space suggest that the sector is not entering a total collapse, but rather a necessary period of re-valuation. As the Fed continues to monitor inflation data for signs of cooling, investors will need to maintain a disciplined approach, focusing on cash flow, debt service coverage, and long-term asset viability. Whether this cycle leads to a "soft landing" or a more prolonged correction remains the central question for the coming months, but for now, the industry is bracing for a sustained period of elevated rates.