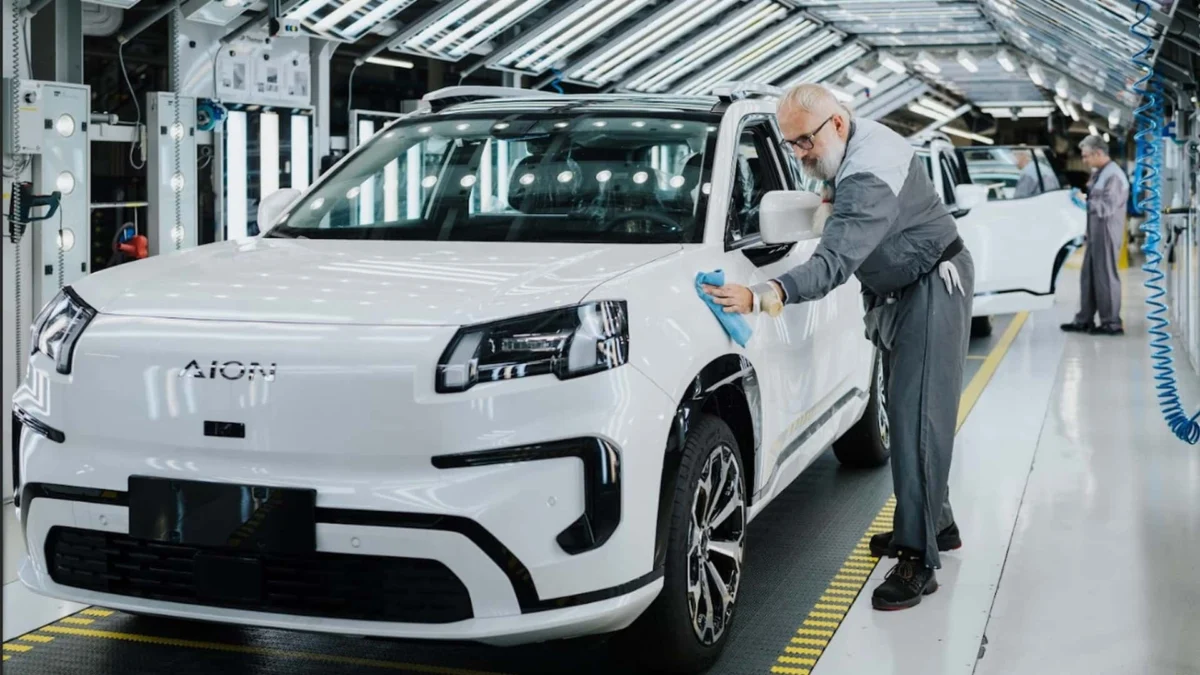
For Chinese automotive manufacturers, the prospect of entering the United States market has long been viewed as a high-stakes aspiration fraught with geopolitical tension. Throughout the late 2010s, as China’s domestic EV sector surged with state-backed investment and technological maturation, the industry looked toward North America as the ultimate frontier for global expansion. However, the trajectory shifted abruptly as the U.S. moved to protect its domestic manufacturing base through a combination of punitive tariffs, supply chain restrictions, and heightened national security scrutiny. What appeared to be a period of inevitable globalization has instead solidified into a landscape of economic protectionism, leaving Chinese brands largely sidelined from the world’s most lucrative automotive market.
The prevailing status quo, characterized by a bipartisan consensus on the risks posed by Chinese automotive integration, faced a potential disruption this past Friday. During an appearance on Fox News’ The Ingraham Angle, President-elect Donald Trump articulated a nuanced position that could signal a pivot in trade strategy. While maintaining a firm stance against the importation of vehicles produced in China, Trump expressed a conditional openness to Chinese automakers establishing production facilities on American soil.
“If China wanted to come in and open a plant to build their cars here, I’d be okay with that,” Trump stated during the interview. “Japan does it, but they hire our people. The big thing is they hire our people.” He was quick to distinguish this approach from the current strategies of some global firms that utilize manufacturing hubs in Mexico to gain duty-free access to the U.S. market under the United States-Mexico-Canada Agreement (USMCA). Trump emphasized his opposition to using regional neighbors as a loophole to circumvent trade rules, framing the issue squarely around the creation of domestic jobs and the expansion of the U.S. industrial footprint.
The Legislative and Regulatory Landscape
The prospect of Chinese-branded vehicles appearing on U.S. roads remains significantly complicated by a web of existing regulations. The Department of Commerce has already implemented a series of stringent rules that effectively serve as a barrier to entry. Starting in 2027, the U.S. will ban software developed by Chinese firms in connected vehicles, followed by a total ban on Chinese-developed hardware in 2030. These regulations are grounded in national security concerns, specifically the potential for foreign surveillance and the vulnerability of the domestic electric grid and infrastructure.
These measures are not merely theoretical; they have already begun to reshape the market. Polestar, a brand with deep roots in the Geely-Volvo ecosystem, recently saw its efforts to secure U.S. market authorization denied, effectively forcing an exit strategy. Similarly, major legacy manufacturers are finding themselves in the crosshairs of federal oversight. Last week, Department of Transportation Secretary Sean Duffy directed a sharp critique toward Ford Motor Company regarding its licensing agreement with Contemporary Amperex Technology Co. Limited (CATL), the Chinese battery giant.
Ford’s project in Michigan—a facility designed to produce LFP (Lithium Iron Phosphate) batteries—relies on American labor and localized production. However, the involvement of CATL’s proprietary technology has drawn significant fire from lawmakers. Michigan Senator Elissa Slotkin, who has been a vocal proponent of legislative action to prohibit Chinese-made vehicles, has cautioned that any potential deal involving a broader acceptance of Chinese automotive entities could undermine U.S. manufacturing security. These tensions are expected to reach a focal point when Chinese President Xi Jinping visits the United States for high-level meetings later this month.
A Chronology of Rising Tensions
The friction between the U.S. automotive industry and Chinese expansionism has been years in the making.
- 2018-2019: The U.S.-China trade war intensifies, with the implementation of Section 301 tariffs on a wide range of goods, including automotive components and finished vehicles.
- 2021-2022: The Biden Administration doubles down on domestic production through the Inflation Reduction Act (IRA), which ties federal tax credits for EVs to stringent domestic content requirements, effectively excluding vehicles produced outside of the North American free-trade zone.
- 2023: The U.S. government initiates investigations into "connected vehicles" sourced from China, citing data privacy and cybersecurity risks as primary concerns.
- 2024: During his presidential campaign, Donald Trump consistently floated the idea of "catastrophic" tariffs on vehicles produced in Mexico by Chinese companies, while simultaneously expressing a willingness to negotiate terms for direct investment in the U.S.
- 2025: Regulatory bans on Chinese software and hardware are finalized, setting a hard deadline for the removal of Chinese technology from the American automotive supply chain.
Economic Implications of Localized Production
The argument for allowing Chinese firms to manufacture in the U.S. mirrors the path taken by Japanese automakers in the 1980s. At that time, companies like Toyota, Honda, and Nissan faced intense pressure to move production stateside to mitigate trade deficits and satisfy labor unions. Today, the Japanese automotive footprint in the U.S. is massive, accounting for hundreds of thousands of jobs across the "auto alley" of the American South and Midwest.
Proponents of a similar model for Chinese manufacturers argue that it could accelerate the transition to electric vehicles in the U.S. by leveraging China’s current lead in battery efficiency and cost-effective manufacturing processes. By requiring these firms to source materials locally, hire American workers, and adhere to U.S. labor and environmental standards, the government could theoretically foster competition that lowers prices for the American consumer without sacrificing national security or domestic labor strength.
However, critics, including many within the current legislative framework, argue that the risks of intellectual property theft and the potential for "backdoor" access to critical infrastructure remain too high. Furthermore, there is the concern that even if a plant is located in the U.S., the ultimate ownership and the flow of profits would remain in Beijing, failing to provide the long-term economic security that domestic firms offer.
The Path Ahead: A Diplomatic Pivot?
The upcoming meeting between President-elect Trump and President Xi Jinping is widely viewed as a bellwether for the future of U.S.-China economic relations. While Trump has often used aggressive rhetoric regarding trade deficits and geopolitical alignment, he has also historically maintained a transactional view of his relationship with President Xi.
The political reality is that a total, indefinite ban on Chinese automotive presence is being challenged by the sheer pace of global innovation. As Chinese manufacturers continue to break export records—shipping millions of vehicles annually to Europe, Southeast Asia, and Latin America—the U.S. remains the only major market where they are largely absent.
If the incoming administration decides to facilitate a "Japan-style" entry for Chinese firms, it would require a complete overhaul of the current regulatory environment. This would involve not only lifting or modifying the software and hardware bans but also providing assurances to domestic manufacturers that their market share would not be cannibalized by state-subsidized competitors.
For the moment, the barriers remain firmly in place. The Department of Commerce’s rules are set to take full effect within the next few years, and legislative efforts to codify these bans are gaining bipartisan support. Yet, in the landscape of modern American politics, where campaign promises often shift into policy with little warning, the automotive industry is preparing for the possibility of a radical U-turn. Whether this leads to a new era of localized manufacturing or merely adds another layer of complexity to an already volatile trade relationship remains to be seen. As it stands, the automotive industry is in a holding pattern, awaiting a clear signal from the White House that will define the rules of engagement for the remainder of the decade.