Mobile homes have rapidly emerged as a vital pathway for first-time homebuyers attempting to navigate an increasingly prohibitive housing market. Driven by escalating traditional real estate prices and modern legislative shifts—such as provisions within the federal ROAD to Housing Act designed to streamline the placement, construction, and accessibility of manufactured housing—more buyers are looking to factory-built homes as a viable alternative to site-built properties. However, acquiring a mobile home involves a complex ecosystem of financial, legal, and logistical considerations that extend far beyond simply selecting a floor plan and a plot of land.
Understanding the nuances of mobile home ownership requires a comprehensive evaluation of upfront costs, hidden expenses, financing mechanisms, land arrangements, and long-term asset appreciation. While these properties frequently offer a lower barrier to entry for prospective homeowners and retirees looking to downsize, they also carry distinct maintenance responsibilities and financing structures that differentiate them sharply from traditional residential real estate.
Defining Manufactured and Mobile Housing: Standards and Terminology
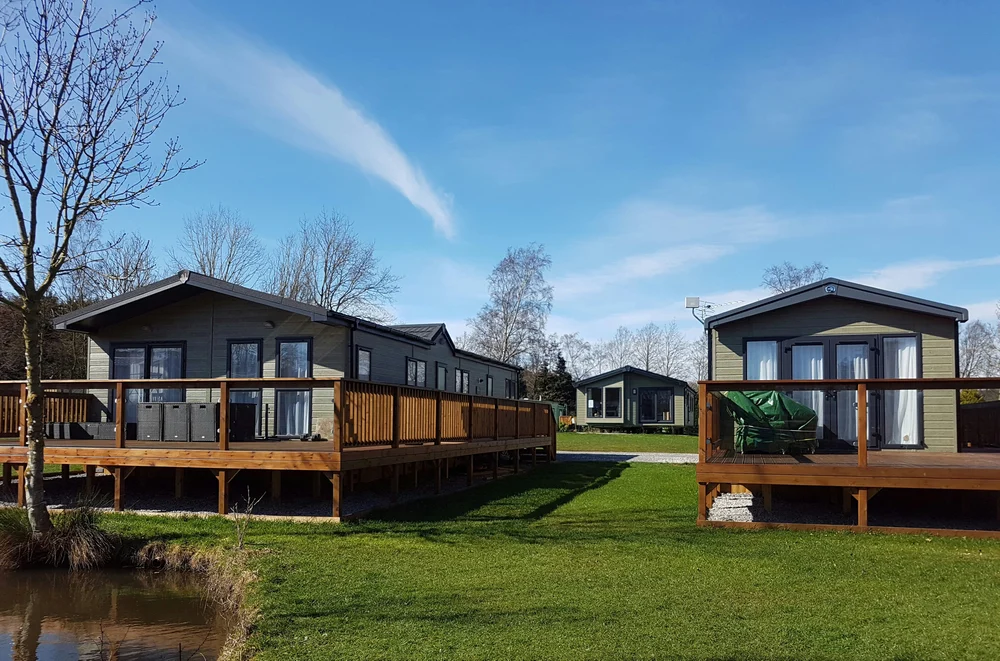
To make an informed purchasing decision, buyers must first understand the technical distinctions between various types of factory-built housing. Although the terms "mobile home" and "manufactured home" are often used interchangeably in everyday conversation, they carry specific regulatory definitions based primarily on construction standards and manufacturing dates.
Historically, homes built prior to June 15, 1976, are legally classified as mobile homes. These structures were built before the implementation of the National Manufactured Housing Construction and Safety Standards Act, a landmark piece of federal legislation overseen by the U.S. Department of Housing and Urban Development (HUD). Homes constructed after this date must strictly adhere to the federal HUD code, which regulates design, construction, strength, fire resistance, energy efficiency, and operational quality. Consequently, modern industry professionals and lenders exclusively use the term "manufactured homes" for post-1976 properties.
In contrast, modular homes are constructed in sections inside a factory environment but must comply with state and local site-built building codes rather than federal HUD standards. Once assembled on a permanent foundation, modular homes are legally indistinguishable from traditional stick-built houses and generally appreciate in value at comparable rates.
Manufactured homes are typically categorized into three primary structural configurations:
- Single-wide homes: Comprising a single rectangular section, these compact units generally range from $40,000 to $100,000, offering a streamlined layout ideal for individuals or small families.
- Double-wide homes: Built using two connected sections, these units provide significantly more living space, with illustrative prices typically spanning $95,000 to $150,000.
- Triple-wide homes: Consisting of three or more integrated sections, these expansive properties often exceed 2,000 square feet and command prices starting at $150,000 and above.
Financial Realities: Purchase Prices, Hidden Costs, and Monthly Budgets
While the initial sticker price of a manufactured home is substantially lower than that of a traditional site-built house, prospective buyers must budget carefully for a variety of ancillary expenses. The overall cost of a mobile home acquisition is dictated by its size, age, condition, geographical location, and whether the purchaser is simultaneously acquiring the underlying real estate or simply leasing a lot within a land-lease community.
Beyond the baseline purchase price, buyers frequently encounter a series of overlooked expenditures. Industry experts emphasize that closing costs, administrative permits, delivery fees, and site preparation represent only the beginning of the financial commitment.
"Buyers may overlook costs related to repairs, maintenance, tie-downs, inspections, skirting, leveling, and other work that may be required before or after closing," notes the operations team at Desert Mobile Home Services in Arizona. Tie-downs—specialized protective anchoring systems designed to secure manufactured homes against severe weather and shifting soils—are particularly critical. "Tie-downs may also be required by a lender, engineer, or as part of the financing process, so they should be addressed early rather than waiting until the last minute."
Monthly housing payments are similarly multi-faceted. In addition to principal and interest obligations on the loan, homeowners must factor in property taxes, hazard insurance, utility hookups, and, where applicable, monthly lot rent. Failing to account for these ongoing operational expenditures can quickly strain a household budget, making comprehensive financial pre-planning essential.
Navigating Location, Land Ownership, and Site Preparation
One of the most consequential decisions a mobile home buyer will make is determining where the home will be located. Buyers generally have two primary options: placing the home within an established land-lease manufactured home community or installing it on private land owned outright by the purchaser.
Purchasing a home within a mobile home park or community typically means the homeowner owns the physical structure while renting the underlying land. While this arrangement often provides access to shared community amenities, it exposes the resident to monthly lot rent increases, community regulations, and potential restrictions on property modifications. Furthermore, financial analysts point out that homes situated on leased land frequently lack the potential for long-term appreciation because the owner does not control the underlying real estate. Consequently, many housing economists advise purchasing manufactured housing only when the buyer also holds the title to the land beneath it.
Conversely, placing a mobile home on private land grants the owner greater autonomy over property decisions, landscaping, and long-term equity building. However, this route requires navigating complex municipal zoning laws, securing building permits, and managing costly site preparation tasks such as land grading, utility installation, septic system placement, and foundation construction.
Recent federal policy shifts have also influenced how these homes interact with land. Following the passage of legislative provisions in the ROAD to Housing Act, federal regulations have removed the traditional requirement for a permanent metal chassis on certain manufactured homes. While eliminating the chassis removes the physical ability to relocate the home in the future, it significantly reduces production and placement costs while expanding architectural floor plan possibilities. As a result, the vast majority of modern manufactured homes remain permanently affixed to their initial installation sites.
Financing Structures: Chattel Loans Versus Traditional Mortgages
Securing financing for a manufactured home differs significantly from obtaining a conventional residential mortgage. According to real estate and housing development specialists, financing terms must be established early in the purchasing timeline, as the loan type is dictated by whether the home is classified as personal property (chattel) or real estate (real property).
- Chattel Loans: Frequently utilized when the mobile home is purchased independently of the land or placed on leased community property, chattel loans function similarly to auto loans rather than mortgages. They feature shorter repayment terms and higher interest rates compared to traditional real estate loans.
- Government-Backed Loans: Qualified buyers may access favorable financing through Federal Housing Administration (FHA), Department of Veterans Affairs (VA), or U.S. Department of Agriculture (USDA) loan programs, provided both the borrower and the property meet specific federal guidelines.
- Conventional Real Estate Mortgages: When a manufactured home is permanently affixed to land owned by the borrower and classified as real property, it may qualify for conventional mortgage financing, mirroring the options available to buyers of traditional site-built homes.
- Personal Loans: In scenarios where specialized manufactured housing lenders are unavailable, unsecured personal loans offer an alternative, though they typically carry elevated interest rates and compressed repayment windows.
Industry Perspectives and Expert Advice on the Purchasing Process
Navigating the acquisition of a manufactured home requires meticulous due diligence, particularly when engaging with independent sellers, retail dealerships, or factory fabricators. Industry leaders emphasize the importance of professional oversight throughout the transaction.
"Decide how you’ll finance the home before you fall for a floor plan, because that choice shapes everything else," advises Cameron Joávan, founder of the on-demand homebuilding platform PERCH. "Manufactured homes are built to the federal HUD code and can be financed as personal property or real property, depending on the home and the land."
When purchasing a new home from a retail dealer, experts warn buyers to remain vigilant against ambiguous contract terms. Representatives from Henley Homes in Sulphur Springs, Texas, caution consumers to watch for unclear pricing structures, vague delivery responsibilities, and unverified warranty claims. "Research the retailer carefully, understand exactly what is included in the purchase price, clarify who is responsible for delivery, installation, site work, permits, utilities, and warranty service, and ensure that all costs and promises are clearly documented before signing the final purchase agreement."
Similarly, Ivan Kosobucki, founder of PrefabFind, recommends retaining independent professional assistance to review purchase contracts prior to execution. "One thing we often see buyers overlook is the contract: before signing, have an independent professional review it to ensure the terms are fair and clearly explain what happens if the manufacturer delays delivery, fails to meet its obligations, or goes bankrupt."
Once a property is selected—whether new or pre-owned—securing a professional home inspection is widely regarded as an indispensable step. Jesse Weaver of Northwest Home Inspector in Washington State underscores the value of expert evaluations. "Hiring a seasoned home inspector who specializes in mobile homes to go over all of the intimate details of the property with you is worth its weight in gold. Learn all you can and do not be shy to ask all of the questions you have—even the ones that may seem silly."
Evaluating the Broader Implications of Manufactured Housing
As the American real estate market continues to grapple with housing affordability constraints, manufactured and mobile homes are projected to play an increasingly prominent role in residential and retirement planning. Industry advocates note that modern factory-built communities offer an attractive, cost-effective alternative for individuals seeking to transition out of traditional rental markets or scale down their living arrangements without surrendering the independence of homeownership.
Ultimately, determining whether purchasing a mobile home is a worthwhile investment depends heavily on an individual’s financial preparedness, long-term housing strategy, and lifestyle preferences. By carefully calculating total ownership costs, securing appropriate financing, verifying land and community regulations, and conducting thorough physical inspections, prospective buyers can successfully leverage manufactured housing to achieve sustainable, affordable homeownership.