The Burden of Global Dominance
To understand why Beijing remains cautious, one must analyze the requirements of a global reserve currency. For a currency to truly replace the dollar, a nation must maintain open capital markets, provide deep liquidity for international investors, and act as a lender of last resort. For the Chinese government, these requirements are antithetical to its domestic political structure.
The Communist Party relies heavily on strict capital controls to maintain its grip on the economy, determining who receives credit and how capital flows throughout the nation. An open capital market would strip the state of this essential mechanism of control. Furthermore, many members of the Chinese elite rely on offshore dollar holdings as a form of "political insurance." If the yuan were to become the global reserve, the internal mechanisms of wealth protection currently favored by Chinese officials would be significantly disrupted. Consequently, Beijing views the dollar’s continued dominance not as a threat to be eradicated, but as a status quo to be navigated.
Strategic Defensive Objectives
The primary driver behind the internationalization of the renminbi is not an attempt to lead the global financial system, but a tactical maneuver to mitigate the risk of financial weaponization by the United States. Following the 2022 Russian invasion of Ukraine, the U.S. and its allies demonstrated the power of the dollar-based financial system by severing Russia’s access to the SWIFT banking network and freezing central bank assets.
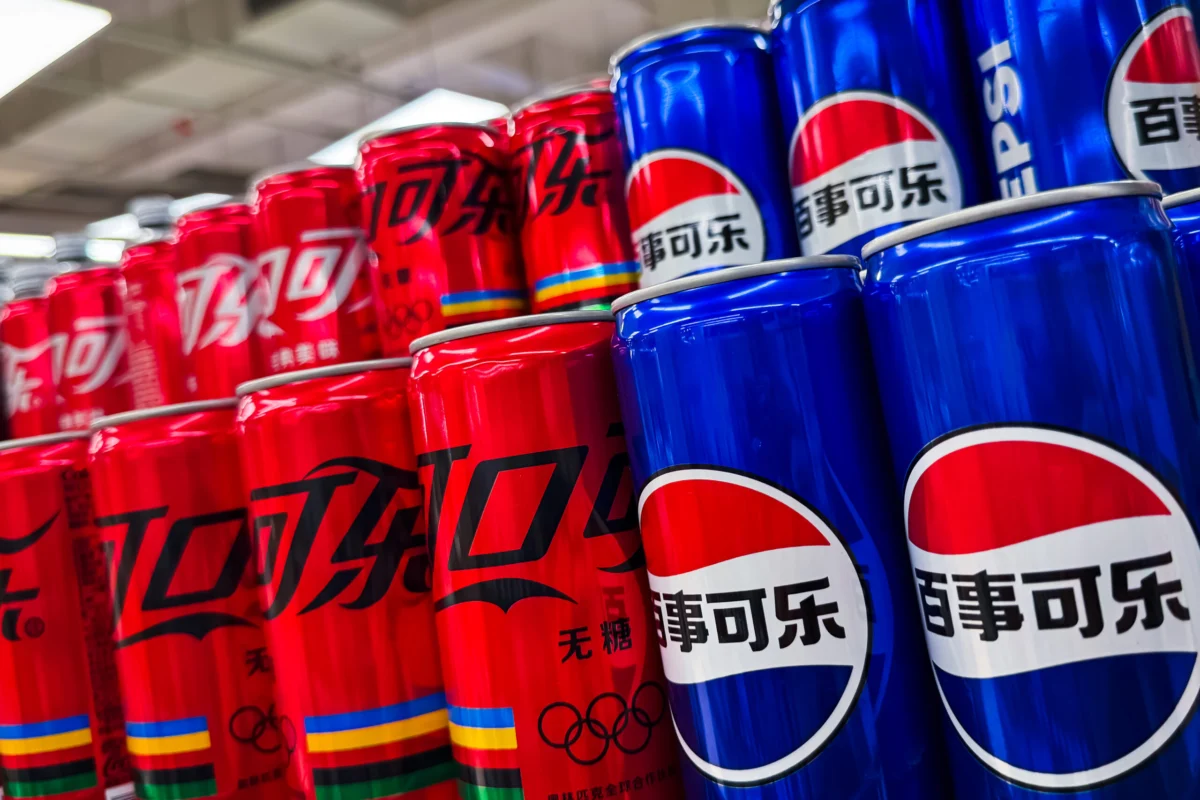
For Beijing, the lesson was clear: over-reliance on the dollar-dominated global payment infrastructure is a significant national security vulnerability. By fostering a network for the renminbi that is international enough to function independently of the U.S. system, China aims to insulate itself from potential future sanctions. The goal is to establish the yuan as a "respectable second" or a "consequential third" in the global hierarchy. This position allows China to bypass unilateral U.S. sanctions while avoiding the immense financial cost and geopolitical responsibility that comes with managing the world’s primary reserve asset. In essence, Beijing is positioning the renminbi to be the "Pepsi" to the dollar’s "Coca-Cola"—a secondary option that remains serviceable in a pinch and serves as a vital hedge against the dominant incumbent.
Chronology of Internationalization Efforts
The internationalization of the yuan has been a multi-decade project, gaining significant momentum in recent years:
- 2009: China begins the Cross-Border Trade RMB Settlement Pilot Program, allowing companies in select cities to settle trade in yuan.
- 2015: The IMF includes the yuan in the Special Drawing Rights (SDR) basket, a significant symbolic milestone for the currency’s legitimacy.
- 2015–2016: The Cross-Border Interbank Payment System (CIPS) is launched to facilitate international clearing, signaling a move away from sole reliance on Western clearinghouses.
- 2022–2023: Accelerated by the fallout from the Ukraine conflict, China signs a series of bilateral currency swap agreements with central banks across the Global South.
- 2024–2026: China begins aggressively promoting "China prices"—yuan-denominated benchmarks for commodities, most notably in the lithium and critical minerals sectors.
Supporting Data: Current Market Reach
As of mid-2026, the progress of the renminbi is quantifiable, though it remains a small fraction of the U.S.-led system. The Cross-Border Interbank Payment System now boasts 1,829 participants, enabling transactions with over 5,200 financial institutions in 191 countries. While this is a robust footprint, it pales in comparison to the reach of the dollar, which remains the primary vehicle for global pricing, financing, risk transfer, and long-term reinvestment.
The "reinvestment" aspect remains the weakest link in China’s strategy. For a currency to be a true reserve, foreign entities must be willing to hold and reinvest their balances in domestic assets. Currently, foreign investors hold only 1.6% of the Chinese bond market, compared to 27% in the U.S. bond market. Without a larger, more transparent, and liquid pool of renminbi-denominated assets, the yuan faces a structural barrier to becoming a true rival to the dollar.
The Rise of the "Green Yuan"
While China may not be pursuing traditional reserve status, it is actively building a "green yuan" ecosystem. By consolidating its dominance over the green energy supply chain—specifically in lithium, critical minerals, and electrical infrastructure—China is creating a sector where its currency is the natural choice for settlement.
If China succeeds in setting the global standards for green technology, it could leverage its control over these essential, hard-to-substitute inputs to force trade in yuan. This strategy essentially mimics the historical "petrodollar" arrangement, where the U.S. guaranteed its currency’s dominance by linking it to oil. China is attempting to replicate this with the "energy of the future."
Geopolitical Shifts and the Petroyuan
The ongoing instability in the Middle East has provided an unexpected catalyst for the potential emergence of a "petroyuan." The petrodollar system, established in 1974, relied on a security pact between the U.S. and Saudi Arabia, where Washington provided military protection in exchange for oil being priced in dollars.
However, recent developments—including the limited success of U.S. naval operations in the Strait of Hormuz and the vulnerability of Gulf infrastructure to modern drone and missile technology—have led to a reassessment of these historical alliances. As Deutsche Bank noted in a recent report, the perceived inability of U.S. air-defense systems to fully protect critical Gulf energy infrastructure has prompted regional powers to consider diversifying their financial dependencies. If regional actors begin accepting yuan for oil as a diplomatic or security hedge, it could signal the beginning of a genuine erosion in petrodollar dominance.
Implications for Global Finance
The shift toward a multipolar currency system carries profound implications for global trade and financial stability. A world where the dollar is no longer the sole arbiter of international trade will likely see increased fragmentation. While this may offer China and its partners protection from U.S. sanctions, it also introduces complexity into global financial markets, potentially increasing transaction costs and reducing transparency.
For the United States, the existence of the renminbi as a viable alternative limits the "exorbitant privilege" of the dollar. The ability to impose unilateral financial sanctions is a key component of modern American statecraft; if China successfully provides an alternative ecosystem, the potency of this tool will diminish.
Ultimately, Beijing’s strategy is not one of global conquest, but of strategic survival. By building the infrastructure for the renminbi to function as a "serviceable" alternative, China is effectively protecting its political and economic sovereignty. The "cola wars" of the global financial system may not result in a new market leader, but they are certainly ensuring that the dominant incumbent can no longer act without considering the existence of a viable, if smaller, competitor. As the international landscape continues to shift, the focus will remain on whether China can convince enough nations that the renminbi is not just a tool of convenience, but a stable enough asset to hold for the long term.