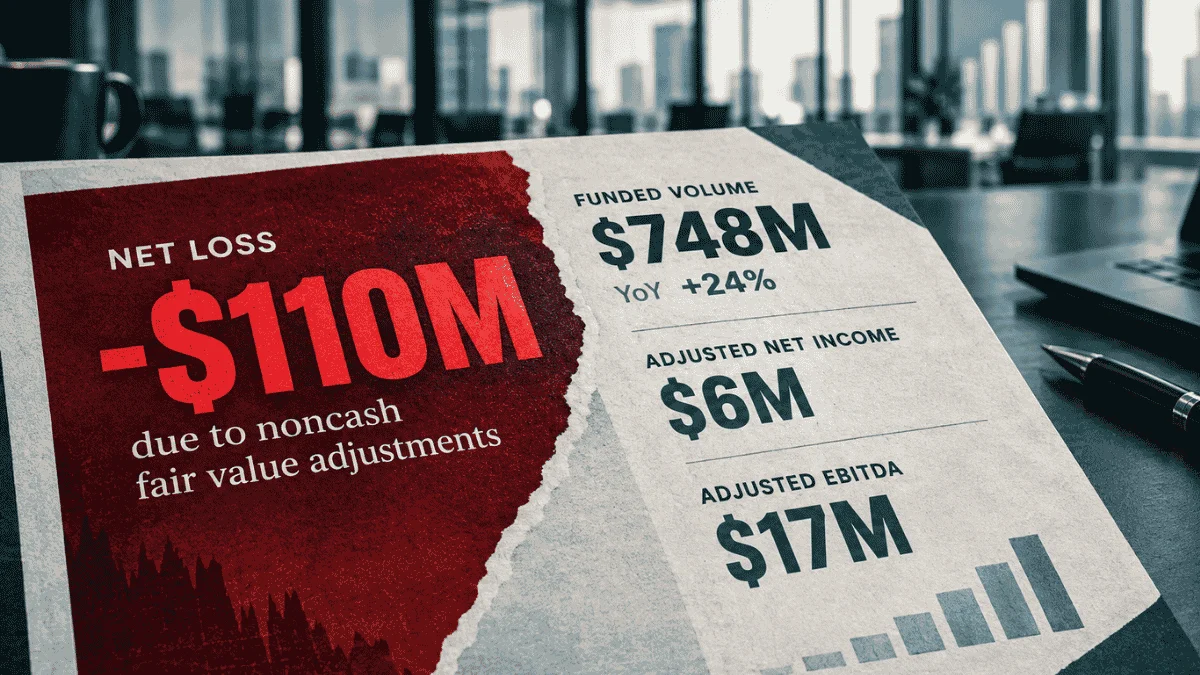
Finance of America (FOA), a prominent specialty finance and home equity lending platform based in Plano, Texas, reported a net loss of $110 million for the third quarter of 2026. Despite posting robust growth in its core home equity origination volume, the company’s bottom line was severely impacted by noncash fair value adjustments and a sudden, challenging shift in the macroeconomic landscape.
The latest financial disclosures reveal a complex quarter for the reverse mortgage and home equity giant. While customer demand for specialized retirement lending products continued on an upward trajectory, aggressive monetary policy shifts by the Federal Reserve and subsequent jumps in benchmark treasury yields introduced near-term headwinds that compressed profit margins across the sector.
Executive leadership at Finance of America has moved swiftly to reassure investors, emphasizing that the operational fundamentals of the platform remain strong and that corrective pricing adjustments have already been deployed to restore historical margin levels by early 2027.
Main Facts and Financial Performance Overview
For the quarter ending September 30, 2026, Finance of America recorded $748 million in funded origination volume. This figure represents a 24% year-over-year increase compared to the $603 million reported during the corresponding period in 2025. On a year-to-date basis, total funded volume reached $2.07 billion, marking a 17% expansion over the first nine months of the previous year.
However, headline profitability figures reflected substantial GAAP losses. FOA recorded a basic net loss of $5.24 per share for the third quarter, a steep decline from the loss of 98 cents per share registered in the third quarter of 2025. The primary driver behind the quarterly net loss was a $125 million charge stemming from noncash fair value adjustments, particularly concerning retained interests in securitization portfolios.
Adjusted metrics offered a more stable view of core operational performance, albeit one that still showed compression from the previous year. On an adjusted basis, Finance of America posted a net income of $6 million, or 28 cents per share, down from $33 million, or $1.33 per share, a year earlier. Adjusted EBITDA for the third quarter of 2026 totaled $17 million, representing a decrease from the $55 million reported in the third quarter of 2025.
Despite these financial pressures, the company’s liquidity position improved notably over the quarter. FOA concluded the third quarter with $118 million in cash and cash equivalents, up from $85 million at the close of June. This liquidity expansion was driven by robust cash generation from originations and strategic capital markets maneuvers. Total equity stood at $307 million as of September 30, with a book value of $28.08 per common share.
Macroeconomic Pressures and the Federal Reserve Pivot
The third quarter of 2026 introduced a notably hostile rate environment for mortgage lenders and specialty finance firms. Throughout the quarter, 10-year Treasury yields climbed by more than 75 basis points. Industry analysts noted that this surge was a direct reaction to persistent inflation readings and a pivotal policy shift by the Federal Reserve, which transitioned from an easing monetary policy stance toward rate hikes.
During the earnings call with investors and analysts, CEO Graham Fleming addressed the macroeconomic environment head-on. He explained that the shift in Federal Reserve policy rapidly compressed the revenue margins associated with originating home equity and reverse mortgage products.
“The third quarter of 2026 demonstrated the continued strength of our platform, with funded origination volume growing 24% year over year,” Fleming stated. “While higher interest rates drove near-term pressure on earnings, we believe this impact is temporary. We have already taken steps to improve margins.”
Fleming noted that the company has implemented necessary adjustments to product pricing across its entire suite of offerings. Management anticipates that these adjustments will take full effect, allowing margins to return to historical norms by the first half of 2027. He underscored that Finance of America has achieved an average annual volume growth of roughly 20% since 2023, pointing to structural demographic tailwinds that continue to drive demand regardless of short-term interest rate volatility.
Retirement Solutions Segment Performance
As the core engine of the company’s business model, the Retirement Solutions segment—which specializes in home equity-based financing products, most notably Home Equity Conversion Mortgages (HECMs) and proprietary HomeSafe products—demonstrated resilient top-line demand.
The segment generated $748 million in funded volume during the third quarter, matching the company-wide total and securing a 24% increase compared to the same period in 2025. For the first nine months of the year, cumulative funded volume in retirement solutions hit $2.07 billion, up 17% year-over-year, while segment revenue climbed 14% to reach $208 million.
Despite strong origination volumes, profitability within the segment experienced noticeable compression. Revenue margins for retirement solutions dropped to 9% in the third quarter of 2026, down from 11.3% in the third quarter of 2025 and trailing the historical average of 10.7% maintained since the beginning of 2024.
Quarterly segment revenue totaled $67 million, slipping 1% from the prior year and declining from the $74 million posted in the second quarter of 2026. Pretax income for the segment fell to $3 million, down from $10 million a year earlier, while adjusted net income retreated to $9 million from $20 million.
President Kristen Sieffert highlighted the diverse nature of the company’s product portfolio during the earnings presentation. She emphasized that submission and funded volumes have maintained a consistent upward trajectory across all major product lines. Specifically, HECM volumes grew 14% year-over-year, proprietary HomeSafe first-lien products expanded by 15%, and HomeSafe second-lien products surged by 63%, illustrating broad adoption among older homeowners seeking liquidity.
Portfolio Management and Servicing Expansion
While origination arms focused on volume expansion, the Portfolio Management segment faced significant accounting headwinds. The segment, which derives revenue from net interest income and fair value fluctuations on portfolio assets, reported a pretax loss of $138 million for the third quarter of 2026. This compares unfavorably to a pretax loss of $11 million recorded in the third quarter of 2025.
The widening loss was primarily attributed to negative non-cash fair value adjustments on retained interests in securitizations, a reflection of the broader interest rate volatility during the period. On an adjusted basis, however, the portfolio management segment reported net income of $11 million, though this was down from $30 million a year earlier. For the first nine months of 2026, the segment posted a cumulative pretax loss of $128 million, contrasting with a pretax income of $202 million for the first nine months of 2025.
Despite the paper losses on asset valuations, the operational footprint of the portfolio expanded substantially. Assets under management (AUM) within the segment grew 23% year-over-year, reaching $37.4 billion. This growth was fueled by organic originations and a major strategic acquisition: the successful onboarding of Onity Mortgage Corp.’s HECM servicing portfolio, which was finalized on July 1, 2026.
Corporate Strategy, Debt Management, and Outlook
Looking beyond the immediate financial reporting period, Finance of America executives outlined a disciplined capital allocation strategy designed to strengthen the balance sheet while capitalizing on demographic trends.
Chief Financial Officer Matt Engel reported that the company is on track to execute a $60 million paydown of senior secured notes in November 2026, a move that will reduce ongoing debt servicing costs and enhance overall financial flexibility.
Looking ahead to the fourth and final quarter of 2026, leadership expressed strong optimism regarding origination pipelines. FOA forecasts that total funded volume for the upcoming quarter will reach between $3.1 billion and $3.4 billion. Company officials noted that this projected volume is supported by favorable consumer demographics—specifically the aging population of older Americans requiring alternative retirement funding sources—alongside the company’s product breadth and ongoing improvements in digital and operational conversion rates.
Industry analysts observe that while noncash fair value adjustments and margin compression created headline-grabbing losses in the third quarter, Finance of America’s underlying growth metrics, successful portfolio expansion, and proactive repricing strategies suggest the firm is positioning itself to weather macroeconomic turbulence and capitalize on long-term market demand for home equity solutions.