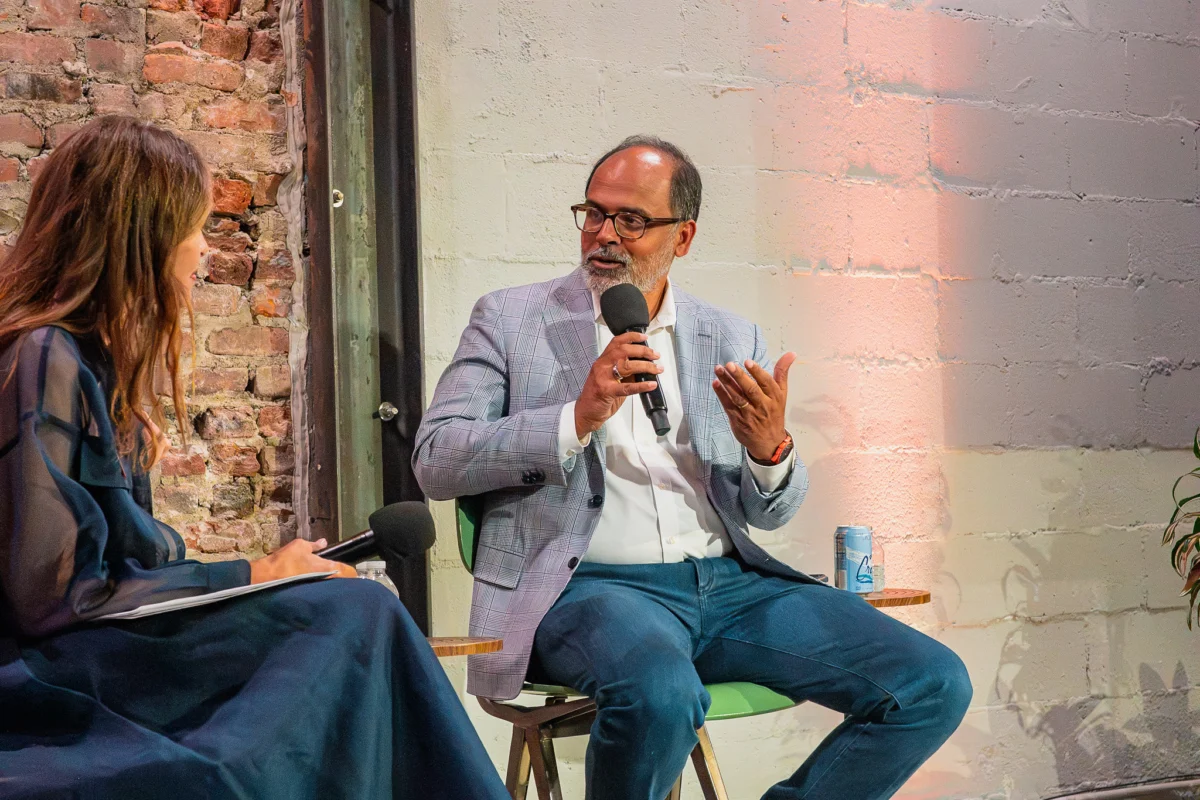
Insight Partners has quietly maneuvered to the apex of global software investing, managing a staggering $90 billion in assets under management (AUM) without cultivating the social media hyper-visibility characteristic of many contemporary venture capitalists. In an industry where executives frequently command headlines on X and populate podcast feeds, Devin Parekh, who has co-run Insight Partners for 26 years, represents a contrasting archetype. Eschewing public noise in favor of portfolio-driven performance, Parekh offered a rare, candid assessment of the venture capital landscape during a sit-down interview with TechCrunch at the StrictlyVC event in New York City.
The exclusive conversation touched upon the firm’s calculated bets across global markets, the realities of competing against rival mega-funds, internal debates over backing competing artificial intelligence giants, and the urgent necessity of returning liquidity to limited partners (LPs). Far from operating in an ivory tower, Parekh’s perspective reflects the balancing act required of a heavyweight institutional investor navigating macroeconomic headwinds, skyrocketing AI valuations, and shifting exit environments.
Main Facts and Current Market Strategy
Founded on the premise of scaling software companies through deep operational expertise, Insight Partners has spent more than two decades building a diversified portfolio that includes notable heavyweights like Databricks, alongside major stakes in frontier AI leaders OpenAI and Anthropic. Unlike firms that specialize strictly in early-stage seed rounds or late-stage buyouts, Insight utilizes a flexible, temporal allocation strategy.
According to Parekh, the firm does not adhere to fixed geographic or stage quotas across its funds. However, market conditions have directly altered deployment tactics. With high interest rates, restrictive software debt markets, and compressed exit multiples, Insight has largely paused major buyout activity since 2024.
Instead, the firm has adjusted its venture approach in response to soaring early-stage valuations that mirror the frothy market of 2021. When follow-on rounds accelerate so rapidly that they fail to provide incremental data to offset risk, Parekh argues that the only logical response is to move earlier. Rather than writing monolithic $500 million checks into overheated late-stage rounds, Insight leverages its scale fund to deploy $20 million to $25 million checks into earlier-stage winners.
A prime example of this strategy is cybersecurity decacorn Wiz. Insight participated in the Series A round and continued writing checks through subsequent stages, maximizing its financial gains. Parekh noted that if Wiz had failed, the initial losses would have barely registered against a fund of Insight’s magnitude. Conversely, disciplined scaling allowed the firm to capture outsized returns.
Chronology and Historical Evolution of Insight’s Playbook
To understand Insight Partners’ longevity—currently operating on its 13th flagship fund—one must examine its historical pivot toward liquidity and opportunistic deal-making. In its earlier years, the firm occasionally fell into the common venture trap of holding onto winning positions indefinitely, subscribing to the belief that a stellar asset should never be sold.
However, over the past two years, Insight has returned more than $20 billion to its limited partners through strategic secondary sales and initial public offerings, with billions more projected. This realization underscores a fundamental shift in venture capital: limited partners demand realized liquidity (DPI, or distributed-to-paid-in capital), not just paper markups.
This pragmatic philosophy was also evident in the firm’s history with security firm Armis. Initially losing the primary deal to Sequoia Capital, Insight kept the relationship alive by deploying a modest $5 million check from an $11 billion fund. Eighteen months later, Insight capitalized on an inflection point, buying out the entire cap table—including Sequoia—with a nine-figure check. The calculated risk culminated in ServiceNow acquiring Armis for $7 billion, demonstrating that small initial stakes can evolve into major liquidity events through patient relationship management and timely execution.
Supporting Data and Macroeconomic Realities in AI
The contemporary venture landscape is heavily dominated by frontier AI infrastructure, with OpenAI and Anthropic reportedly capturing roughly half of all venture capital dollars deployed during the first half of the year. This extreme capital concentration has sparked intense debate regarding risk exposure for institutional investors.
While some boutique funds raise capital entirely on the thesis of allocating 35% to 40% of their assets into one or two foundational AI labs, Parekh warns against excessive concentration. Insight’s multi-fund strategy is designed to weather long-term economic cycles rather than chasing momentary market euphoria. Although a 25% allocation to Anthropic would temporarily inflate short-term returns, historical data demonstrates that long-term venture outperformance rewards diversification.
Simultaneously, Parekh addressed the pervasive societal and professional anxieties surrounding AI safety, drawing a distinction between speculative existential risks and immediate medical applications. Referencing his role on the board of NYU Langone Health, Parekh highlighted how machine learning models analyzing tens of millions of patient records can identify early indicators of life-threatening cardiac events years in advance. In an aging global demographic facing acute shortages of medical professionals, Parekh contends that scaling healthcare capacity through artificial intelligence is not merely advantageous—it is an economic and humanitarian necessity.
Regarding physical AI and robotics, Insight maintains a cautious posture. Parekh described physical intelligence ventures as sophisticated science projects, noting that successful commercialization relies on unproven assumptions regarding the timeline of mass robotics adoption. While acknowledging that younger investors—such as his 23-year-old son—view robotics as the premier growth frontier, Insight prefers to monitor the sector until clear market maturation occurs.
Official Responses and Industry Dynamics
Competition for premier global talent remains fierce, transcending traditional Silicon Valley boundaries. Parekh pointed to Insight’s pursuit of Legora, a buzzy European AI legal-tech enterprise based in Stockholm. Despite efforts by Insight partner Jeff Horing, who flew directly to Sweden to pitch the founders, the deal ultimately went to General Catalyst. Parekh attributed the loss to a superior value proposition presented by competing investors during that specific pitch, emphasizing that in a globalized ecosystem, missing out on individual deals is an expected operational friction point.
Geographic talent distribution varies significantly by vertical sector. While foundational AI infrastructure remains heavily concentrated in San Francisco, specialized enterprise verticals exhibit greater geographic dispersion. For instance, financial technology talent for companies like Ramp remains deeply rooted in New York City, enabling localized investing strategies that bypass traditional tech hubs.
Furthermore, Insight’s decision to back both OpenAI and Anthropic illustrates the complex evolution of governance and competitive exclusivity in late-stage tech. While early-stage venture capital strictly prohibits backing direct competitors due to severe information-sharing sensitivities, later-stage investing functions closer to public market stock acquisition. As foundational AI companies scale capital requirements into tens of billions of dollars, they have outgrown the era of strict investor exclusivity. Insight views OpenAI as a dominant consumer-facing play and Anthropic as a robust enterprise strategy, though the boundaries between these business models continue to shift.
Broader Impact and Implications for the Venture Capital Ecosystem
Looking ahead, the macroeconomic implications of impending public offerings from tech giants like Anthropic, OpenAI, and SpaceX are set to redefine public market expectations. With valuations scaling from inception to tens of billions of dollars in mere years, public market investors face unprecedented velocity in value creation. However, sustaining hyper-growth rates of 10x multiples indefinitely is mathematically unsustainable for trillion-dollar enterprises.
As the industry cycles through periods of capital scarcity and abundance, Parekh advises founders navigating frothy valuation environments to de-risk judiciously. When presented with aggressive offers from enthusiastic markets, founders are encouraged to lock in 10% to 20% liquidity to protect against inevitable macroeconomic corrections.
Ultimately, Insight Partners’ enduring footprint demonstrates that massive asset scale does not necessitate performative public loudness. By prioritizing disciplined portfolio reviews—such as analyzing hundreds of portfolio companies across multi-day sessions to identify inflection points—Insight reinforces the core mandate of venture capital: backing exceptional entrepreneurs while delivering tangible, realized liquidity back to the market.