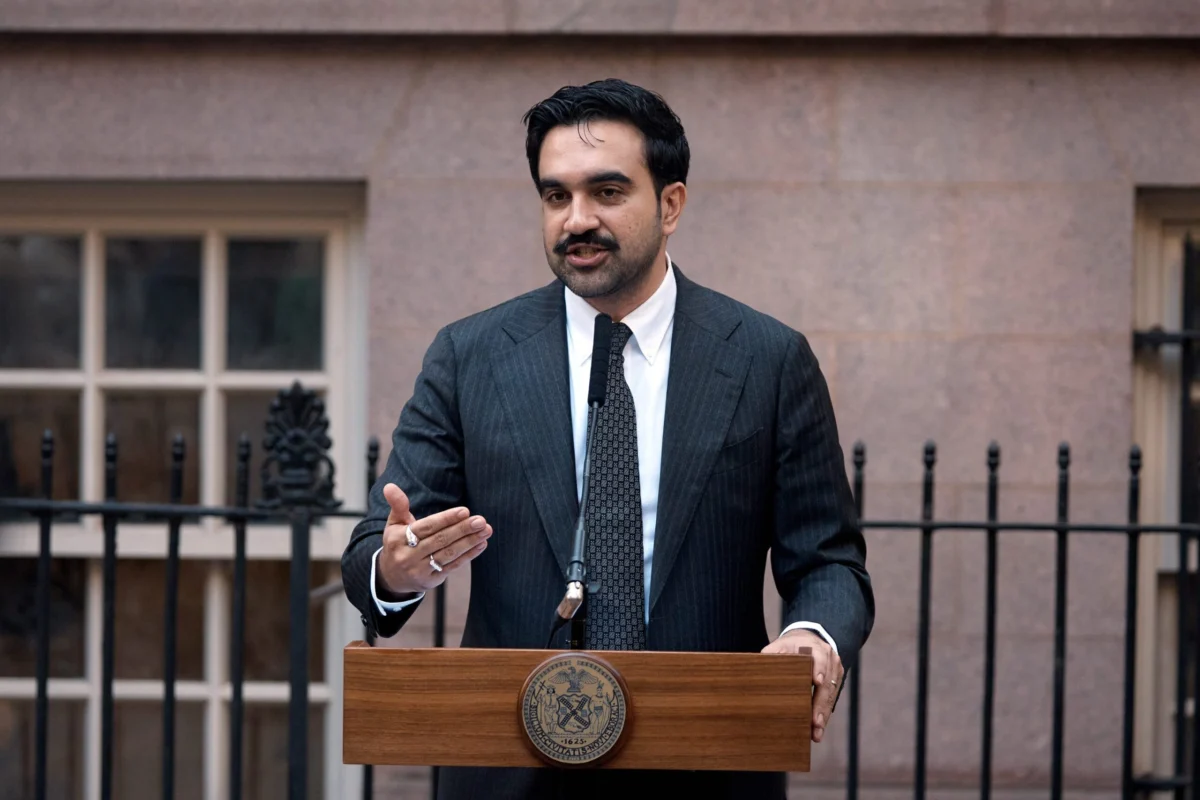
In a significant legal victory for the administration of Mayor Zohran Mamdani, a New York appeals court on Wednesday issued a unanimous ruling that effectively dismantles a high-profile legal challenge against the city’s controversial pied-à-terre tax. The Appellate Division, Second Department, reversed a previous judgment from the Staten Island Supreme Court, concluding that the homeowners who initiated the litigation failed to establish the legal standing necessary to contest the rollout of the surcharge. The decision represents a pivotal moment for the Mayor’s signature revenue-generating policy, which has faced intense scrutiny from real estate stakeholders since its inception.
The four-judge panel, which delivered its verdict just one week after hearing oral arguments, found that the plaintiffs’ claims of injury were insufficiently concrete to warrant judicial intervention. By dismissing the case, the court has cleared a major hurdle for the Department of Finance (DOF) as it continues the arduous process of identifying luxury properties subject to the new tax.
The Genesis of the Dispute
The lawsuit, filed in August by a coalition of seven homeowners represented by former First Deputy Mayor Randy Mastro, sought to halt the city’s implementation of the tax. At the heart of the plaintiffs’ complaint was the method by which the city identified potential taxpayers. The DOF had generated a supplemental roll comprising roughly 900,000 properties and subsequently mailed notices to approximately 17,000 owners, effectively placing the burden of proof on the property owners to demonstrate that their homes were primary residences rather than secondary, luxury dwellings.
The plaintiffs argued that the city’s process was administratively overreaching and flawed, asserting that the government should have utilized existing municipal and tax records to verify residency before initiating a widespread outreach campaign. They contended that the receipt of such notices—and the subsequent requirement to prove primary residency—imposed an undue burden and potential reputational or financial harm on homeowners.
The Court’s Rationale: Lack of Standing
The Appellate Division’s ruling focused heavily on the concept of "standing"—the legal requirement that a plaintiff must show they have suffered a direct, concrete, and particularized injury to sue. In their decision, the judges dismissed the plaintiffs’ arguments as speculative. The court noted that the receipt of a notice from the city, while perhaps inconvenient, serves an "informational purpose" analogous to a standard debt collection communication.
Furthermore, the panel observed that the state legislature, in drafting the tax law, clearly anticipated that the initial list of notice recipients would not be perfect. The inclusion of an exemption process within the legislation was cited by the court as evidence that the system was designed to handle inaccuracies without requiring judicial oversight at every turn.
Regarding the plaintiffs’ claims of generalized anxiety or administrative burden, the court characterized these as "tenuous and ephemeral." The judges highlighted that the city’s annual assessment rolls already disclose sensitive information—such as owner names, assessed property values, and market values—rendering the claim that the new notices uniquely exposed homeowners to risks like stalking or fraud unconvincing. Additionally, the court noted that the cost of applying for an exemption is a standard component of tax compliance, and the plaintiffs failed to provide documented evidence of quantifiable financial loss.
A Chronology of the Pied-à-Terre Controversy
The legal battle is merely one chapter in a long-standing debate over the tax. The following timeline outlines the evolution of this policy:
- Early 2026: Mayor Mamdani introduces the pied-à-terre tax as a cornerstone of his economic platform, aiming to tap into the wealth of non-resident owners of luxury homes to fund city infrastructure and housing initiatives.
- Summer 2026: The Department of Finance releases its supplemental rolls, sparking immediate backlash from wealthy property owners and industry groups.
- August 2026: A group of seven homeowners files suit in Staten Island, represented by Randy Mastro, challenging the constitutionality and procedural fairness of the notices.
- Late August 2026: The city receives updated income-tax data from the state, allowing the DOF to clear over 1,200 owners who were erroneously flagged for the tax.
- September 2026: Staten Island Supreme Court Justice Wayne Ozzi grants the homeowners injunctive relief, temporarily pausing the enforcement of the notices.
- October 2026: The Appellate Division hears the city’s appeal, culminating in the current reversal of Justice Ozzi’s decision.
Economic Implications and Revenue Projections
The fiscal stakes of the pied-à-terre tax are substantial. Comptroller Mark Levine initially estimated that the tax could generate up to $380 million annually from a pool of approximately 11,200 properties. Mayor Mamdani, however, has been more optimistic, projecting annual revenues reaching $500 million. These funds are earmarked to address critical gaps in the city’s budget, particularly in public works and affordable housing programs.
The implementation process has not been without its technical hurdles. Following the initial rollout, the city faced criticism for "blanket" mailing strategies. However, the DOF has since refined its approach. By utilizing updated state income-tax data, the city has successfully cleared thousands of owners from the list of potential tax liabilities. As of late 2026, the DOF reports that over 8,800 exemption requests have been processed and granted, suggesting that the administrative framework is beginning to stabilize despite the initial confusion.
Official Responses and Political Fallout
Following the ruling, Mayor Mamdani was quick to frame the court’s decision as a moral victory. "The court has rejected an attempt by the ultrawealthy to avoid paying their fair share," Mamdani stated in a press release. He emphasized that ownership of a second home valued in excess of $5 million carries an inherent responsibility to contribute to the city’s economic ecosystem.
Mamdani’s administration has signaled a clear intent to move forward aggressively. Despite the victory, the Mayor acknowledged that the city remains locked in ongoing legal battles, specifically citing challenges brought in Suffolk County. He categorized these legal actions as the work of the same "uberwealthy interests" whose arguments were deemed insufficient by the appellate court.
"We will implement the pied-à-terre surcharge fairly and efficiently," the Mayor added, "ensuring that those most able to contribute do their part to build a city that works for everyone."
Looking Ahead: The Broader Legal Landscape
While the Appellate Division’s ruling resolves the specific procedural concerns raised by the initial group of seven plaintiffs, it does not mark the end of the legal war over the tax. According to reports from Gothamist and other outlets, the surcharge remains the subject of at least three other separate legal challenges. These suits are expected to touch upon different constitutional and administrative arguments, potentially including the claim that the DOF ignored its own internal guidelines regarding the use of 2024 income-tax data.
From a policy standpoint, the ruling strengthens the city’s hand. By setting a high bar for what constitutes a "concrete injury" in tax-related litigation, the court has effectively narrowed the window for future challenges based on administrative inconvenience. For property owners, the message is clear: the path to challenging the tax will likely require demonstrating a direct, quantifiable financial harm rather than a generalized grievance regarding the city’s administrative processes.
As the city proceeds with its collection efforts, the focus will likely shift from the legality of the rollout to the accuracy of the final assessment lists. With over 8,800 exemptions granted, the DOF is under pressure to ensure that the remaining taxpayers are correctly identified to avoid further litigation. The success of the pied-à-terre tax as a revenue source will ultimately depend on the city’s ability to maintain this balance—securing funds from the city’s wealthiest residents while minimizing the administrative burden on the broader real estate market.
For now, the Mamdani administration has secured the necessary legal breathing room to continue its ambitious fiscal agenda, setting a precedent that will influence future tax enforcement cases throughout the five boroughs.