The United States housing market is entering a more volatile phase as a long-standing correction expands beyond the Sunbelt states into previously resilient regions, including the Northeast and Midwest. While nominal home prices—the figures listed on contracts and tracking services—have remained largely positive, market analysts report that these headline numbers are increasingly deceptive. A combination of rising mortgage rates, cooling buyer demand, and a shift in seller behavior suggests that the housing sector is moving toward a sustained period of price adjustment rather than a short-term dip.
The Anatomy of the Current Correction
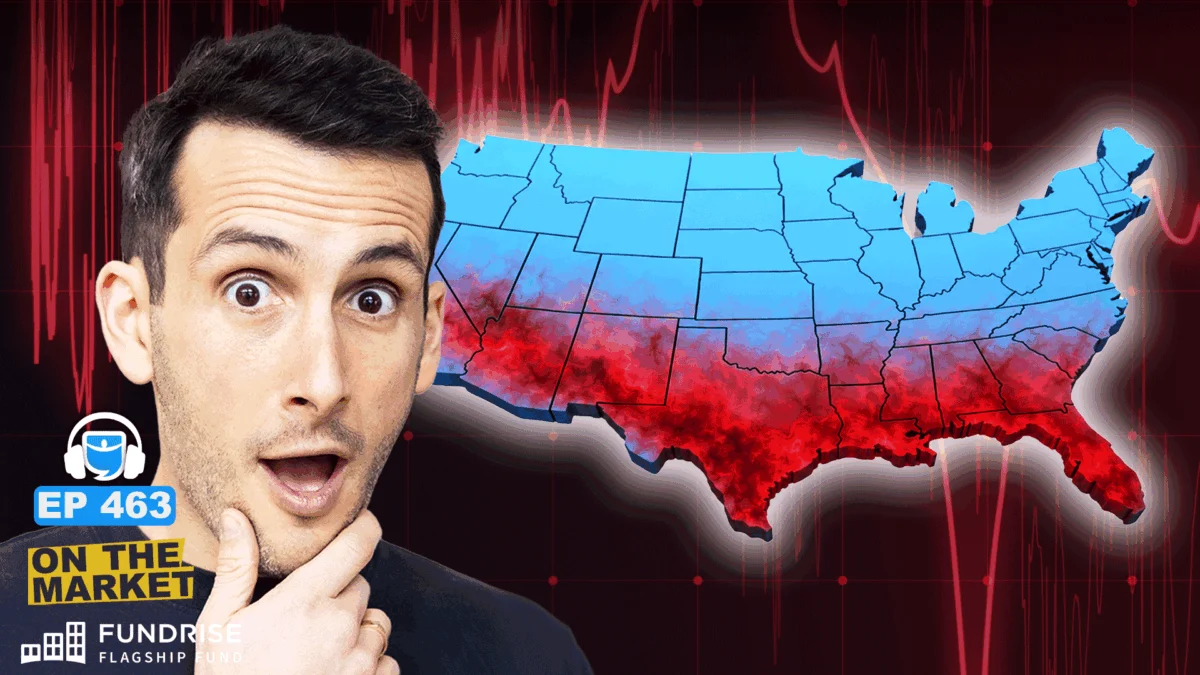
For the past four years, the housing market has operated under the shadow of a correction that remained largely regionalized. Markets such as Austin, Texas, and Phoenix, Arizona, experienced significant price pullbacks after the pandemic-era boom. However, recent data indicates that the "safe" havens of the Northeast and Midwest are no longer insulated from these pressures.
Economic analysts distinguish between nominal prices and "real" prices, which are adjusted for inflation. When accounting for current inflation rates, real home prices have been trending downward for 48 months. According to data from the S&P CoreLogic Case-Shiller Index and the Calculated Risk blog, inflation-adjusted home prices currently sit approximately 5% below their 2022 peak. This trajectory is consistent with historical housing cycles, which often last seven years or longer, suggesting that the current cooling period may be only at its midpoint.
Shifting Seller Dynamics and Hidden Discounts
One of the most significant factors obscuring the true state of the market is the prevalence of seller concessions. In a standard market, home prices are determined by the final sale price. However, in the current environment, many sellers are opting to provide concessions—such as temporary interest rate buydowns, closing cost assistance, or repair credits—rather than lowering the sticker price.
Recent reports from Redfin indicate that approximately 45% of home sales now involve some form of seller concession, a figure that has steadily climbed from roughly 42% just one year ago. This trend is even more pronounced in the new construction sector, where builders, wary of lowering prices and setting lower property comps for future sales, offer substantial incentives to move inventory. Approximately two-thirds of new construction sales now feature concessions, with average price reductions reaching roughly 6% for those builders who do opt for direct cuts.
When these concessions are factored into the total cost of acquisition for the buyer, the nominal 1.5% year-over-year growth cited by the National Association of Realtors (NAR) effectively evaporates, pointing toward a market that is, in real terms, either stagnant or experiencing modest negative growth.
Demand Softening and the Mortgage Rate Impact
The primary catalyst for the current market shift remains the elevated mortgage rate environment. The Mortgage Bankers Association (MBA) purchase index, which tracks mortgage applications for home purchases, has seen a substantial decline. Current activity is roughly half of the long-term historical average, falling significantly from 2023 levels.
Several factors are contributing to this decline in demand:
- Interest Rate Sensitivity: With mortgage rates remaining stubbornly high, the cost of borrowing has significantly reduced the purchasing power of the average American household.
- Economic Uncertainty: Growing concerns regarding potential labor market instability, particularly in white-collar and technology sectors, have caused prospective buyers to adopt a more cautious stance.
- Inflationary Pressures: Broader cost-of-living increases, including rising fuel, food, and automotive expenses, have reduced the discretionary capital available for down payments and monthly housing costs.
As a result, pending home sales have dropped by 5.5% year-over-year, reaching levels not seen in nearly three years. Existing home sales have similarly faltered, recently dipping below the four-million-unit threshold for the first time in over a year.
Supply Trends and the End of De-listings
Historically, supply remained low during the initial years of this correction because sellers who could not achieve their target price simply withdrew their properties from the market. This "lock-in" effect—largely driven by homeowners holding sub-4% mortgage rates—prevented a surge in inventory that would have forced a more rapid price collapse.
However, recent data shows that de-listings have fallen by 13% year-over-year. This indicates that sellers are becoming increasingly pragmatic. Realizing that interest rates are unlikely to return to pandemic-era lows in the near term, more homeowners are choosing to accept current market conditions rather than waiting for a rebound. Consequently, existing inventory has risen to 1.62 million units, an increase of 6% compared to the previous year, marking the highest inventory level since late 2019.
Regional Rotation and the Path Forward
The market is currently undergoing a "rotation." In the South, where price corrections began earlier, there are signs that the decline is moderating. Cities like Austin and Dallas-Fort Worth are seeing a stabilization in inventory and, in some cases, a slight uptick in price activity. Conversely, the Midwest and Northeast are now seeing an acceleration in inventory growth, with markets such as Detroit, Indianapolis, and Baltimore experiencing a deceleration in home price appreciation.
This regional shift suggests that the correction is broadening its scope. While a "2008-style" crash remains unlikely due to current, stricter lending standards and the fact that a large portion of homeowners are not under immediate financial distress, the market is bracing for a period of extended stagnation.
Implications for Investors and Homebuyers
For potential investors and homebuyers, the current environment necessitates a shift in strategy. The era of assuming rapid, automatic appreciation has largely passed. Market analysts suggest that buyers should:
- Underwrite for No Appreciation: Investors should evaluate properties based on cash flow and intrinsic value rather than relying on future market price increases.
- Prioritize Disciplined Acquisition: In a buyer’s market, patience is a tactical advantage. Buyers are encouraged to walk away from deals that do not meet specific financial criteria, such as a requirement for 10% to 15% discounts below comparable sales.
- Negotiate Concessions: Given that nearly half of all transactions involve concessions, buyers should aggressively negotiate for rate buydowns or seller-paid closing costs to offset the impact of high mortgage interest rates.
Ultimately, the housing market is moving toward a more balanced state where buyers possess greater leverage than they have in nearly a decade. While this correction does not signal an immediate collapse, it does represent a fundamental reset of expectations. The market is transitioning from a period of unbridled growth to a "grind," where value is found through careful selection and rigorous underwriting rather than speculative participation. As the correction continues to spread geographically, the coming year will likely be defined by a slow, systematic adjustment to a new economic reality.