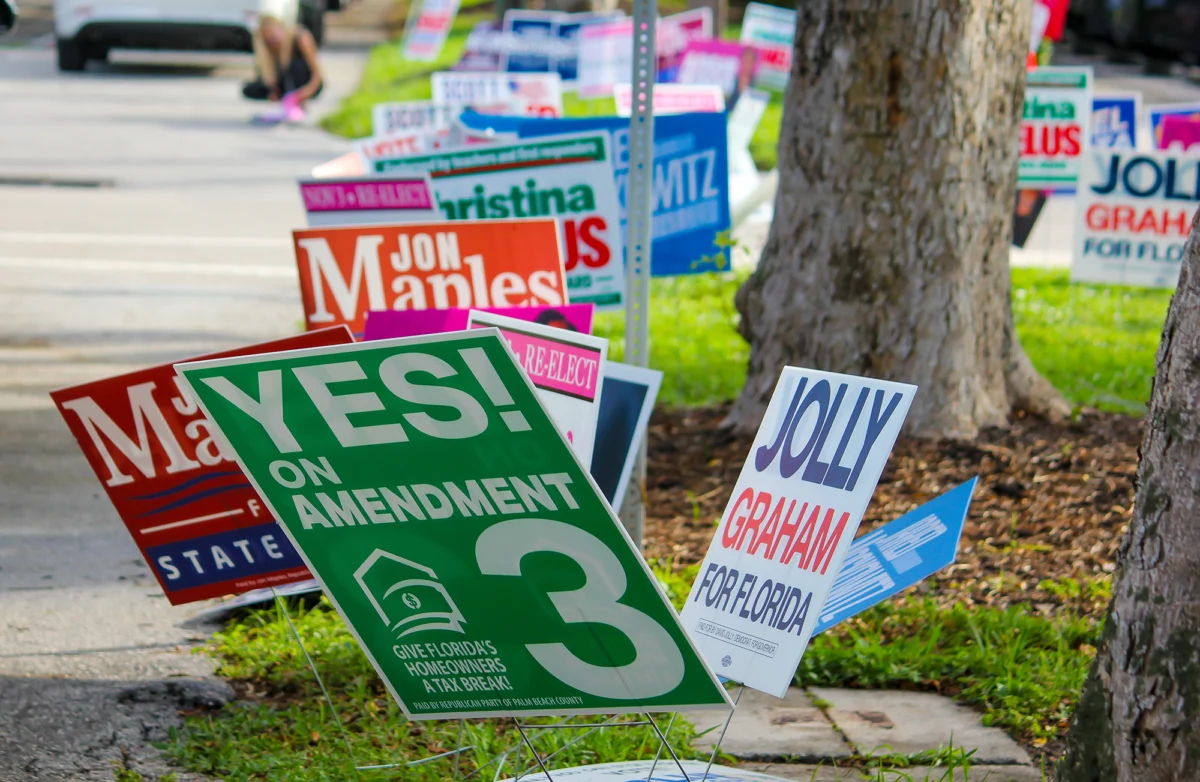
For those who spent the first week of November disconnected from the global news cycle, the political landscape of the United States has undergone a fundamental transformation. The midterm elections resulted in a decisive shift toward Democratic control, with the party securing majorities in both houses of Congress and capturing the gubernatorial offices in at least 27 states, including influential markets such as Texas, Ohio, and Georgia. For the commercial real estate sector, which relies heavily on regulatory stability, tax policy, and interest rate environments, this "Blue Wave" signals a new era of federal intervention and state-level policy experimentation.
The immediate focus for industry analysts and stakeholders is how this shift will influence two of the most capital-intensive and politically sensitive areas of the market: housing production and the rapid expansion of digital infrastructure through data centers.
A New Federal Mandate for Housing Policy
The legislative agenda for the upcoming session appears poised to move away from market-driven housing solutions toward a more interventionist federal model. During the campaign, several prominent Democratic leaders signaled an intent to utilize federal leverage to alleviate the nation’s chronic housing shortage.
James Whelan, president of the Real Estate Board of New York (REBNY), underscored the industry’s cautious optimism regarding this shift. "Washington cannot solve New York’s housing shortage on its own, but it can make housing dramatically easier to finance, approve, and build," Whelan stated. He urged the new congressional majority to prioritize the expansion of capital for affordable housing, remove federal regulatory bottlenecks, and ensure full funding for existing housing authorizations.
The scope of potential federal investment is significant. Rep. Maxine Waters, widely expected to chair the House Financial Services Committee, has advocated for a $1 trillion housing investment strategy. The primary objectives of this proposal include a systemic reduction in homelessness and the provision of robust subsidies for low-income homeowners. Parallel to this, the "Homes Act," a $30 billion legislative proposal championed by Rep. Alexandria Ocasio-Cortez, is expected to gain significant traction. The bill seeks to acquire distressed housing assets and convert them into permanent, government-subsidized affordable housing. While proponents argue this is a necessary step to stabilize the middle-class housing market, critics worry about the inflationary impact of such massive federal spending on the broader construction sector.
State-Level Volatility and Local Market Shifts
While federal policy dominates the headlines, the state-level outcomes of last Tuesday’s election are already causing tangible market reactions. In Florida, voters approved Amendment 3, a measure designed to halve the cap on property tax increases. While the move is popular among homeowners, fiscal analysts warn that the legislation could significantly constrain state revenue, leading to budgetary shortfalls and potential reductions in municipal services.
The sentiment in local markets is similarly mixed. In South Florida, voters rejected high-profile development proposals, including Robert Rivani’s planned office complex in South Beach and the RCI Marine Group and Suntex Marinas projects on Virginia Key. These rejections highlight a growing trend of local resistance to large-scale commercial development, a challenge developers must increasingly navigate.
In California, the atmosphere remains tense as Proposition 45 remains too close to call. The proposal, which seeks to streamline environmental regulations to accelerate construction, has become a lightning rod for debate. Critics argue that the bill acts as a "Trojan Horse," intended to bypass stringent oversight for the construction of energy-intensive data centers—an asset class that has faced intense public scrutiny in recent months due to its massive electricity and water consumption profiles.
Earnings Season: A Sector in Transition
The recent wave of Q3 earnings reports provides a quantitative snapshot of an industry navigating high interest rates and shifting demand. The newly merged entity of AvalonBay Communities and Equity Residential, operating as Vivmark Residential, reported $1.19 billion in revenue with a net operating income (NOI) of $800.76 million. Despite a healthy 95.8 percent occupancy rate and a $4.4 billion development pipeline, the company reported a $747 million quarterly loss, reflecting the high costs of integration and interest rate pressures.
The office sector continues to demonstrate the most significant variance in performance. Starwood Property Trust reported a challenging quarter, with a 95 percent year-over-year drop in net income and a net loss of $389.7 million. Conversely, Simon Property Group outperformed market expectations, generating $1.8 billion in revenue—a 13.3 percent increase over the previous year—and achieving a 96.5 percent occupancy rate.
Brookfield Asset Management maintained its momentum, securing $25 billion in new fundraising during the quarter, bringing its total 2026 capital raise to $123 billion. Cushman & Wakefield also showed signs of recovery, with revenue climbing to $2.8 billion from $2.6 billion in the same period last year. Michelle MacKay, global CEO of Cushman & Wakefield, emphasized the firm’s strategic pivot: "We have executed our deleveraging plan and expect to move to a more balanced capital allocation strategy."
The Manhattan Office Market: A Resurgence?
Despite broad concerns about the future of remote work, Manhattan’s office market showed resilience in the fourth quarter. Colliers reports that leasing activity rose by 54 percent in October compared to September. Major institutions continue to commit to the city, evidenced by MetLife’s expansion at 200 Park Avenue, where the firm increased its footprint from 450,000 to 500,000 square feet. This activity suggests that while the office sector is undergoing a transformation, demand for high-quality, Class A space in central business districts remains robust.
Strategic Shifts in Human Capital
The industry is also seeing a shuffle in leadership, reflecting the need for firms to align themselves with new government priorities. At a recent industry forum, it was announced that Mark Weiss of Cushman & Wakefield would serve as commissioner of the General Services Administration’s (GSA) Public Buildings Service, overseeing a portfolio of 360 million square feet of government property.
Other notable movements include:
- Gene Spiegelman: Rejoining Cushman & Wakefield as vice chairman after a tenure at Ripco Real Estate.
- Michael Gordon: Leaving the Walt Disney Company to lead the construction of 175 Park Avenue, a major mixed-use project by TF Cornerstone and RXR.
- Adam Griff: Transitioning from Gensler to JLL to serve as managing director of the firm’s nonprofit, education, and government department.
Outlook for the Future
As the dust settles from the election, the commercial real estate industry faces a complex environment. The transition toward a more active federal role in housing will likely provide new avenues for financing, but may also introduce stricter compliance and regulatory burdens. The divergent performance of REITs and asset managers suggests that success in the coming year will be defined by the ability to manage debt-to-equity ratios and adapt to the changing preferences of both tenants and local communities.
Looking ahead, the market is bracing for further volatility in the office sector as existing leases expire and firms reassess their spatial requirements. For lenders, the primary challenge remains the "higher-forever" interest rate environment, which has fundamentally altered the math for opportunistic investments. Whether these conditions will favor the borrower or the lender remains the central question for the 2027 fiscal year. As the industry recalibrates, the focus remains on operational efficiency and the strategic deployment of capital in an increasingly regulated, yet potentially high-growth, landscape.





