Navigating the complexities of personal finance in an era defined by economic volatility, persistent inflationary pressures, and mounting systemic uncertainties has become an increasingly daunting challenge for American households. Amid growing anxieties regarding long-term financial security, a comprehensive new report published this week by AARP outlines six foundational metrics designed to provide individuals with a clear, realistic snapshot of their financial health. Designed to cut through the noise of modern economic life, these indicators offer a practical framework for evaluating everything from daily liquidity to long-term retirement readiness, empowering consumers to identify vulnerabilities and execute course corrections before minor fiscal missteps morph into full-scale crises.
The release of the AARP framework arrives at a critical juncture for the American workforce. According to data cited from the Employee Benefit Research Institute’s (EBRI) 2026 Retirement Confidence Survey, approximately two in five U.S. workers harbor deep-seated concerns that they will lack the financial resources necessary to maintain a comfortable standard of living throughout their retirement years. This widespread unease is compounded by a confluence of macroeconomic headwinds, including sustained cost-of-living increases, mounting anxiety over the long-term solvency and reform trajectories of federal entitlement programs like Social Security, and record levels of household debt among older demographics. By breaking down personal finance into six discrete, quantifiable numbers, the AARP report seeks to demystify wealth management and provide a step-by-step diagnostic tool for individuals across all age brackets.
Decoding Monthly Cash Flow and Liquidity Management
The foundational starting point of the AARP financial health diagnostic is monthly cash flow, a fundamental measure of day-to-day economic stability. Calculated simply by subtracting total household recurring and discretionary expenses from net take-home pay, monthly cash flow reveals whether an individual is living within their means or quietly eroding their net worth.
A positive cash flow indicates that income exceeds outlays, creating surplus capital that can be systematically funneled toward emergency savings, investment vehicles, or debt acceleration. Conversely, a negative cash flow signals that spending is dangerously outpacing earnings, a trajectory that inevitably forces reliance on revolving credit and short-term loans. For households caught in a negative cash flow cycle, the report emphasizes the necessity of a rigorous budget audit. This involves dissecting recurring expenditures—such as housing, utilities, subscriptions, and transportation—to identify immediate areas for contraction, alongside exploring avenues for supplemental income generation through side enterprises, skill monetization, or career advancement.
Financial planners frequently emphasize that cash flow is the beating heart of personal finance; without positive cash flow, long-term wealth accumulation remains a mathematical impossibility. By shining a spotlight on this metric, AARP aims to prompt proactive budgeting habits long before a cash crunch forces drastic and painful lifestyle alterations.
Navigating Social Security Estimates and Claiming Strategies
The second critical figure in the AARP metric suite centers on Social Security, the bedrock of retirement income for tens of millions of older Americans. Despite its vital role, many workers maintain a vague or inaccurate understanding of what their future benefit checks will actually look like.
AARP advises workers to actively monitor their estimated retirement benefits by establishing and regularly reviewing an online account through the Social Security Administration (SSA). These official projections provide a realistic baseline for what government support will contribute to a retiree’s monthly budget. However, knowing the projected benefit is only half the battle; understanding the mechanics of claiming age is equally transformative.
While eligible workers can legally begin collecting Social Security retirement benefits as early as age 62, doing so results in a permanent reduction in monthly payments compared to waiting until full retirement age—which typically ranges from 66 to 67 depending on birth year. Furthermore, for every month an individual delays claiming past their full retirement age, up until age 70, they accrue delayed retirement credits that increase their monthly benefit by roughly 8% per year.
In light of ongoing national debates regarding Social Security reform, fiscal sustainability, and potential legislative adjustments ahead of midterm elections, maximizing this guaranteed income stream through strategic timing has never been more crucial for prospective retirees looking to hedge against longevity risk.
Retirement Savings Realities and the Four Percent Rule
Moving from guaranteed government support to self-directed capital accumulation, the third metric demands a comprehensive inventory of private retirement savings vehicles. This encompasses the aggregate balances held across employer-sponsored plans such as 401(k)s and 403(b)s, traditional and Roth Individual Retirement Accounts (IRAs), and taxable brokerage accounts designated for post-work life.
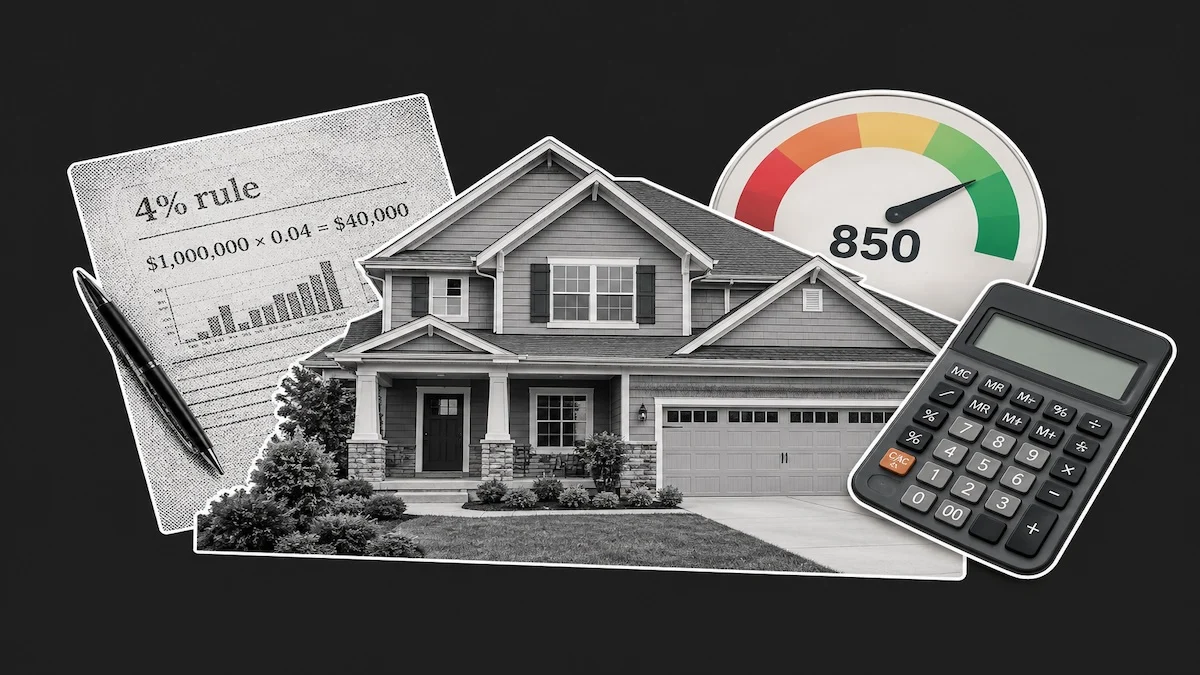
Once the total savings balance is tallied, the report suggests comparing this figure against anticipated post-retirement expenses, factoring in expected Social Security inflows and any pension or annuity streams. To help individuals translate a lump-sum savings balance into a sustainable annual income stream, the AARP report incorporates a version of the widely utilized 4% withdrawal rule.
Originally popularized by financial planner William Bengen in the 1990s, the 4% rule suggests that a retiree can safely withdraw 4% of their total retirement portfolio balance in the first year of retirement, and subsequently adjust that dollar amount upward for inflation in each subsequent year, with a high degree of confidence that the portfolio will last for at least 30 years. Although contemporary financial analysts continue to debate whether inflation volatility and shifting market valuations make the traditional 4% threshold too aggressive or overly conservative for today’s economic environment, the metric nevertheless serves as a vital mathematical benchmark. It forces workers to confront the stark reality of whether their accumulated nest egg will realistically support their projected longevity and lifestyle expectations.
Credit Scores and Borrower Health
Beyond income and savings, the AARP framework highlights the vital importance of the three-digit credit score. Calculated by major credit bureaus and scoring agencies like FICO and VantageScore, these scores act as a universal barometer of creditworthiness, directly influencing an individual’s financial fluidity and cost of capital.
Lenders rely heavily on credit scores when evaluating applications for revolving credit cards, automobile financing, personal loans, and residential mortgages. A strong credit score unlocks access to lower interest rates, translating into tens or even hundreds of thousands of dollars in lifetime savings on large capital purchases. Conversely, a depressed score can severely restrict financial options and inflate borrowing costs to prohibitive levels.
To strengthen this critical metric, AARP points to fundamental credit-building practices: making all debt servicing payments on time, maintaining a low credit utilization ratio (typically keeping revolving balances below 30%—and ideally below 10%—of total available limits), and regularly auditing credit reports for errors or fraudulent activity. Maintaining a robust credit profile not only facilitates smoother major transactions but also acts as an emergency financial buffer during unexpected economic downturns.
Tackling High-Interest Debt with Proven Methodologies
The fifth metric focuses squarely on the corrosive impact of expensive, high-interest debt. Unlike low-interest, tax-advantaged mortgages or strategic student loans, unsecured high-interest obligations—predominantly driven by revolving credit card balances and high-APR personal loans—can rapidly compound, turning modest purchases into insurmountable financial burdens.
The AARP report outlines two of the most widely accepted and empirically validated debt-payoff methodologies designed to systematically dismantle high-interest obligations: the avalanche method and the snowball method.
Under the debt avalanche strategy, borrowers direct all extra financial capital toward paying off the debt with the highest interest rate while maintaining minimum payments on all other accounts. Mathematically, this approach is the most efficient, as it minimizes the total amount of interest paid over the life of the debt acceleration journey.
Alternatively, the debt snowball strategy instructs borrowers to target the account with the smallest overall balance first, regardless of the interest rate. Once that small balance is eliminated, the capital previously allocated to it is rolled over into the next-smallest balance, creating a psychological "snowball" effect of quick wins. While technically generating slightly more interest cost over time, the behavioral momentum and psychological reinforcement provided by the snowball method make it exceptionally effective for individuals who struggle with burnout during long-term financial remediation.
The Debt-to-Income Ratio and Housing Market Implications
The sixth and final figure outlined in the AARP report is the debt-to-income (DTI) ratio, a metric that carries immense weight not only for personal budgeting but also for prospective homebuyers navigating the residential real estate market.
The DTI ratio is calculated by dividing an individual’s total recurring monthly debt payments—including mortgage or rent payments, minimum credit card payments, auto loans, and student loans—by their gross monthly income. According to the AARP report and broader institutional lending standards, conventional mortgage lenders generally prefer a total DTI ratio of 36% or less, though certain loan programs may permit higher thresholds depending on compensating factors such as cash reserves or exceptional credit scores.
A low DTI ratio signals to lenders that a borrower possesses sufficient disposable income to comfortably service new debt without risking default. For individuals eyeing homeownership, managing and reducing the DTI ratio is often the single most effective strategy to secure mortgage pre-approval and favorable interest rates in a competitive housing market.
Synthesis, Timeline, and Broader Economic Implications
When evaluated collectively, these six numbers transcend individual calculations to form an interconnected ecosystem of personal economic health. Financial analysts note that the true value of the AARP framework lies in its diagnostic timing. By encouraging regular evaluation of cash flow, Social Security projections, savings trajectories, credit scores, debt loads, and DTI ratios, consumers are empowered to diagnose systemic vulnerabilities years—or even decades—before catastrophic fiscal failure occurs.
This proactive stance is particularly vital in the context of broader macroeconomic trends taking shape through the mid-2020s. With baby boomers facing unprecedented retirement challenges, persistent inflation altering the purchasing power of fixed-income households, and ongoing legislative scrutiny surrounding entitlement programs, the margin for financial error has narrowed considerably.
Industry experts and policy observers emphasize that shifting the cultural narrative from reactive crisis management to proactive financial literacy is essential for stabilizing the American middle class. As economic pressures continue to evolve, tools like the AARP six-number assessment provide a reliable compass, ensuring that workers and retirees alike can navigate turbulent financial waters with clarity, confidence, and control.