The Australian Taxation Office has officially ceased accepting credit card payments, marking a major shift in how citizens and businesses settle their public liabilities. This abrupt operational change coincides directly with nationwide financial reforms implemented by the Reserve Bank of Australia (RBA) aimed at eliminating checkout surcharges on major payment systems, including Visa, Mastercard, and Eftpos.
The decision by the nation’s premier tax collection agency brings an end to a long-standing convenience for a subset of taxpayers who historically relied on credit cards to manage short-term cash flow issues or accumulate reward points. According to official statements from the agency, the ATO determined that absorbing the merchant service fees associated with credit card transactions would unfairly shift administrative banking costs onto the broader tax-paying public. As government agencies navigate the evolving financial regulatory landscape, the policy adjustment underscores a broader national push toward fee transparency and the reduction of intermediary processing costs within the Australian economy.
Background Context and Regulatory Drivers
The overhaul of Australia’s card payments system follows an extensive strategic review conducted by the Reserve Bank of Australia. RBA Governor Michele Bullock declared the legacy payment architecture no longer fit for purpose in a modern, highly digitized financial ecosystem. For years, consumers and businesses faced mounting friction over hidden or explicit card surcharges at retail checkouts, government portals, and service counters.

The RBA’s sweeping regulatory adjustments are designed to strip away these extra charges, forcing merchants, service providers, and institutions to absorb or restructure the underlying costs of digital transactions. While the private sector moved swiftly to update checkout protocols and pricing models, public sector entities faced intense scrutiny regarding the ethical handling of public funds.
The ATO’s rationale hinges on the principle that public revenue agencies should not act as indirect subsidizers of private credit card rewards programs or high merchant banking fees. By discontinuing credit card processing entirely, the government avoids passing the multi-million dollar burden of merchant fees onto the community pool. Critics and consumer advocates have pointed out that while this protects public coffers from unnecessary overhead, it places an immediate operational burden on lower-income earners or small business operators who occasionally use credit lines to navigate tight liquidity cycles.
Impact on Taxpayers and Direct Debit Arrangements
Although the overwhelming majority of Australian taxpayers utilize standard electronic funds transfers, BPAY, or direct debit from standard bank accounts, a dedicated minority relies on credit cards to manage their tax liabilities. The ATO has acknowledged that this transition period will require significant adjustments for affected individuals and commercial entities.
Taxpayers currently utilizing direct debit arrangements linked directly to a credit card face an immediate compliance hurdle. The agency has issued formal warnings indicating that any recurring payment plans tied to credit accounts must be manually updated to alternative payment methods before the next scheduled installment due after November 30. Failure to update these payment pathways risks triggering administrative defaults or non-compliance penalties associated with established payment arrangements.
To mitigate potential fallout, ATO representatives have emphasized that the agency remains committed to assisting vulnerable clients. Taxpayers experiencing genuine financial hardship, seasonal cash flow shocks, or extraordinary circumstances that impede their ability to meet traditional payment obligations are encouraged to contact the agency early to establish flexible, alternative support pathways.
Corporate Tax Transparency and Broader Economic Pressures
The credit card policy shift arrives concurrently with the release of the Australian Taxation Office’s latest corporate transparency report, which has injected fresh fuel into ongoing national debates regarding corporate accountability. The landmark data revealed that more than one-quarter of large corporate entities operating within Australia paid zero corporate income tax during the 2024-25 fiscal period.
Approximately 27% of reporting entities cited accounting losses—where operational expenses, depreciation, and capital investments outstripped gross revenue—to justify their zero-tax status. This mirrors historical trends observed among major multinational corporations, including telecommunications provider Optus and prominent mining ventures like Adani’s Queensland coal operations, which frequently report minimal or zero taxable income despite generating billions in gross revenue.
Despite these notable exemptions, the aggregate data demonstrates robust contributions from traditional economic powerhouses. A total of 4,299 entities, each earning a minimum of $100 million in total income, contributed a combined $87.5 billion in corporate tax revenue for the 2024–25 financial year, heavily anchored by the nation’s dominant mining and resources sectors.

However, regulatory focus is shifting rapidly toward emerging digital infrastructure. ATO Acting Deputy Commissioner Michelle Sams highlighted an increasing institutional focus on digital supply chains, software ecosystems, and data centers. Regulatory authorities are intensifying audits and cross-border financial tracking to ensure that modern tech infrastructure giants remit taxes proportionate to their actual economic footprint within the Australian market.
National Telecommunications and Infrastructure Resilience
Beyond fiscal policy, Australian infrastructure systems are undergoing synchronized upgrades to better protect communities from systemic shocks. In a parallel development, major telecommunications providers—including Telstra, Optus, and Vodafone—have officially activated a landmark temporary disaster roaming capability ahead of the high-risk summer bushfire and cyclone season.
Under this new framework, mobile network operators are legally and technically empowered to seamlessly transfer stranded subscribers onto a rival carrier’s network during declared natural disasters. When primary regional infrastructure fails due to extreme weather events such as floods, bushfires, or severe cyclones, affected customers will automatically regain basic connectivity for voice calls, text messaging, and emergency data access without incurring additional roaming fees.
While emergency triple-zero call handovers have existed for years, this expanded initiative ensures sustained baseline communication for communities isolated by prolonged power outages or physical tower destruction. Implementation parameters stipulate that temporary disaster roaming can be deployed across a maximum of three designated disaster zones simultaneously, encompassing up to 15 mobile sites per zone for rolling 24-hour windows, provided the affected regions are separated by at least 400 kilometers. Metropolitan areas are entirely excluded from the arrangement, preserving the commercial boundaries of urban telecom competition while fortifying vulnerable regional corridors.

Political Landscape and Public Sentiment
These sweeping regulatory, financial, and infrastructural adjustments form the backdrop of an increasingly volatile domestic political climate. Following leadership transitions within minor parties, prominent political figures have seized upon public fatigue regarding corporate influence and institutional disconnect.
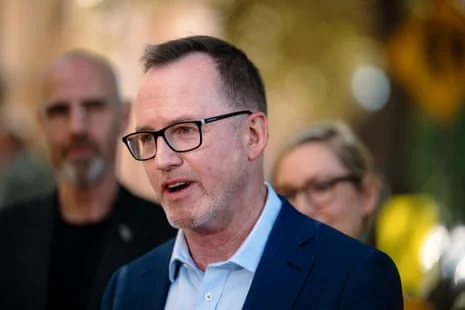
Greens Leader David Shoebridge recently addressed national media, arguing that the Australian electorate has grown weary of superficial political rhetoric. Positioning his party to capitalize on widespread disillusionment with traditional major parties, Shoebridge emphasized a platform centered on challenging corporate power structures and addressing systemic cost-of-living pressures. The political realignment highlights an electorate increasingly focused on tangible economic security, equitable taxation, and institutional reliability.
Implications and Future Outlook
The simultaneous rollout of RBA surcharging bans, the ATO’s credit card phase-out, new telecommunications disaster protocols, and rigorous corporate tax disclosures signal a period of profound structural adjustment for Australia.

For ordinary citizens, the elimination of credit card payments at the tax office requires immediate administrative vigilance, particularly for those managing structured payment plans. Simultaneously, the broader economic ecosystem must adapt to a cashless and surcharge-free retail environment designed to protect consumers from hidden point-of-sale costs. As regulatory bodies tighten compliance metrics around multinational digital assets and modernize public safety nets, Australia’s institutional framework is actively pivoting toward greater transparency, resilience, and consumer protection in an increasingly complex global economy.