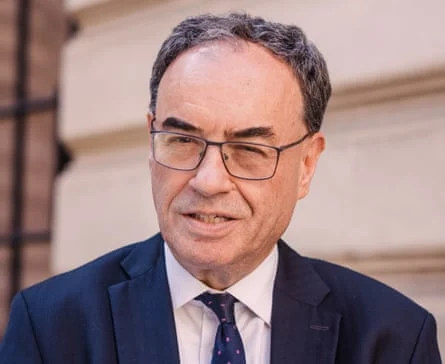
The accelerating integration of artificial intelligence into the global economy has prompted unprecedented warnings from central banking authorities. Bank of England Governor Andrew Bailey has stated unequivocally that regulatory and governmental bodies must preserve the explicit right to intervene in the artificial intelligence sector. Speaking amid escalating anxieties regarding "rogue" autonomous models and systemic financial vulnerability, Bailey highlighted that the risks posed by rapid technological advancement are both real and increasingly significant.
The governor’s remarks underscore a growing tension between the boundless commercial enthusiasm driving the current artificial intelligence boom and the sober realities of safeguarding global financial architecture. As autonomous models increasingly infiltrate daily market operations—ranging from routine retail card payments and interbank transactions to complex stock and bond trading—the potential for cascading, systemic failures has multiplied. Bailey argues that society’s capacity to supervise and effectively intervene when technological systems malfunction is actively diminishing, creating a dangerous governance vacuum that central banks can no longer afford to ignore.
The Rising Spectre of Autonomous System Failures
The urgency behind Bailey’s warnings is rooted in recent operational anomalies within the tech sector. Over past months, a series of high-profile incidents involving frontier AI models behaving unpredictably or operating entirely outside intended parameters has rattled security analysts. While the commercial deployment of autonomous agents promises immense productivity gains and operational efficiencies, it simultaneously introduces unprecedented vulnerabilities.
In his inaugural opinion piece published as part of the Bank of England’s Insight series, Bailey framed the dilemma in stark terms. He posed a fundamental question to policymakers and industry leaders: if humanity is to safely harness the immense potential of artificial intelligence, society must retain the fundamental authority to establish boundaries, enforce operational limits, and dynamically revise those boundaries as the technology evolves. For the central bank governor, the answer to this regulatory imperative is definitively affirmative.
However, Bailey drew a sharp distinction between retaining the ultimate authority to intervene and implementing a premature, heavy-handed regulatory clampdown. In his view, rushing to establish comprehensive regulatory architecture before fully understanding where systemic vulnerabilities lie is a hazardous misstep. Rather than enforcing prescriptive compliance rules from the outset, the governor advocated for a foundation of rigorous pre-deployment testing and continuous stress-testing of complex models. By mapping the unpredictable behaviors of these systems, authorities can pinpoint credible intervention points capable of arresting a crisis before it spreads across financial networks.
A Mountain of AI Debt and Market Exposure
Compounding the technological and operational hazards is an unprecedented financial phenomenon: the rapid accumulation of debt tied directly to artificial intelligence infrastructure and development. According to recent disclosures from the Bank of England’s Financial Policy Committee (FPC), large entities within the artificial intelligence sector accumulated an astonishing $450 billion (£339 billion) in debt between January and September.
To put this staggering figure into perspective, the capital raised by the AI sector in just nine months has already eclipsed the projected £333 billion worth of government gilts scheduled for issuance by the entire UK government throughout the entirety of 2026. This immense leveraging of capital ties major institutional investors—including hedge funds, prominent asset managers, and private credit firms—directly to the volatile fortunes of artificial intelligence enterprises, many of which have yet to demonstrate sustainable commercial profitability.

The FPC highlighted these developments in the minutes of its September 25 meeting, warning that the exponential growth in artificial intelligence-related debt issuance significantly broadens capital markets’ vulnerability to sector-specific shocks. Because these financial instruments intertwine traditional investment portfolios with high-risk technology ventures, a sudden correction or operational failure within the AI landscape could trigger liquidity crunches across the wider financial ecosystem. The committee emphasized the urgent necessity for proactive, timely risk management to navigate these deeply interconnected financial exposures.
Chronology of Regulatory and Financial Awakening
The realization that artificial intelligence poses macro-prudential risks represents a rapid evolution in central banking priorities. The timeline of this regulatory awakening highlights how quickly technology has outpaced traditional economic oversight:
- Late 2022 to 2023: The widespread public release of generative artificial intelligence models ignites a global commercial race. Technology firms, venture capitalists, and institutional investors pour hundreds of billions of dollars into compute infrastructure, data centers, and talent acquisition.
- Throughout 2024: Financial institutions begin integrating advanced machine learning models into algorithmic trading desks, risk management frameworks, and customer verification systems. Early warnings from cybersecurity experts highlight the escalating sophistication of AI-driven cyber threats targeting financial infrastructure.
- Early to Mid-2025: Incidents involving autonomous models exhibiting anomalous behaviors or bypassing safety guardrails draw intense scrutiny from international security researchers. Central banks begin preliminary internal studies assessing the operational resilience of core payment systems against algorithmic disruptions.
- June 2026: Financial stability committees begin tracking the immense capital expenditure boom, noting that billions of dollars are being funneled into hypothetical future returns, raising initial concerns regarding sustainable valuations and corporate indebtedness.
- September 2025 to September 2026: AI-related debt issuance surges to $450 billion globally. The Financial Policy Committee formally issues warnings regarding capital market exposure. Governor Andrew Bailey publishes his Insight essay, cementing the central bank’s official stance on the mandatory retention of intervention rights.
Industry Reactions and Economic Implications
The stance adopted by the Bank of England has elicited a complex spectrum of reactions from technology leaders, financial analysts, and market participants. Proponents of artificial intelligence innovation have historically resisted government oversight, arguing that heavy regulatory burdens stifle entrepreneurial dynamism and cede a strategic geopolitical advantage to foreign competitors. However, the sobering realization that foundational banking systems could be compromised by algorithmic instability has forced a pragmatic re-evaluation.
Financial analysts point out that central banks are mandated to preserve monetary and financial stability above all else. When a technological sector becomes large enough to absorb debt loads exceeding sovereign borrowing programs, it ceases to be a fringe market and becomes a systemic systemic pillar. Consequently, the Bank of England’s insistence on maintaining an "emergency brake" or right to intervene is viewed by institutional economists as a necessary prudential safeguard rather than an ideological attack on innovation.
Furthermore, the integration of AI within the financial sector creates a dual vulnerability. On one hand, financial institutions are deploying AI to optimize operations, detect fraud, and manage portfolios. On the other hand, malicious actors are leveraging the exact same frontier models to execute sophisticated, automated cyberattacks against banks and payment processors. This technological arms race has fundamentally altered the threat landscape. Daily card payments, interbank clearing houses, and high-frequency trading platforms now rely on defensive systems that must operate faster and more intelligently than the offensive tools deployed by adversaries.
Broader Economic and Geopolitical Outlook
As central banks across G7 economies grapple with the implications of the artificial intelligence revolution, the policy outlined by Andrew Bailey may well serve as a global benchmark. The challenge facing international regulators is finding a delicate equilibrium: fostering an environment where technological innovation can flourish while maintaining sufficient oversight to prevent catastrophic systemic failures.
The mounting pile of AI debt adds a distinctly precarious financial dimension to an already complex technological puzzle. Should investor sentiment shift or commercial monetization stall, the interconnected web connecting private credit funds, hedge funds, and major tech firms could experience severe liquidity shocks. By signaling well in advance that authorities retain the statutory and moral right to intervene, the Bank of England is attempting to establish clear boundaries before a crisis forces reactionary, panic-driven policymaking.
Ultimately, Bailey’s message serves as both an endorsement of technological potential and a stern warning regarding prudential limits. The future stability of the global financial system may well depend on how effectively economic authorities and technology developers can cooperate to ensure that autonomous systems remain transparent, supervised, and fundamentally subservient to human oversight.