As Lennar prepares to release its third-quarter financial results on Thursday morning, market watchers and investors find themselves navigating an increasingly complex housing landscape marked by persistent affordability headwinds and fluctuating mortgage rates. The upcoming earnings call is widely anticipated not only for its headline numbers but for management’s forward-looking guidance on gross margins, production pacing, and sales incentives. Following a significant 16% correction in its share price since the release of its second-quarter report, Lennar currently trades at a modest 1.05 times its tangible book value and approximately 0.88 times its stated book value. This compressed valuation suggests that public market investors are heavily discounting the homebuilder’s near-term margin recovery potential and longer-term return on equity (ROE) trajectory.
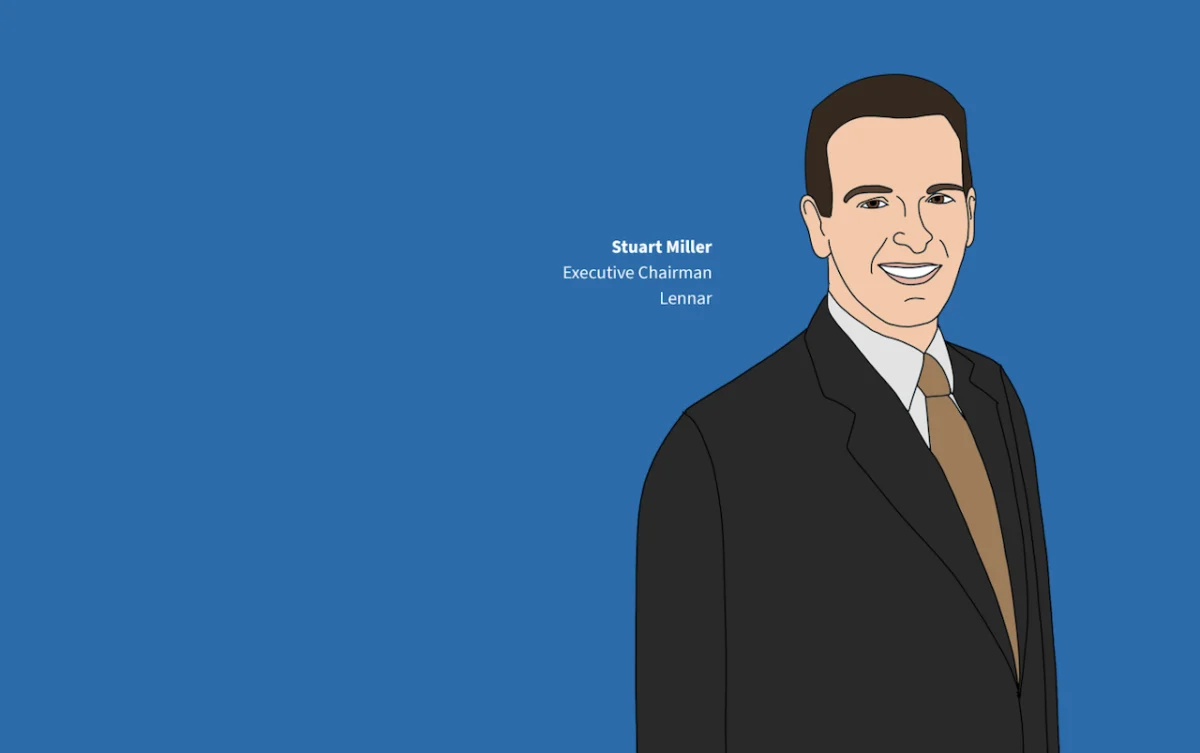
The core debate on Wall Street centers on whether Lennar can sustain the incremental margin improvements it reported earlier in the fiscal year or if macroeconomic pressures will force a tactical retreat. During the second-quarter earnings call, Executive Chairman and Co-CEO Stuart Miller offered a characteristically grounded assessment of the housing sector, expressing cautious optimism supported by a nascent recovery in gross margins. Specifically, Lennar posted a 120-basis-point sequential increase in gross margins from the first quarter to the second. However, with macroeconomic volatility persisting and borrowing costs remaining elevated, market expectations have cooled considerably, setting the stage for a critical corporate update.
The Operational Equation: Margins, Leverage, and Asset Turnover
To understand why Lennar’s valuation has compressed to near-tangible book value, financial analysts are closely examining the fundamental drivers of the company’s return on equity. In the capital-intensive homebuilding sector, a company’s ROE is typically a function of three primary levers: net profit margins, asset turnover, and financial leverage. For Lennar, however, two of these three levers have already been pushed close to their structural limits.
Through aggressive operational streamlining, the adoption of land-banking strategies, and a strict focus on supply chain management, Lennar has previously achieved record-low construction cycle times and optimized its asset turnover. Furthermore, management has maintained a disciplined approach to balance sheet management, meaning there is little appetite or necessity to significantly increase financial leverage to drive artificial growth. Consequently, Lennar’s ROE remains extraordinarily sensitive to fluctuations in its gross and net profit margins. When margins expand, profitability scales efficiently; conversely, any margin compression hits the bottom line directly, heavily influencing how equity research analysts model the stock’s intrinsic worth.
Because the current valuation implies that Lennar’s underlying assets are worth little more than their historical cost, the market is effectively pricing in a prolonged period of stagnant profitability. This bearish sentiment underscores the importance of Thursday’s call, where management is expected to provide definitive commentary on whether margin recovery can resume or if it will be stymied by shifting consumer dynamics.
The Incentive Puzzle and Consumer Affordability Pressures
At the heart of the margin debate are sales incentives. To stimulate demand in a high-rate environment, homebuilders have increasingly relied on financial concessions, ranging from direct price reductions to specialized mortgage rate buy-downs. For Lennar, the trajectory of these incentives over recent quarters illustrates the ongoing tug-of-war between maintaining sales volume and protecting gross margins.
During the final quarter of fiscal 2025, Lennar’s incentives represented approximately 14.5% of the total purchase price. This figure edged downward to 14.1% in the first quarter of the fiscal year and contracted further to 12.9% in the second quarter. This sequential decline in incentive dependency was a primary catalyst behind the 120-basis-point margin expansion that fueled Stuart Miller’s cautious optimism in June.
However, the broader macroeconomic environment has shifted uncomfortably since the conclusion of the second quarter. Mortgage rates have experienced renewed upward drift, putting additional pressure on prospective homebuyers already squeezed by years of rapid home price appreciation. In the current housing market, even minor shifts in borrowing costs have an outsized impact on consumer purchasing power. Industry rules of thumb suggest that every 10-basis-point movement in mortgage rates exerts the exact same psychological and financial pressure on monthly housing affordability as a 1% change in the home’s purchase price.
During the span of Lennar’s second quarter, benchmark mortgage rates drifted upward by approximately 30 basis points. Holding all other variables constant, that increase effectively required a 3% reduction in home purchase prices just to keep a standard buyer’s monthly mortgage payment unchanged. This mathematical reality creates a difficult operational dilemma for homebuilding executives: as affordability deteriorates, builders may find themselves forced to reverse the downward trend in incentives, sweetening deals with more aggressive rate buy-downs to maintain absorption rates and keep construction pipelines moving.
Investor Anxiety Over Land Banking and Production Pacing
Beyond immediate pricing strategies, institutional investors have raised structural questions regarding Lennar’s operational flexibility. One major point of contention involves the company’s heavy reliance on land banking—a strategy where third-party entities acquire and develop land parcels, subsequently selling them back to the builder via scheduled take-down agreements.
While land banking successfully keeps capital off the builder’s balance sheet and enhances return on assets during robust housing cycles, critics argue it can introduce rigid cost structures during sector downturns. Some market participants worry that contractual take-down schedules obligate Lennar to purchase land at predetermined intervals, giving the company less localized flexibility to abruptly slow down production and sales starts when local demand softens. Under this assumption, a rigid land pipeline forces builders to keep building homes, which in turn necessitates higher sales incentives to clear inventory, ultimately dealing a harsher blow to operating margins.
Management’s commentary regarding land-banking flexibility, therefore, will be heavily scrutinized on Thursday. Investors will be listening for reassurances that Lennar retains the contractual agility to adjust its starts program and moderate its land acquisition pace should the affordability crisis deepen in the second half of the year.
Broader Industry Implications and Competitor Watch
Lennar’s strategic positioning does not exist in a vacuum. The broader residential construction sector is currently engaged in a delicate balancing act, carefully weighing production volumes against pricing power. This dynamic was highlighted recently in strategic budget analyses of major competitors, such as D.R. Horton’s multi-year planning outlines, which signaled to the wider market how top-tier builders intend to handle pricing and absorption targets through 2027.
As production slows across the industry in response to affordability-impacted markets, every operational signal from a bellwether like Lennar serves as a vital benchmark for rival firms. Competitors will be tuning into Thursday morning’s conference call not only for financial metrics but for qualitative insights into how Lennar plans to manage fourth-quarter absorption targets. Specifically, industry observers want to know whether Lennar will choose to protect margin percentages by intentionally throttling volume, or if it will prioritize market share and steady cash flow by leaning more heavily into rate buy-downs and marketing tweaks.
Ultimately, Lennar’s upcoming third-quarter earnings report represents a crucial test of credibility for the homebuilding sector at large. By addressing investor anxieties head-on—particularly regarding land commitments, incentive trends, and margin guidance—management has an opportunity to reset market expectations. Whether the current valuation near tangible book value proves to be an overly pessimistic mispricing or a realistic reflection of structural headwinds will depend largely on the clarity and confidence Lennar’s leadership projects when they address Wall Street this week.