Navigating the labyrinth of real estate transactions often introduces a variety of hurdles, none of which carry quite as much financial weight for buyers, sellers, and lenders alike as the home appraisal. Whether a real estate deal is taking place in a bustling metropolitan area like Tampa, Florida, or a growing suburban community such as Dumfries, Virginia, the home appraisal serves as a critical checkpoint in the mortgage financing pipeline. Far more than a simple walk-through, a professional appraisal establishes an independent, objective opinion of a property’s fair market value, protecting both the lending institution and the borrower from overleveraging.
To demystify this essential component of the housing market, industry experts emphasize the need to understand every phase of the appraisal workflow—from the initial on-site physical inspection to the final comparable market analysis and report generation. Understanding how appraisers calculate market value, what structural elements carry the most weight, and how specialized loans enforce stricter evaluation criteria can help market participants better navigate the complexities of property transactions.
Defining the Role of a Home Appraisal in Modern Real Estate
At its core, a home appraisal is a formal evaluation of a property’s current market value conducted by a licensed or certified real estate appraiser. When a prospective buyer utilizes a mortgage loan to finance a real estate purchase, the lending institution invariably mandates an independent appraisal. The primary objective of this requirement is to ensure that the property provides adequate collateral to secure the loan amount. Should a borrower default on the mortgage, the lender must be confident that the market value of the home can cover the outstanding balance of the debt through a future liquidation.
Beyond traditional purchase transactions, appraisals are frequently required during mortgage refinancing processes, home equity line of credit (HELOC) applications, and legal proceedings such as estate planning or divorces.
It is a common misconception among consumers that a home appraisal is interchangeable with a home inspection. While the two processes often occur around the same time during a real estate transaction, their underlying objectives differ significantly. A home inspection is performed to diagnose the physical condition of a property, identify potential defects, and alert the buyer to necessary repairs or safety hazards. Conversely, a home appraisal is primarily concerned with establishing economic value. While deferred maintenance and visible property damage certainly factor into an appraiser’s final valuation, the principal focus remains on analyzing location, structural characteristics, square footage, and recent sales data of comparable properties.
Chronology and Workflow of the Appraisal Process
The home appraisal lifecycle follows a structured, methodical chronology that blends on-site observation with rigorous off-site market research. While the exact duration of an appraisal assignment can vary based on property size, architectural uniqueness, and market volume, the process generally unfolds in five distinct phases.
Step One: The On-Site Property Visit
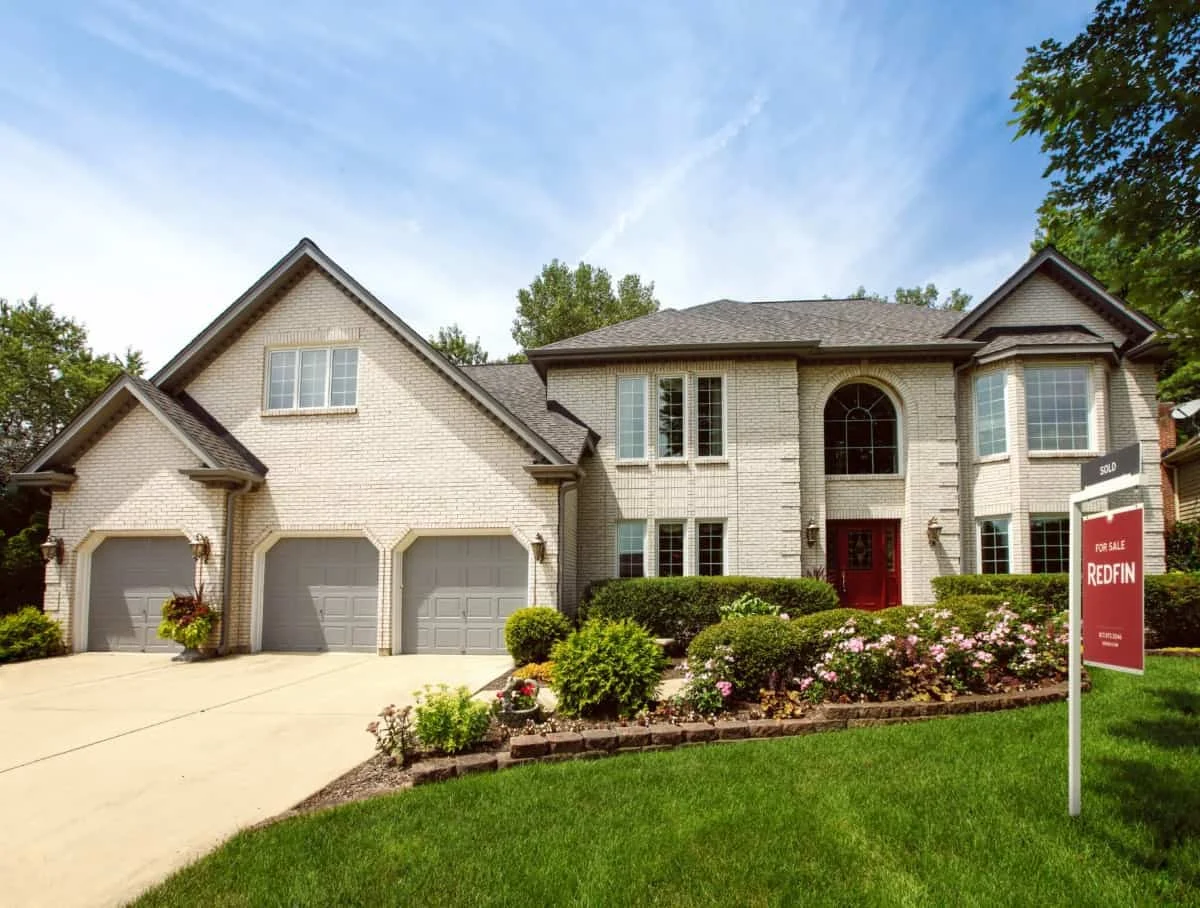
The appraisal process typically commences with an interior and exterior inspection of the subject property. The licensed appraiser visits the site to observe, document, and measure the physical dimensions of the home and the surrounding lot. During this visit, the appraiser captures photographs of key living areas, the exterior facade, and any permanent property improvements. The duration of this visit varies depending on the scale of the property; a sprawling, custom-built residence will naturally require significantly more data collection time than a standard suburban single-family home or a condominium unit.
Step Two: Comprehensive Property Evaluation
Once inside and around the property, the appraiser systematically evaluates the home’s overall condition, functional utility, layout, and quality of construction. Key structural components—such as the roof, foundation, HVAC systems, plumbing, and electrical infrastructure—are meticulously noted. The appraiser also tallies the number of legal bedrooms and bathrooms, finished square footage, and the presence of amenities like garages or additions.
According to Corey Ferguson of Mercor Realis, a residential appraisal firm, permanent and functional structural improvements carry the most weight in the valuation formula. “Permanent, functional improvements carry the most weight—updated kitchens and baths, added square footage, finished basements, and newer major systems like the roof, furnace, and electrical,” Ferguson explains.
Conversely, Ferguson cautions that homeowners frequently overestimate the financial return on luxury or cosmetic upgrades. Features such as in-ground swimming pools, ultra-luxury interior finishes that far exceed neighborhood norms, aesthetic paint choices, and elaborate landscaping help a property show and sell quickly on the open market, but they rarely translate to a dollar-for-dollar increase in the appraiser’s final valuation number.
Step Three: Researching Comparable Market Sales
Following the physical inspection, the appraiser transitions to off-site research, compiling a dataset of recent comparable sales—commonly referred to in the industry as “comps.” These are properties located in close proximity to the subject home that have recently sold and share similar architectural, dimensional, and qualitative traits.
Because no two real estate parcels are entirely identical, the appraiser must carefully adjust the sales prices of these comparable properties to account for differences in square footage, lot size, age, condition, and amenities.
Robert Surns, a residential appraiser at Lakeshore Appraisal, highlights the critical nature of this analytical step. “Recent comparable sales provide evidence of what buyers are currently paying for similar homes,” Surns notes. “Appraisers analyze these sales to align the subject with current market activity and support a credible opinion of value.” Because historical asking prices or theoretical valuation estimates do not reflect actual consumer behavior, verified recent sales serve as the ultimate benchmark for what the current market will bear.

Step Four: Data Synthesis and Valuation Modeling
In the fourth phase, the appraiser integrates the empirical data gathered during the on-site visit with the findings of the comparative market analysis. Rather than evaluating individual features in a vacuum, the appraiser assesses the property holistically. Factors such as neighborhood desirability, local school districts, proximity to commercial hubs, and macroeconomic housing trends are weighed against the physical state of the home.
This synthesis explains why a home’s agreed-upon purchase price, a seller’s emotional attachment, or the total capital expenditure a homeowner poured into recent renovations do not automatically dictate the final appraised value. If the broader market data does not support the price point, the appraisal report will reflect the independent market reality.
Step Five: Final Report Delivery
The culmination of the appraisal process is the delivery of a comprehensive appraisal report. This standardized documentation package details the property characteristics, summarizes the chosen comparable sales, outlines relevant local housing market conditions, and explicitly states the appraiser’s final, defended opinion of market value. For mortgage transactions, this report is transmitted directly to the underwriting department of the lending institution.
Differentiating Appraisal Standards Across Loan Programs
While conventional mortgages adhere to standard appraisal guidelines, government-backed loan programs enforce additional property standards that can directly impact whether a transaction proceeds smoothly. Buyers utilizing Federal Housing Administration (FHA) loans or Department of Veterans Affairs (VA) loans must navigate properties that satisfy strict minimum property requirements (MPRs).
FHA appraisals incorporate stringent evaluations focused on property health, safety, and structural integrity. If an FHA appraiser identifies conditions such as severely deteriorating lead-based paint, active roof leaks, structural foundation shifting, exposed electrical wiring, or substandard moisture barriers, these deficiencies must typically be corrected and reinspected before the mortgage can receive final underwriting approval.
Similarly, VA home loan purchases mandate that properties meet baseline standards of being safe, structurally sound, and sanitary. The appraiser must verify that the home features adequate and continuous heating, operational utilities, a sound roof, and freedom from environmental hazards. If a property fails to meet these federally mandated benchmarks, the parties involved must negotiate who will fund the necessary remediation efforts to keep the real estate transaction alive.
Implications and Outcomes of the Completed Appraisal
The finalization of the appraisal report triggers the next phase of the mortgage underwriting workflow. Three primary scenarios typically emerge upon delivery of the report:
-
The Appraised Value Matches or Exceeds the Purchase Price: This is the ideal outcome for all parties involved. With the collateral verified, the mortgage underwriting process continues uninterrupted toward a scheduled closing date, provided the borrower satisfies all remaining financial prerequisites.
-
The Appraisal Comes in Low: If the appraised value falls short of the agreed-upon purchase price, a financing gap is created. Because lenders base their loan-to-value (LTV) ratios strictly on the appraised value rather than the contract price, the buyer must make up the financial difference out of pocket, the seller must agree to lower the purchase price to match the appraisal, or the parties must negotiate a compromise. Failure to bridge this gap can result in the termination of the purchase contract under standard appraisal contingency clauses.
-
The Appraisal Uncovers Mandatory Repair Conditions: Common in FHA and VA transactions, this outcome halts the transaction until specific safety or structural repairs are completed and verified by a subsequent re-inspection.
Broader Market Impact and Economic Significance
The home appraisal process remains a vital stabilizing force within the broader real estate economy. By injecting objective, data-driven methodology into property transactions, appraisals prevent speculative bubbles, protect financial institutions from systemic risk, and ensure that buyers do not drastically overpay for housing assets.
While navigating a low appraisal or preparing a home for an inspector’s visit can induce stress for both buyers and sellers, a thorough understanding of the underlying mechanics removes much of the uncertainty. By recognizing what professional appraisers look for—focusing on permanent structural functionality and verifiable comparable market data—homeowners and market participants can better prepare for one of the most technical yet essential milestones in the real estate journey.