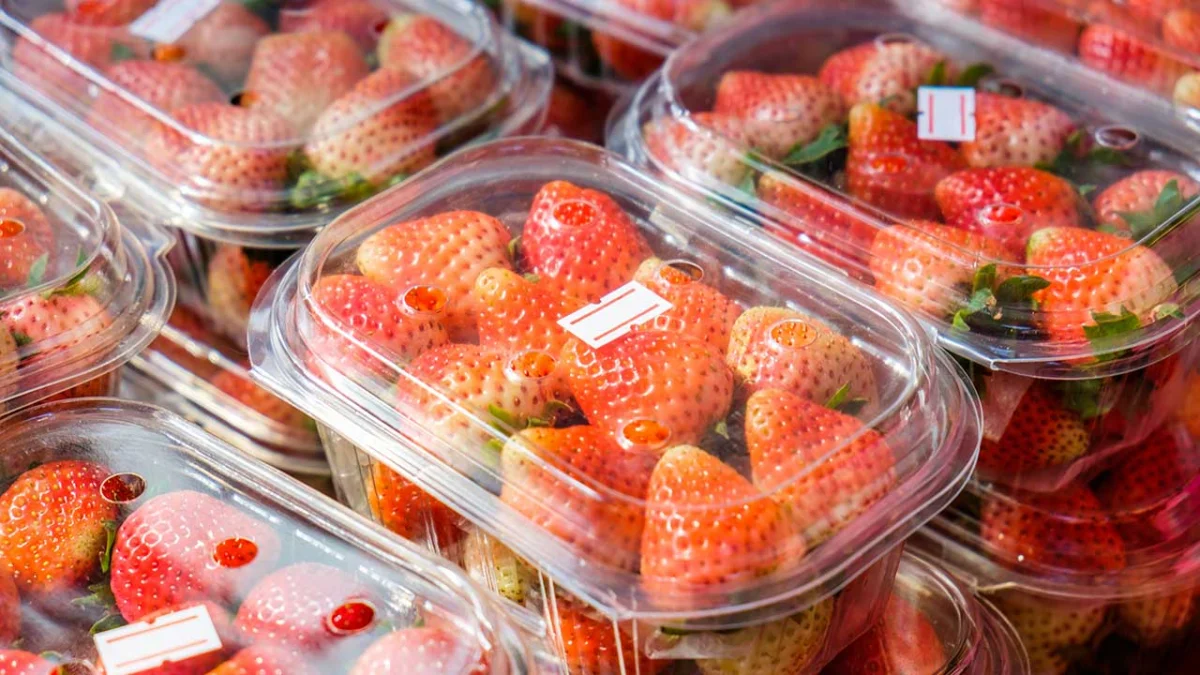
The grocery store aisles of the near future will look remarkably different for American consumers, driven by sweeping regulatory changes originating on the West Coast. By 2028, shoppers will likely notice a distinct absence of traditional packaging mainstays: fruits packaged in rigid plastic clamshells will give way to ventilated cardboard cartons, takeout meals will arrive in molded fiber bowls, and microwaveable dinners will sit securely in clear or light-colored plastic trays rather than opaque black containers. These visible modifications across supermarket shelves are the direct result of California’s landmark packaging legislation, Senate Bill 54 (SB 54), whose finalized regulations officially took effect in May 2026.
Although enacted at the state level, the operational reach of SB 54 extends far beyond California’s borders. Major multinational consumer goods manufacturers and national retail brands are actively reformulating their packaging pipelines for a unified nationwide market, rather than bearing the steep logistical and financial costs of maintaining separate manufacturing streams for different states. This standardization effect has transformed California’s regulatory framework into a de facto national standard. However, the implementation of the law has not proceeded without friction. Shortly after the final regulations were codified, prominent environmental advocacy organizations—including Oceana, the Natural Resources Defense Council (NRDC), and the Californians Against Waste Foundation—filed a joint lawsuit in the San Francisco Superior Court. The plaintiffs argue that the finalized rules incorporate broad exemptions for major categories of plastic packaging, permit producers to claim indefinite extensions, and fail to establish sufficient safeguards against unverified technologies that the original legislation intended to curb.
The Scope of the Plastic Waste Crisis
To understand the immense pressure driving these regulatory shifts, policymakers and environmental economists point to the sheer volume of municipal solid waste generated globally and domestically over the past several decades. For generations, synthetic plastics became the foundational default for modern commercial packaging due to their low production costs, chemical durability, and featherlight physical properties. Yet, this exponential growth in production has triggered a severe global waste management crisis.
According to historical data published by the U.S. Environmental Protection Agency (EPA), plastic waste accounted for a negligible 0.4% of the total municipal solid waste stream in the United States in 1960. By 2018, that figure had skyrocketed to 12.2%, a staggering surge that underscored the unsustainability of linear consumption models. Packaging materials constitute the vast majority of this problem because they are designed for immediate, single-use consumption before being discarded. Industry analyses indicate that approximately 36% of all manufactured plastic is utilized exclusively for packaging applications, and a striking 85% of that discarded material ultimately terminates in landfills or escapes into natural ecosystems.
In direct response to these escalating environmental pressures, California passed SB 54 to overhaul the state’s waste infrastructure. The statute establishes two core mandates: a legally binding requirement to cut single-use plastic packaging by 25% by 2032, and a mandate ensuring that all single-use packaging sold or distributed within the state is either genuinely recyclable or commercially compostable.
The economic engine driving these structural changes is the principle of Extended Producer Responsibility (EPR). Under an EPR framework, the financial and operational burden of end-of-life waste management is shifted away from municipal governments and local taxpayers and placed directly onto the corporations that manufacture and distribute the packaging. This creates an immediate, enforceable financial incentive for companies to reduce raw material usage, design packaging for seamless recyclability, and eliminate problematic or toxic polymers from their supply chains.
Vulnerable Packaging Materials and Industry Phase-Outs
SB 54 establishes stringent thresholds for recyclability, source reduction, and compostability, placing immediate pressure on materials historically categorized as difficult or impossible to recycle. Expanded polystyrene (EPS)—commonly known by the brand name Styrofoam—has already faced aggressive restrictions in California, with food service applications restricted following the industry’s failure to achieve a mandated 25% recycling rate. Other problematic material categories are undergoing rapid redesign, substitution, or outright phase-down as producers race toward intermediate and final compliance deadlines.
Expanded Polystyrene and Health Risks
EPS is ubiquitous in modern commerce, appearing in single-use coffee cups, takeout clamshell boxes, rigid coolers, and fragile protective shipping blocks. However, because EPS is composed predominantly of air, it presents severe logistical and financial inefficiencies during transport. Furthermore, the material is brittle, breaking down easily into microscopic particles that contaminate clean recycling streams and ruin bales of otherwise valuable materials. Beyond its persistence in the environment, scientific literature has increasingly linked chronic exposure to styrene—the foundational chemical building block of polystyrene—to elevated risks of leukemia, lymphoma, and other severe health complications. Consequently, manufacturers are aggressively substituting EPS with molded fiber containers, corrugated cardboard, and heavy-duty paper-based alternatives.
Black and Dark-Colored Plastics
Another primary target for redesign is black and dark-colored plastic food packaging, frequently utilized for microwave-safe meal trays, sushi containers, and fresh produce bases. The environmental failure of these items lies entirely within their optical properties. Modern materials recovery facilities (MRFs) rely heavily on near-infrared (NIR) optical sorting technology to rapidly categorize and separate different polymer types on high-speed conveyor belts. The carbon black pigments universally used to dye these trays absorb near-infrared light rather than reflecting it back to the sensor. As a result, optical sorters register the dark packaging as a void, automatically ejecting it into the landfill waste stream rather than capturing it for recycling. Within the coming years, transparent or light-colored polyethylene terephthalate (PET) containers, aluminum trays, and fiber-based alternatives are expected to completely replace black plastic across retail shelves.
Polyvinyl Chloride (PVC) and Oxo-Degradable Plastics
Rigid polyvinyl chloride (PVC)—often referred to as vinyl—frequently forms the transparent clamshells used for bakery items, berries, and salads, as well as blister packs for consumer electronics and hardware. Under SB 54, PVC faces severe regulatory penalties because it acts as a catastrophic contaminant in the PET recycling stream; even microscopic traces of PVC mixed into a bale of recycled PET can ruin the entire batch. Moreover, the plasticizers required to render PVC flexible often contain phthalates, which are endocrine disruptors linked to chronic metabolic conditions and reproductive health issues.
Simultaneously, the law takes direct aim at oxo-degradable plastics. These conventional polymers, such as polyethylene, are manufactured with chemical additives designed to accelerate physical fragmentation when exposed to ultraviolet light or ambient heat. Often marketed under vague "eco-friendly" labels, oxo-degradables do not truly biodegrade at a molecular level; instead, they shatter into persistent microplastics that accelerate ecological contamination in soil and marine environments. SB 54’s rigorous standards effectively ban these deceptive marketing practices, demanding verified proof of biological breakdown.
Chronological Roadmap: The SB 54 Compliance Timeline
The transformation of the commercial packaging sector is governed by a multiyear statutory roadmap, giving producers structured deadlines to adapt their supply chains:
- May 1, 2026: Permanent regulatory frameworks take effect upon filing. Producers are given a strict statutory window to register with the designated Producer Responsibility Organization (the Circular Action Alliance), register independently with CalRecycle, or apply for verified small-producer exemptions.
- January 1, 2027: Full program implementation initiates. Covered single-use plastic packaging must demonstrate a 10% volume reduction compared to the established 2023 baseline. Producers operating outside an approved compliance plan are legally prohibited from selling covered materials in California, and mitigation fund payments commence.
- January 1, 2028: The regulatory threshold mandates that 30% of covered single-use plastic packaging and food service ware must be actively recycled, moving beyond theoretical recyclability to verifiable processing rates.
- January 1, 2030: The statutory recycling rate target increases to 40%, while mandatory source reduction scales up to 20%. Refillable systems, concentrated pods, and returnable packaging models transition from pilot programs to mainstream commercial offerings.
- January 1, 2032: The final tier of statutory targets takes full effect. Producers must achieve a 25% source reduction, a 65% recycling and composting rate, and 100% compliance ensuring all covered packaging is strictly recyclable or compostable.
Broader National Implications and Federal Inaction
While California’s proactive legislative stance is unique in its scale, it does not exist in a vacuum. A growing cohort of U.S. states are enacting independent Extended Producer Responsibility laws to address municipal waste burdens. Oregon’s Recycling Modernization Act similarly requires manufacturers to fund municipal recycling upgrades, while states such as Colorado, Maine, Vermont, and New York have advanced or enacted comparable legislative frameworks.
For national consumer brands, navigating a fragmented, state-by-state patchwork of conflicting packaging rules presents an extraordinary financial and logistical hurdle. To maintain operational efficiency, major corporations frequently choose to design a single, globally compliant package that satisfies the most rigorous regulatory market in the country—namely, California—and distribute that uniform product nationwide. This economic reality amplifies California’s legislative reach, effectively establishing a de facto national standard. This state-led momentum highlights a persistent vacuum at the federal level, where comprehensive packaging EPR legislation has stalled, leaving regional coalitions—such as an emerging "West Coast standard" among California, Oregon, and Washington—to drive national environmental policy by default.
Market Realities and Corporate Accountability
As corporations race to comply with SB 54, consumer advocates and regulatory agencies remain vigilant against corporate greenwashing—the practice of utilizing misleading environmental marketing to obscure underlying ecological impacts. Material substitutions that replace one problematic polymer with another unverified bioplastic can introduce unforeseen chemical hazards, such as the presence of toxic manufacturing additives in compostable packaging.
To ensure genuine accountability, market observers emphasize the importance of verified third-party certifications, such as the Biodegradable Products Institute (BPI) logo for commercial compostability and standardized labeling systems like How2Recycle. Ultimately, the successful execution of SB 54 will depend on close coordination between state regulators, municipal waste management authorities, and conscious consumers. By shifting the financial responsibility of waste management back to the producers, California’s landmark law has permanently altered the trajectory of American commerce, setting a high bar for environmental stewardship and circular economic design.