The national political landscape experienced significant volatility during the most recent election cycle, yet the predicted blue tsunami failed to crest in Florida. Instead, the Sunshine State reaffirmed its conservative trajectory, delivering decisive victories for Republican candidates across statewide offices. Beyond the electoral outcomes, Florida voters ushered in a seismic shift in public policy by passing Amendment 3, a measure that mandates a massive reduction in property tax bills. While proponents celebrate the move as essential relief for homeowners grappling with persistent inflation, the amendment has triggered an intense debate among economists, law enforcement officials, and local government leaders regarding the long-term viability of essential public services.
The Mechanics of Amendment 3
At the heart of the approved measure is a significant expansion of the homestead exemption, a mechanism that shields a portion of a primary residence’s assessed value from property taxation. Under the current structure, the exemption stands at $51,400. Amendment 3 introduces a tiered expansion strategy: the exemption will climb to $150,000 by 2027, followed by a further increase to $250,000 in 2028.
In addition to the homestead expansion, the amendment imposes a more stringent cap on annual assessments for rental and commercial properties, reducing the allowable hike from 10% to 5%. While the measure explicitly excludes school-related property taxes—an attempt to insulate the state’s education funding—it simultaneously establishes a legislative framework that could eventually lead to the total abolition of non-school property taxes. This structural change represents one of the most aggressive tax-cutting measures in Florida’s recent history, effectively altering the revenue-gathering capacity of municipalities across all 67 counties.
Financial Projections and Revenue Shortfalls
The economic implications of the amendment are staggering. According to state economic analysts, the fiscal impact will be felt almost immediately upon implementation. Initial estimates suggest that local governments stand to lose approximately $5 billion in the first year alone. Once the amendment is fully phased in by 2028, that annual deficit is projected to balloon to nearly $12 billion.
Critics of the amendment, including former Republican state senator and current president of the Florida Policy Project, Jeff Brandes, argue that these losses are unsustainable. In a recent analysis, Brandes highlighted the disparity in fiscal resilience between large, tourism-heavy cities and smaller, inland rural communities. While a city like Miami may be able to offset some losses through increased hotel taxes or tourist-related fees, many rural municipalities lack the infrastructure or economic base to pivot to alternative revenue streams.
Research from the Florida League of Cities bolsters this concern, revealing that in 108 of the state’s 411 cities, at least 90% of homestead values will no longer be taxable under the new $250,000 exemption threshold. In 33 counties, seven out of every ten homes will fall entirely below the taxable limit.
A Conflict Over Essential Services
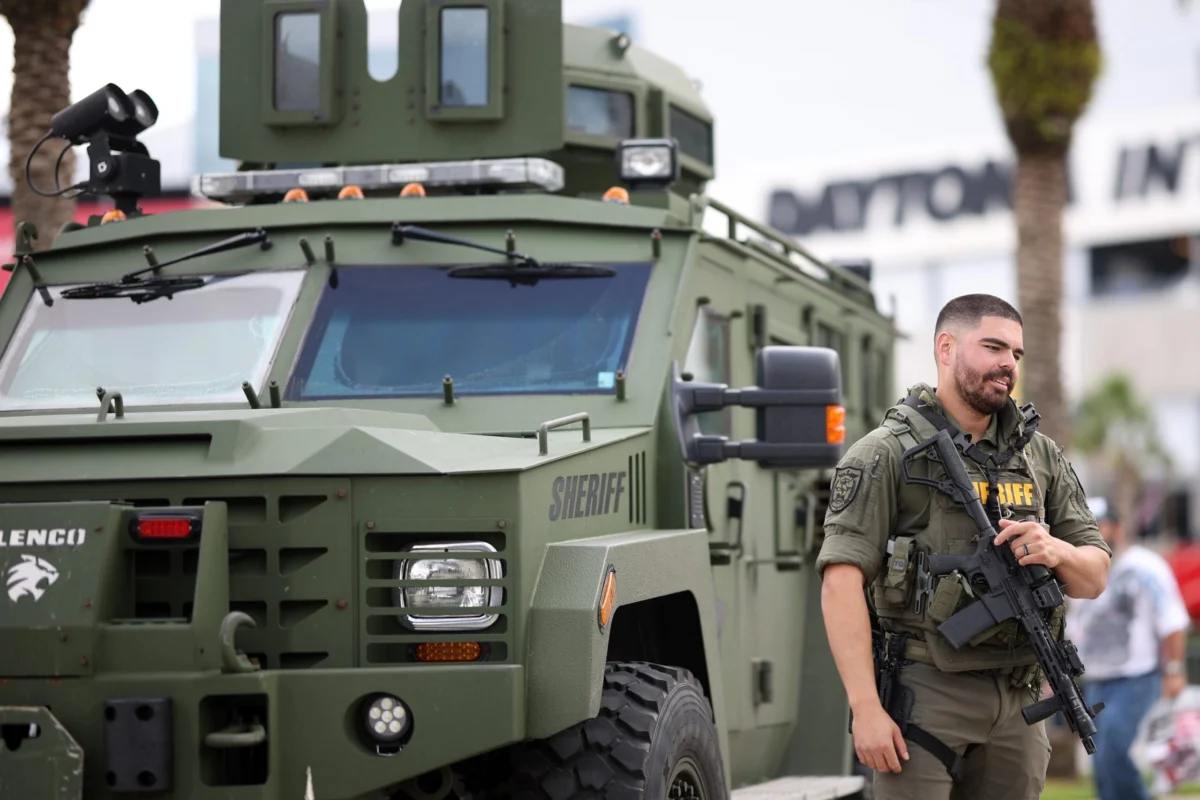
The most contentious aspect of the amendment lies in the funding of public safety. Although the measure stipulates that remaining tax revenue must be directed toward public safety and essential local services, it fails to mandate that police, fire, or emergency medical services (EMS) receive a specific, guaranteed level of funding.
Law enforcement and fire safety officials have been vocal in their opposition, warning that the lack of protective mandates will force deep budget cuts. Pinellas County Sheriff Bob Gualtieri has been particularly outspoken, estimating that his jurisdiction alone faces a potential $180 million loss in the first year. Because the sheriff’s office budget is heavily weighted toward personnel—covering salaries for deputies, dispatchers, and support staff—Gualtieri has warned that layoffs are inevitable.
"There is no doubt—zero—that there has to be position cuts," Gualtieri stated in recent briefings. The potential reduction in force could affect community policing, marine patrols, and specialized K-9 units. Furthermore, the county’s emergency medical services fund is projected to suffer a $20 million reduction, raising alarms about increased response times for life-saving care.
The Insurance Conundrum
An often-overlooked consequence of the tax cut is the potential for increased costs in other sectors, specifically property insurance. The Insurance Services Office (ISO), a private firm that evaluates local fire protection capabilities, provides ratings that insurance companies use to set premiums. These ratings are heavily dependent on the funding and equipment available to local fire departments.
Industry experts have warned that if the budget cuts necessitated by Amendment 3 result in downgraded fire protection services—such as longer response times or less modern equipment—communities could see their ISO ratings drop. A lower rating typically correlates with higher insurance premiums for homeowners, effectively negating the financial savings gained from the property tax cut. This creates a "hidden" tax, where the money saved on tax bills is simply redirected to private insurers to cover the higher risk associated with degraded public safety infrastructure.
Perspectives from Leadership and Economic Analysts
The political divide surrounding the amendment remains sharp. Outgoing Governor Ron DeSantis has consistently backed the measure, framing the warnings of local officials as "fearmongering." The Governor’s office has suggested that the state could step in with grants to offset any significant budget shortfalls, ensuring that essential services remain operational.
However, economists remain skeptical of this approach. Abigail Hall and Aaron Wood, writing for The Conversation, noted that funding for police and fire services is traditionally the responsibility of local governments and constitutes the largest line item in most municipal budgets. They argue that state grants are inherently unstable and cannot replace the consistent, reliable revenue that property taxes once provided.
"The elimination of a substantial portion of the property tax base does not eliminate the cost of local government services," analysts at the Tax Foundation noted in a pre-election report. "Amendment 3 would create highly distortive tax shifts, change who pays, and change how those costs are distributed. The result would be economically harmful both to Florida communities and the state overall."
A Timeline of Implementation and Future Uncertainty
The road ahead for Florida’s municipalities is characterized by uncertainty. With the election decided and the amendment passed, the focus shifts to the legislative process. It is widely expected that the Florida Legislature will need to convene a special session to clarify the implementation details and attempt to bridge the gap between the promised tax relief and the preservation of municipal functionality.
- Pre-Election Phase: Debate intensified as the Florida League of Cities and local sheriffs issued warnings regarding the potential for "rural dark ages," where decreased revenue leads to a cycle of disinvestment, lower service levels, and further economic decline.
- Election Day: Voters approved the measure, signaling a preference for immediate tax relief over concerns regarding long-term municipal solvency.
- Post-Election (Current Status): Local governments are beginning the process of revising their long-term fiscal plans. Discussions regarding potential fee increases—such as utility surcharges or new municipal assessments—are already surfacing as towns seek to mitigate the incoming $5 billion revenue shock.
- 2027–2028: The full implementation of the tax exemptions will serve as the ultimate test of the amendment’s economic theory.
Broader Economic Implications
Florida’s tax structure has historically been unique, relying heavily on property taxes rather than a state income tax to fund local services. This structure has traditionally provided a stable revenue floor even during economic downturns. By fundamentally restructuring this system, Amendment 3 introduces a new variable into the state’s fiscal policy.
Critics argue that by thinning the tax base, the state is effectively restricting its own ability to respond to future crises. If the state is forced to rely on sales taxes and fees to fill the void left by property taxes, the tax burden may shift toward the most economically vulnerable citizens, who tend to spend a higher proportion of their income on taxable goods.
As the state transitions into this new fiscal reality, the outcome will likely serve as a case study for other states considering similar tax-cutting initiatives. The central question remains: can Florida balance the immediate political mandate for lower property taxes with the long-term necessity of maintaining safe, functional, and well-funded public institutions? For now, the answer remains a point of intense contention, with the "rural dark ages" warned of by critics serving as the primary cautionary tale against the potential for a cascading decline in local service quality.
The coming months will be critical as municipal leaders, the state legislature, and taxpayers navigate the complex transition. Whether the predicted fiscal collapse is mitigated by state intervention or whether it manifests in reduced services, the passage of Amendment 3 marks a definitive, irreversible turn in the governance of Florida’s local communities.