The current landscape of the UK fuel market is defined by a confluence of geopolitical instability and structural supply deficits, leading to unprecedented pricing volatility. As of September 2026, the cost of diesel has reached levels that threaten to destabilize household budgets and inflate the cost of goods across the supply chain. With average prices hovering at approximately 196p per litre, compared to 172p for petrol, the disparity highlights a growing vulnerability in the nation’s energy security.
A Chronology of the 2026 Fuel Crisis
The escalation of fuel prices throughout 2026 was not an isolated event but the result of a series of compounding geopolitical shocks. The timeline began with the intensification of conflict in the Middle East, specifically regarding tensions in Iran and the subsequent blockade of the Strait of Hormuz. This maritime choke point, which facilitates a significant portion of the world’s oil transit, saw immediate volatility in global crude benchmarks.
By August 2026, global oil prices surged to an average of $91 per barrel, marking a $7 increase from the July baseline. However, the situation deteriorated rapidly as September witnessed a sharp spike, with prices reaching $108 per barrel. This volatility was exacerbated by the continued impact of the war in Ukraine and the critical closure of Saudi Arabia’s East-West pipeline, which restricted the flow of refined products to Western markets.
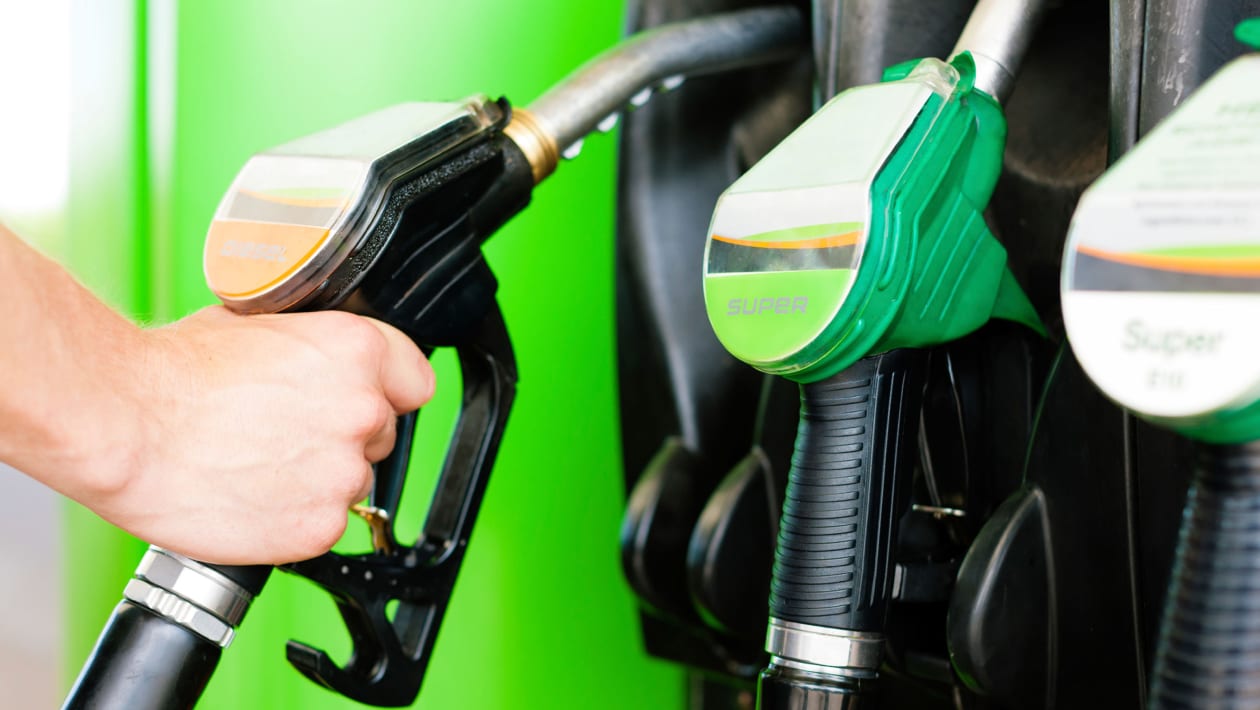
For the UK, the timing of these global disruptions proved particularly damaging, as the domestic market was already grappling with a transition away from diesel-powered vehicles, leaving the existing fleet of 11 million diesel passenger cars—representing 30% of the total UK car population—highly exposed to these price fluctuations.
Analyzing the Supply Deficit: The EIA Data
The primary driver of the current price surge is the unprecedented depletion of distillate fuel oil reserves. According to data provided by the US Energy Information Administration (EIA), the total US diesel inventory has been whittled down to 107.9 million barrels. This figure represents the lowest seasonal inventory level recorded since the EIA began tracking this metric in 1982.
The forecast for the remainder of 2026 and into 2027 remains somber. The EIA projects that US distillate fuel oil reserves will likely remain below the 100-million-barrel threshold for an extended period, failing to recover to the five-year average. Because the United States remains a key supplier to the global market, this structural deficit creates an indirect but inescapable upward pressure on the price of diesel at British pumps.
The mechanics of this price transmission are straightforward: as global supply becomes inelastic, the "crack spread"—the difference between the price of crude oil and the price of refined petroleum products—widens. Refiners are struggling to balance the demand for heating oil as winter approaches with the steady, non-negotiable demand for road diesel.
The Declining Diesel Market: A Structural Shift
The UK automotive market has undergone a radical transformation over the past decade. In 2015 and 2016, diesel vehicles accounted for nearly 48% of all new car registrations. By August 2026, that figure had plummeted to a mere 4.8%. This shift, driven by stricter emissions regulations and the rise of electric vehicle (EV) technology, has fundamentally altered the vehicle landscape.
Research conducted by industry analysts in 2025 indicated that the diversity of diesel options available to consumers had been drastically reduced. In 2015, manufacturers offered approximately 240 different models with diesel engine options; by 2025, this number had fallen to just 91, and current data suggests this decline has continued throughout 2026.
Despite this decline in the passenger vehicle sector, diesel remains the essential fuel for heavy-duty transport. The reliance on diesel-powered vans and HGVs for the movement of goods means that the transport sector cannot easily pivot to alternative fuels in the short term. Consequently, the rising cost of diesel acts as a tax on the entire economy, with transportation firms forced to pass increased overheads onto the end consumer, further fueling general inflation.
Implications for the Economy and Consumers
The economic implications of prolonged high diesel prices extend far beyond the forecourt. For the individual motorist, the cost of commuting has become a significant portion of monthly expenditure. For the logistics sector, the margin compression caused by fuel costs is severe.
Economists have noted that because diesel is the primary energy source for the nation’s supply chain, sustained prices near £2 per litre represent a systemic risk to the UK’s inflation target. Unlike petrol, which is largely driven by private consumer demand, the price of diesel is tied to industrial output. When diesel prices rise, the cost of transporting food, construction materials, and retail goods rises in tandem.
"We are seeing a decoupling of fuel prices from general energy trends," says one market analyst. "While crude oil production is expected to increase from 13.8 million barrels per day in 2026 to 14.3 million in 2027, this increased supply may not be sufficient to offset the geopolitical risks and the structural lack of refining capacity for diesel specifically."
The Path Toward 2027: A Recovery or Continued Strain?
Looking ahead, the EIA’s projection of increased US crude production provides a glimmer of hope, suggesting that the supply chain may find some relief by mid-2027. However, this recovery is contingent upon several factors that remain outside the control of the UK government or domestic energy providers.
Firstly, the resolution of the blockade in the Strait of Hormuz is paramount to stabilizing global maritime energy routes. Secondly, the geopolitical status of the East-West pipeline in Saudi Arabia remains a bottleneck that prevents the efficient distribution of oil to global markets. Finally, the resilience of the global economy will dictate how much further the market can absorb these high energy costs before demand destruction occurs.
For the average UK driver, the immediate future is characterized by caution. With no clear respite in sight, households and businesses are being encouraged to optimize fuel efficiency and, where possible, accelerate their transition to lower-emission alternatives. Yet, for the millions of diesel owners, the current reality remains one of significant financial strain, with the "pain at the pump" expected to persist well into the first half of 2027.
Industry Reaction and Policy Outlook
While no official government intervention has been announced to specifically cap diesel prices, industry stakeholders are increasingly calling for a review of fuel duty and a more strategic approach to energy reserves. The RAC and other motoring organizations have emphasized that the current price gap between petrol and diesel is unsustainable for the logistics industry and threatens the competitiveness of UK businesses.
As the industry prepares for the Paris Motor Show 2026 and other key automotive events, the focus is clearly shifting toward electrification. However, for the millions of HGVs currently on the road, the transition to alternative power remains a long-term goal rather than an immediate solution. The energy sector, therefore, faces a difficult winter, as the global market attempts to recalibrate its inventory levels in a climate of high geopolitical tension.
The current situation serves as a stark reminder of the global nature of energy markets and the fragility of supply chains. Until global refining capacity catches up with demand—and until geopolitical tensions in the Middle East and Eastern Europe reach a state of relative equilibrium—British motorists will likely continue to face the brunt of these historic price levels. The transition period between now and 2027 will require both consumers and industry to navigate a landscape where volatility is the only constant.