European consumers looking to make the switch to electric mobility may soon face a substantial, unintended financial hurdle as policymakers accelerate efforts to localize the electric vehicle (EV) supply chain. While the European Union’s push to mandate locally produced batteries aims to bolster regional employment and decrease reliance on Chinese manufacturing, new analysis suggests that the transition could impose a significant price premium on the very vehicles intended to spearhead the green revolution. A September 22 policy brief from the Brussels-based think tank Bruegel highlights the delicate balance between industrial sovereignty and consumer affordability, warning that the financial burden of protecting established European manufacturers may ultimately fall squarely on the shoulders of the car buyer.
The Math Behind the Battery Premium
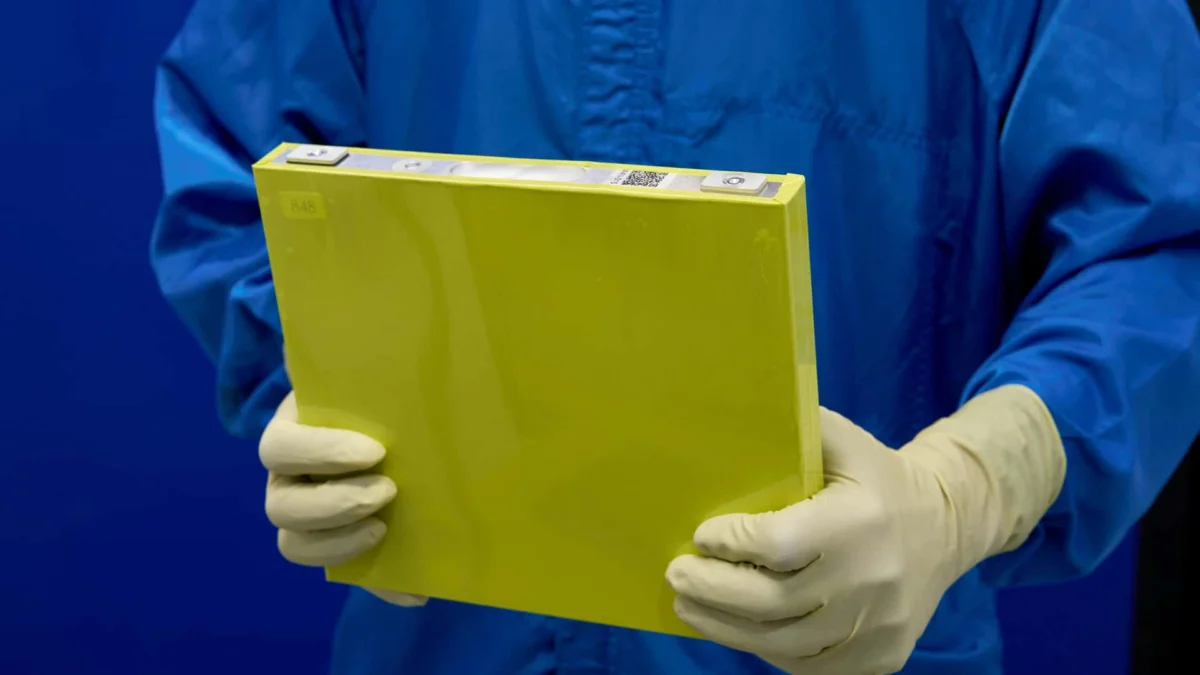
The economic argument for localizing the battery supply chain is rooted in geopolitical security and long-term industrial viability, but the short-term arithmetic is sobering. According to calculations presented in the Bruegel report, the requirement to utilize EU-produced cells instead of more cost-efficient imports could drive production costs from approximately €50 per kilowatt-hour (kWh) to as much as €85 per kWh.
For a standard mid-range electric vehicle equipped with a 60 kWh battery pack, this represents a direct cost increase of €2,100 per unit. Furthermore, proposed mandates regarding the use of low-carbon steel—a move intended to green the manufacturing process—could tack on an additional €200 per vehicle. While the report notes that streamlining bureaucratic vehicle approval processes could theoretically save manufacturers roughly €61 per car, these marginal gains are vastly outweighed by the inflationary pressure of localized battery production. This creates a difficult scenario for automakers: either absorb the costs, which threatens their already strained profit margins, or pass the expenses to consumers, which could stifle the adoption of EVs at the lower end of the market.
Chronology of a Shifting Landscape
The current tension is the result of years of structural shifts within the global automotive industry. Since 2019, the European automotive sector has faced a perfect storm of headwinds. Total vehicle production within the EU has plummeted by 19% over the last five years, reflecting a broader contraction in the market. In 2025 alone, consumers purchased 2.2 million fewer new cars compared to pre-pandemic levels.
This decline occurs against a backdrop of deep concern regarding the future of the European labor market, which currently supports approximately 14 million jobs across the continent. While manufacturers continue to invest heavily—injecting approximately €3 billion per quarter into battery and EV assembly facilities—there is a growing sense of urgency that Europe is losing its competitive edge in technology, supply chain control, and international market share.
The most visible manifestation of this struggle took place at the 2024 Paris Motor Show. European manufacturers, traditionally proud of their engineering heritage and design language, were met with an influx of Chinese competitors offering high-end software integration, luxury-adjacent interiors, and advanced charging architectures. While legacy brands such as BMW and Mercedes-Benz have responded with competitive offerings like the iX3 and the electric GLC, the marketplace is increasingly skeptical of the "familiar badge" premium, as consumers prioritize digital utility and affordability over brand history.
The Struggle for Local Battery Autonomy
Establishing a domestic battery industry capable of rivaling China’s scale and efficiency has proven significantly more difficult than anticipated. The European dream of a "Battery Valley" has faced numerous setbacks, including the high-profile struggles of Swedish manufacturer Northvolt, the decision by Porsche to scale back its internal manufacturing efforts at Cellforce, and the shelving of multiple Advanced Cell (ACC) factory projects.
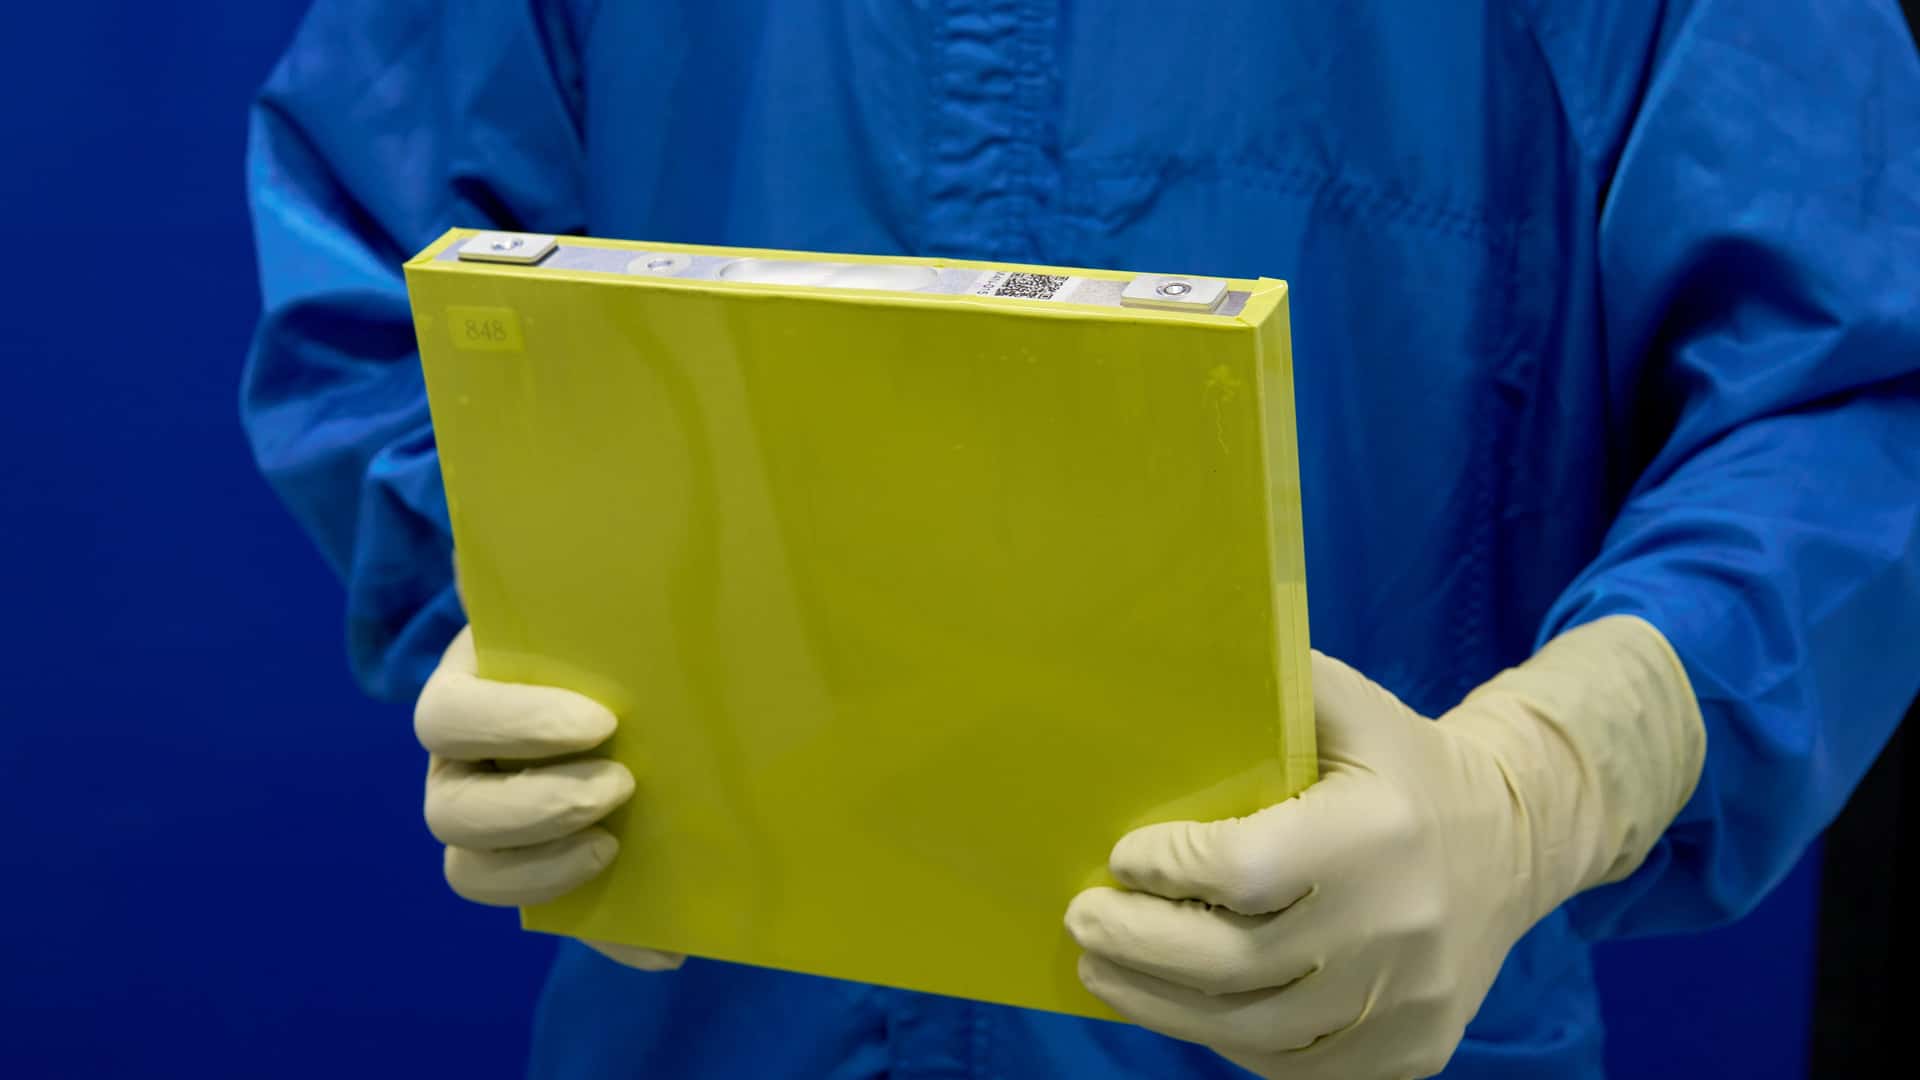
These failures underscore a fundamental reality: even when European firms attempt to manufacture batteries locally, they often remain reliant on equipment, raw materials, and technical expertise sourced from Asia. The reliance on foreign investment is, in fact, a double-edged sword. Current data indicates that South Korean firms own approximately 65% of existing European battery cell manufacturing capacity, while Chinese companies hold a 55% stake in the projects currently under construction. This foreign involvement is not merely a strategic choice but a functional necessity, as European factories struggle to achieve the economies of scale that have made Chinese imports so dominant.
Policy Responses and Market Impacts
In an effort to level the playing field, the European Union has imposed additional duties on Chinese electric vehicles, with some tariffs reaching as high as 35.3%. However, these measures have had complex consequences. While the goal was to shield local manufacturers, the policies have inadvertently accelerated a shift in consumer behavior. Data indicates that while Battery Electric Vehicle (BEV) imports from China have leveled off, imports of plug-in hybrid vehicles—which are not subject to the same strict tariffs—have surged.
Furthermore, the withdrawal of government subsidies has had a disproportionate impact on the market. Research from France suggests that when EVs were excluded from national purchase subsidies, sales for those specific models declined by 60% relative to eligible vehicles. This suggests that the market for EVs remains highly price-sensitive and that any policy-driven increase in MSRP—whether from tariffs or local-content mandates—carries a high risk of slowing the transition to sustainable transport.
Strategic Recommendations: A Managed Path Forward
The Bruegel report suggests that rather than relying solely on aggressive protectionism, the EU should consider more collaborative diplomatic strategies. One proposed solution is a temporary, managed trade agreement with China that would limit the volume of electric cars and plug-in hybrids entering the European market. Such a quota system would provide European manufacturers with a finite window of time to scale their own operations and develop more cost-effective EV architectures without the immediate threat of being undercut by mass-market, budget-friendly imports from Asia.
However, the report warns that this approach comes with its own risks. Historical precedents—such as Europe’s previous limitations on Japanese car imports and Canada’s current restrictive stance on Chinese EVs—demonstrate that protectionist barriers inevitably lead to higher prices for domestic consumers. By shielding local manufacturers from competition, the market loses the downward pressure on prices that typically drives innovation and efficiency.
Broader Implications for the Global Automotive Market
The situation in Europe serves as a microcosm of a larger, global struggle for control over the future of the automotive sector. As nations move to protect their industrial bases, the cost of the green transition is increasingly becoming a matter of political choice.
If the EU proceeds with strict localization requirements, it will likely succeed in securing jobs and insulating its industry from total dependency on foreign rivals. Yet, the cost of this security is high. It threatens to make the entry-level EV segment—the very vehicles necessary to decarbonize the fleet—unaffordable for the average household.
As the industry moves into the latter half of the decade, policymakers face a critical challenge: they must decide whether the priority is to maintain an indigenous manufacturing base at any cost or to foster a competitive, globalized market that delivers the most affordable technology to the consumer. For now, the report from Bruegel serves as a stark reminder that the "Made in Europe" label may soon carry a price tag that goes far beyond the vehicle itself, reflecting the immense cost of pivoting an entire continent’s industrial backbone toward an electrified future.